Gas Engines Market Size & Opportunities Analysis - Growth Strategies, Competitiveness, and Forecasts (2025 - 2032)
This Report Provides In-Depth Analysis of the Gas Engines Market Report Prepared by P&S Intelligence, Segmented by Fuel Type (Natural Gas, Special Gas), Power Output (.5-1 MW, 1-2 MW, 2-5 MW, 5-1 MW, 1-2 MW, Above 2 MW), Application (Power Generation, Cogeneration/CHP, Mechanical Drive), End Use (Utilities, Manufacturing, Oil & Gas, Marine), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Gas Engines Market Outlook
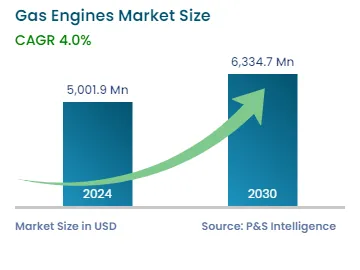
The global gas engines market was valued at USD 5001.9 million in 2024, and it is projected to reach USD 6766.0 million by 2032, growing at a CAGR of 4.0% during 2025–2032.
A gas engine is an internal combustion engine that runs on gaseous fuels, such as natural gas, propane, and methane. In terms of efficiency and emissions, these engines typically perform better than gasoline and diesel engines. They are widely used in generators, pumps, and a lot of other pieces of off-road and on-road machinery.
The rising demand for power from various industries is the major factor propelling the global market. Moreover, the increase in the efficiency of gas engines as the technology advances and the rise in the population are the major factors supporting the market growth.
According to the International Energy Agency (IEA) and Ember’s Global Electricity Review 2024, gas-fired power plants accounted for around 23% of the global electricity generation in 2023. While total global natural gas demand grew in 2023, the IEA notes that this increase was driven by multiple sectors, including power generation, with year-on-year growth varying by region. In many developed economies—such as the U.S. and parts of Europe—aging coal-fired infrastructure, combined with the need to balance variable renewable output, has reinforced the role of natural gas in ensuring grid stability and meeting peak demand.
Gas Engines Market Emerging Trends & Growth Drivers
Technological Advancements in Engine Efficiency Are Key Trends
Modern gas engines achieve higher thermal efficiency through improved combustion chamber design and optimized fuel-air mixing.
Advanced turbocharging and intercooling systems are boosting power output while maintaining fuel efficiency.
Integration of digital monitoring and predictive maintenance tools is enhancing engine reliability and reducing operational downtime.
The development of engines capable of operating on multiple gaseous fuels, including biogas and hydrogen blends, is expanding their applicability.
Enhanced materials and coatings are increasing engine durability, enabling longer service intervals and lower lifecycle costs.
Low-NOx and other emission control technologies are helping engines meet stringent environmental regulations without compromising performance.
As per the latest estimates, in 2022, the electricity and heat production sector was the largest contributor to global greenhouse gas emissions, accounting for approximately 39% of total emissions, which equates to about 16.1 Gigatonnes of COâ‚‚ equivalent.
Growing Demand for Distributed Power Generation Is Driving Market Growth
The rising electricity demand in urban and industrial areas is increasing the need for on-site and localized power generation solutions.
Distributed power generation reduces dependency on centralized grids, lowering transmission losses and improving supply reliability.
Gas engines are well-suited for distributed generation because they offer high efficiency, quick start-up, and the ability to operate at partial loads.
Integration of renewable energy sources like solar and wind is creating demand for flexible backup systems, where gas engines can provide stable and dispatchable power.
North America possesses strong natural gas infrastructure, favorable policies, and increasing demand for backup power in critical sectors like healthcare and data centers
Businesses, hospitals, data centers, and remote facilities are adopting distributed generation to ensure uninterrupted power supply during grid outages.
Advancements in gas engine technology are enabling lower emissions and higher fuel flexibility, making them attractive for distributed applications.
The World Bank estimates that power outages cost businesses in developing countries approximately USD 82 billion annually, driving increased investment in on-site gas engine generation systems as backup and primary power sources.
As of 2024, global natural gas-fired power generation reached a record 6,788 Terawatt-hours (TWh), accounting for 22% of the world's electricity production.
BlackRock finalized a USD 11-billion deal with Saudi Aramco to lease and lease back natural gas processing facilities in the Jafurah basin.
Centrica and Energy Capital Partners agreed to acquire National Grid's Grain LNG terminal for approximately USD 2.04 billion, enhancing the UK's energy security.
Gas Engines Market Segmentation Analysis
Fuel Type Analysis
Natural gas dominated the global gas engines market in 2024 with 55% share. The established natural gas distribution networks in North America, Europe, and parts of Asia-Pacific provide a reliable fuel supply for continuous gas engine operation, supporting both baseload and peaking power applications. Natural gas engines benefit from consistent fuel quality, enabling optimized combustion control and maintenance scheduling that maximizes operational availability.
Special gases, including biogas, landfill gas, and sewage gas, represent the fastest-growing fuel category with an expected CAGR, during forecast period. This growth reflects increasing waste-to-energy project development, supportive renewable energy policies, and growing recognition of organic waste as a valuable energy resource. Global biogas production has expanded significantly, reaching around 445 TWh by 2022, up from 2017 levels, with an average growth rate near 19%. Agricultural operations, wastewater treatment plants, and landfill operators increasingly view gas engines as essential equipment for monetizing waste streams while meeting sustainability objectives.
These fuel types are covered:
Natural Gas (Largest Category)
Special Gas (Fastest-Growing Category)
Biogas
Landfill Gas
Sewage Gas
Others
Power Output Analysis
The 2–5 MW category held the largest market share in 2024, of 30%, reflecting its optimal balance between efficiency, cost-effectiveness, and application versatility across industrial, commercial, and utility-scale projects. Engines in this power range achieve peak electrical efficiencies while maintaining manageable installation complexity and capital costs, making them particularly attractive for distributed generation and industrial CHP applications. Manufacturing facilities, district heating systems, and small-scale utility plants frequently specify 2-5 MW gas engines to match their baseload power requirements while preserving operational flexibility.
The 10–20 MW category will exhibit the highest CAGR, of approx. 4.5%, during 2025–2032, driven by utility-scale power generation projects and large industrial applications requiring substantial on-site generation capacity. These larger engines benefit from economies of scale in both capital and operational costs, achieving the lowest cost per installed kilowatt among gas engine categories. Grid operators increasingly deploy 10-20 MW gas engines for flexible capacity additions, leveraging their rapid start capabilities and excellent part-load efficiency to support renewable energy integration and provide ancillary grid services.
These power outputs are covered:
0.5–1 MW
1–2 MW
2–5 MW (Largest Category)
5–10 MW
10–20 MW (Fastest-Growing Category)
Above 20 MW
Application Analysis
Power generation applications commanded the largest share of the gas engines market in 2024, of 45%. This category encompasses standalone power generation for grid supply, backup power systems, and island mode operations for remote locations. The flexibility of gas engines to operate in various configurations, from single units to multi-engine power plants, enables scalable solutions matching specific power requirements. Utilities and independent power producers particularly value gas engines for their ability to provide fast-responding capacity that complements intermittent renewable energy sources.
The Mechanical drive category is predicted to expand at the highest rate over the projection timeframe. Gas engines as prime movers are used to directly run mechanical equipment, such as pumps, compressors, blowers, chillers, and other rotating equipment. This is why the oil & gas and manufacturing sectors make extensive use of gas engines. Within the oil & gas industry, particularly in LNG plants, gas engines primarily drive the compressors during the gathering, processing, and transmission of the gas.
These application categories are covered:
Power Generation (Largest Category)
Cogeneration/CHP
Mechanical Drive (Fastest-Growing Category)
Others
End Use Analysis
Utilities represented the largest category in 2024, with 40% share. Utility operators appreciate gas engines’ modular nature, enabling phased capacity additions matching demand growth while minimizing capital exposure. The technology's superior operational flexibility compared to large combined-cycle plants makes it particularly valuable for managing daily load variations and providing rapid response to renewable energy fluctuations.
Manufacturing constitutes the fastest-growing category, with a projected CAGR, during 2025–2032, driven by energy-intensive operations seeking greater energy independence and cost predictability. Chemical processing, automotive manufacturing, and textile production facilities increasingly install gas engine systems to reduce grid electricity purchases while capturing waste heat for process applications. The United Nations Industrial Development Organization reports that industrial energy efficiency improvements could reduce global energy demand by 26% by 2040, with CHP systems including gas engines contributing significantly to these gains.
These end use categories are covered:
Utilities (Largest Category)
Manufacturing (Fastest-Growing Category)
Oil & Gas
Marine
Others
Drive strategic growth with comprehensive market analysis
Gas Engines Market Geographical Analysis
Asia-Pacific Gas Engines Market Share
Asia-Pacific dominated the global gas engines market in 2024 with 40% share, and it will exhibit the highest CAGR, during forecast period. The region's manufacturing sector expansion, particularly in China, India, and Southeast Asian nations, creates substantial demand for reliable on-site power generation and CHP solutions. According to ADB projections, Asia and the Pacific will contribute about two-thirds of global energy growth by 2040, reflecting substantial regional demand expansion.
China Gas Engines Market Share
China's commitment to reducing coal dependency while maintaining energy security has accelerated gas engine adoption across industrial and utility applications. The country's natural gas consumption reached 394 billion cubic meters in 2023, growing by 7.2% annually according to the National Energy Administration, with distributed energy systems receiving priority support under national energy policies. Industrial parks throughout China increasingly implement gas engine-based micro-grids, combining multiple units to provide reliable power while achieving economies of scale in operations and maintenance.
The proliferation of industrial estates and special economic zones across Southeast Asia further stimulates regional market growth. Countries including Thailand, Vietnam, and Indonesia actively promote distributed generation to address grid reliability challenges while supporting industrial competitiveness.
North America Gas Engines Market Size
North America represented the second-largest regional market in 2024. The U.S. leads regional demand, with over 85,000 MW of gas-fired distributed generation capacity installed across commercial, industrial, and institutional facilities. Distributed generation deployment, including solar PV, storage, wind, and hybrid systems, is expected to continue expanding robustly in the U.S., supported by cost declines and policy incentives.
The region's emphasis on grid resilience following extreme weather events has accelerated gas engine deployment for critical infrastructure applications. Hospitals, data centers, and water treatment facilities increasingly specify gas engines for primary and backup power, recognizing their superior fuel efficiency and lower emissions compared to diesel alternatives. State-level incentive programs, including California's Self-Generation Incentive Program and New York's Combined Heat and Power Program, provide financial support for gas engine installations, particularly those incorporating renewable gas sources or achieving exceptional efficiency levels.
Europe Gas Engines Market Outlook
Europe maintains a substantial position in the global gas engines market. The region's stringent energy efficiency directives and carbon reduction commitments drive continuous market expansion, particularly in Germany, the U.K., and Nordic countries, where district heating networks create ideal conditions for gas engine CHP deployment. In 2023, combined heat and power (CHP) plants supplied approximately 11% of Europe’s electricity generation. While complete pan-European data for CHP’s share of heat production is not readily available, CHP is widely recognized for its high energy efficiency, particularly when using gas-fired engines.
Germany Gas Engines Market Outlook
Germany's Energiewende transformation and commitment to phasing out nuclear power by 2025 have positioned gas engines as a crucial transitional technology, providing flexible capacity to balance renewable energy variability. As of 2022, Germany had nearly 9,876 biogas plants, with an installed electrical capacity of approximately 5.9 GW, generating around 33.5 TWh of electricity per year. This extensive biogas infrastructure provides a pathway toward carbon-neutral power generation while supporting agricultural economies and waste management objectives.
These regions and countries are covered:
North America
U.S. (Larger Country)
Canada (Faster-Growing Country)
Europe
Germany (Largest Country)
U.K. (Fastest-Growing Country)
France
Italy
Russia
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Region)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country)
Mexico (Fastest-Growing Country)
Rest of LATAM
Middle East and Africa
Saudi Arabia (Fastest-Growing Country)
South Africa (Largest Country)
U.A.E. (Fastest-Growing Country)
Rest of MEA
Gas Engines Market Competitive Landscape
The global gas engine market is characterized by a consolidated structure, with a limited number of established manufacturers holding a significant share of industry activity. High barriers to entry, such as advanced engineering expertise, proven product reliability, and extensive service infrastructure, limit competition from new players. Market growth is increasingly shaped by the adoption of fuel-flexible technologies, including engines capable of operating on biogas, syngas, and hydrogen blends, in response to evolving sustainability goals and regulatory requirements.
Demand is particularly strong in the Asia-Pacific region, where rapid industrialization and infrastructure expansion drive the need for reliable and efficient distributed power solutions. Europe also represents a key market, supported by environmental policies, mature biogas infrastructure, and widespread deployment of combined heat and power (CHP) systems. Utilities remain one of the largest application segments, relying on gas engines for grid stabilization, peak-load management, and backup power in emission-sensitive environments. CHP continues to be a core area of adoption, as it enables high overall energy efficiency by utilizing both electricity and thermal output.
Top Gas Engines Manufacturers:
Caterpillar Inc.
Rolls-Royce plc
General Electric
Volkswagen (MAN Energy Solutions)
Siemens AG
Jenbacher
Cummins Inc.
Mitsubishi Heavy Industries Ltd.
Kawasaki Heavy Industries Ltd.
Ningbo C.S.I. Power & Machinery Group Co. Ltd.
IHI Power Systems
Hyundai Heavy Industries Co. Ltd.
Gas Engines Market Developments
In July 2025, Rolls-Royce plc, in partnership with Duisburger Hafen AG, launched a COâ‚‚-neutral, self-sufficient energy system for the new Duisburg Gateway Terminal. The system features hydrogen-fueled mtu CHP units, battery storage, fuel cells, and smart energy management—delivering both electricity and heat in a green microgrid configuration.
In March 2025, Rolls-Royce plc announced that German Customs has commissioned its new ship, Rügen, which features four mtu gas engines for propulsion and another two for electricity generation. Three additional 55-meter customs vessels are presently under construction at Peene-Werft in Wolgast, northern Germany. Each vessel is set to be outfitted with three 16-cylinder mtu Series 4000 gas engines.
In March 2025, Mitsubishi Heavy Industries (MHI) Group attained rated operation (4,35 kW/1,500min-1) utilizing 100% hydrogen fuel, during a trial run of a 500-kW-class hydrogen engine generator set at the Sagamihara Plant.
In May 2024, INNIO Group launched its Ready for H2 engine platform, enabling operation with up to 100% hydrogen, for future zero-carbon power generation applications across the industrial and utility sectors.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws