This Report Provides In-Depth Analysis of the Automotive Manufacturing Equipment Market Report Prepared by P&S Intelligence, Segmented by Equipment Type (CNC Machines, Robots, Conveyor Belts, Injection-Molding Machines, Stamping Machines, Welding Machines), Mode of Operation Analysis (Automatic, Semi-Automatic), Vehicle Type (Passenger Vehicles, Commercial Vehicles), Application (Body Assembly, Powertrain Manufacturing, Interior Assembly, Final Assembly, Quality Control), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Automotive Manufacturing Equipment Market Outlook
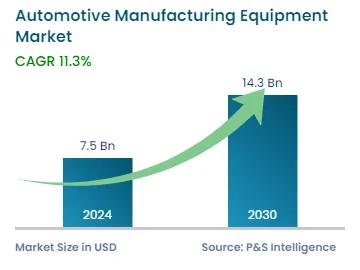
The global automotive manufacturing equipment market was valued at USD 7.5 billion in 2024 and is projected to reach USD 17.5 billion by 2032, expanding at a CAGR of 11.3% during 2025–2032. The market growth is driven by the accelerating shift toward electric vehicles, Industry 4.0 adoption, and the increasing demand for precision manufacturing solutions across global automotive production facilities.
The automotive industry's transformation toward electrification is significantly reshaping manufacturing requirements. According to the International Energy Agency, electric vehicle sales reached 14 million units globally in 2023, representing a 35% increase from the previous year. This surge necessitates specialized manufacturing equipment capable of handling battery assembly, electric motor production, and advanced powertrain systems. Manufacturers are investing heavily in automation technologies to enhance production efficiency, reduce costs, and maintain quality standards required for next-generation vehicles.
Industry 4.0 technologies are revolutionizing automotive manufacturing processes through real-time data analytics, artificial intelligence, and interconnected systems. This technological advancement is driving unprecedented demand for smart manufacturing equipment capable of integrating with digital ecosystems.
The rise of passenger vehicle production globally continues to fuel market expansion. According to the International Organization of Motor Vehicle Manufacturers, global passenger car production reached approximately 67.7 million units in 2024, accounting for 73% of total vehicle output. This robust production volume, combined with the need for manufacturing flexibility to accommodate both traditional and electric powertrains, is creating sustained demand for advanced manufacturing equipment.
Industry 4.0 Integration in Manufacturing Operations Is Key Trend in Market Growth
The automotive manufacturing sector is experiencing a profound transformation through Industry 4.0 technologies, fundamentally changing how vehicles are produced. Smart factories equipped with artificial intelligence, Internet of Things sensors, and real-time analytics are becoming the new standard for competitive automotive manufacturing. According to Acerta, manufacturers implementing AI-powered quality control systems have reduced defect rates by up to 40% while increasing production throughput.
Digital twin technology is enabling manufacturers to simulate and optimize production processes before physical implementation. According to Flex, automotive manufacturers using digital twins during the production part approval process save months of development time and significantly reduce costs. Machine learning algorithms analyze vast amounts of production data to predict equipment failures, optimize maintenance schedules, and improve overall manufacturing efficiency.
The integration of connected systems allows for unprecedented visibility across the entire manufacturing value chain. According to Siemens, automotive plants implementing comprehensive digital manufacturing solutions have achieved a 15–20% improvement in production efficiency and 25% reduction in unplanned downtime. This connectivity enables manufacturers to respond rapidly to market demands and adapt production lines for different vehicle configurations.
Rising Electric Vehicle Production Is Key Driver for Market Growth
The global transition to electric mobility is creating entirely new requirements for automotive manufacturing equipment. Unlike traditional internal combustion engine vehicles, electric vehicles require precision manufacturing for battery assembly, electric motor production, and specialized powertrain components. According to the World Resources Institute, EV manufacturing requires different skill sets and equipment configurations, with battery assembly requiring clean room environments and specialized handling equipment.
Electric motor production requires specialized equipment for winding, assembly, and testing of high-voltage components. According to Rockwell Automation, manufacturers are investing in flexible production lines capable of handling multiple motor configurations and power ratings. The shift from mechanical to electrochemical production processes is driving demand for equipment with enhanced precision capabilities and digital integration features.
As per the International Energy Agency, in 2024, global electric car production reached approximately 17.3 million units, a roughly 25% increase from the previous year. China dominated the output, manufacturing 12.4 million EVs, representing over 70% of global production. The European Union held steady at 2.4 million units, mainly produced by domestic automakers. In North America, total regional output remained flat year-on-year, as a 7% decline in U.S. production was offset by Mexico doubling its EV output to around 220,000 units. These figures reflect a rapid industrial shift toward electrification, with Asian and European manufacturers leading global production momentum.
High Capital Investment Requirements Are Restraining Market Access
The automotive manufacturing equipment market faces significant challenges from substantial capital investment requirements that create barriers for smaller manufacturers and suppliers. The automated equipment can cost anywhere from thousands to millions of dollars, depending on the type and degree of automation required. These high upfront costs often exceed the immediate cost savings from automation, particularly for small and medium-sized enterprises operating in low-volume production environments.
Implementation complexity adds additional financial burden beyond equipment acquisition costs. Companies face unexpected expenses, including development costs for automated processes, preventative maintenance expenses, staff training for operating sophisticated machinery, integration fees, and costs for peripheral equipment, such as end effectors and vision systems. These cumulative costs can significantly impact return on investment calculations and delay equipment adoption decisions.
The challenge is particularly acute for companies transitioning from traditional manufacturing processes to Industry 4.0 systems. Furthermore, integration of new technologies into legacy production lines requires complex planning, technical expertise, and often complete system overhauls. This complexity creates additional risks and costs that many manufacturers, especially smaller operations, struggle to justify in their capital allocation decisions, potentially limiting overall market growth rates.
The CNC machines category held the largest share, of approximately 75%, in the automotive manufacturing equipment market in 2024, it and is expected to maintain its dominant position through 2032. This leadership position stems from the critical role CNC machines play in manufacturing precision automotive components, including engine blocks, transmission parts, chassis elements, and electric vehicle battery housings.
Robots are emerging as the fastest-growing category, with an expected CAGR of 11.5% during 2025–2032, driven by the automotive industry's accelerating adoption of automation technologies. The growing complexity of electric vehicle manufacturing, which requires high-precision repetitive tasks for battery assembly and motor production, is particularly driving robotic system adoption.
These equipment types are covered:
CNC Machines (Largest Category)
Robots (Fastest-Growing Category)
Conveyor Belts
Injection-Molding Machines
Stamping Machines
Welding Machines
Others
Mode of Operation Analysis
The automatic category commanded approximately 65% market share in 2024, and it is also the faster-growing category, driven by the automotive industry's relentless pursuit of efficiency, precision, and cost reduction. Automatic systems enable 24/7 production capabilities, reduce labor costs, and ensure consistent quality output essential for meeting stringent automotive safety and performance standards. According to the U.S. Bureau of Labor Statistics, the number of electric vehicles on roads increased from 22,000 to over 2 million between 2011 and 2021, driving demand for automated production systems capable of handling complex EV manufacturing requirements.
Based on mode of operation, the market has the following categories:
Automatic (Larger and Faster-Growing Category)
Semi-Automatic
Vehicle Type Analysis
The passenger vehicles category held the dominant market share, of approximately 55% in 2024, reflecting the massive global scale of passenger car production. According to the International Organization of Motor Vehicle Manufacturers, passenger car production accounts for approximately 73% of total global vehicle output, reaching 67.7 million units in 2024. This category's dominance is driven by increasing urbanization, rising per capita income, and growing preference for personal mobility, particularly in emerging economies.
The commercial vehicles category is expected to register the faster growth rate with a CAGR of 11.6% during 2025–2032, driven by expanding e-commerce activities, infrastructure development, and the electrification of commercial vehicle fleets. The growing demand for electric delivery vehicles and commercial trucks requires specialized manufacturing equipment capable of handling different powertrain configurations and payload requirements.
Based on vehicle type, the market has the following categories:
Passenger Vehicles (Larger Category)
Commercial Vehicles (Faster-Growing Category)
Application Analysis
The final assembly application holds the largest market share due to its critical role in bringing together all vehicle components into finished automobiles. This application requires sophisticated automation systems, conveyor systems, and quality control equipment to ensure efficient and accurate assembly processes. According to Ford Motor Company, innovative assembly systems like the Ford Universal EV Production System are revolutionizing how vehicles are assembled, transforming traditional assembly lines into flexible, tree-like structures.
The powertrain manufacturing application is experiencing rapid growth, particularly driven by electric vehicle production requirements. Electric powertrains require precision manufacturing for electric motors, battery integration systems, and power electronics. The shift from internal combustion engines to electric powertrains is creating entirely new manufacturing requirements and driving demand for specialized equipment.
Based on application, the market has the following categories:
Asia-Pacific held the largest market share, of approximately 40%, in 2024 and is expected to register the fastest CAGR of 11.9% during 2025–2032. The region's dominance is driven by massive automotive production volumes, rapid industrialization, and significant investments in manufacturing infrastructure. According to Visual Capitalist, China produced over 31 million vehicles in 2024, more than the U.S. and Japan combined, demonstrating the region's manufacturing scale.
The region benefits from favorable government policies supporting domestic automotive manufacturing and electric vehicle adoption. According to ACEA, Chinese car sales reached nearly 23 million units in 2024, accounting for 31% of global car sales. This massive domestic market, combined with growing export capabilities, is driving sustained investment in advanced manufacturing equipment.
India Automotive Manufacturing Equipment Market Growth
India's emergence as a major automotive manufacturing hub is contributing significantly to regional growth. The country's growing middle class, favorable manufacturing policies, and cost-effective skilled labor are attracting significant foreign direct investment in automotive manufacturing infrastructure. As per the Society of Indian Automobile Manufacturers (SIAM), automotive production in the country rose from 28,439,036 units in 2023–24 to 31,034,174 units in 2024–25.
North America Automotive Manufacturing Equipment Market Size
North America maintained a substantial market share of approximately 30.0% in 2024, driven by the region's focus on automotive innovation, electric vehicle adoption, and manufacturing reshoring initiatives. The region's automotive manufacturers are investing heavily in advanced manufacturing technologies to compete with global competitors and meet stringent emission regulations.
U.S. Automotive Manufacturing Equipment Market Size
The U.S. government's focus on domestic electric vehicle production is driving significant investment in manufacturing equipment. According to Rivian Automotive, the company received a conditional commitment for up to USD 6.6 billion from the U.S. Department of Energy to build a USD 5 billion factory in Georgia with a capacity to produce 400,000 SUVs and crossovers. Such investments are driving demand for specialized EV manufacturing equipment.
Europe Automotive Manufacturing Equipment Market Outlook
Europe accounted for approximately 25% of the global market in 2024, with the region's automotive industry undergoing a significant transformation into electrification and digital manufacturing. According to ACEA, EU car production fell by 6.2% in 2024 as the industry adapts to new regulatory requirements and market conditions, but this transition is driving investment in new manufacturing capabilities.
The region's focus on sustainable manufacturing and circular economy principles is driving demand for energy-efficient and environmentally friendly manufacturing equipment. According to Continental AG, the company announced plans to spin off its Automotive sector group by the end of 2025, reflecting the industry's focus on specialization and efficiency improvements.
Germany remains the largest automotive manufacturing equipment market in Europe, driven by the presence of major automotive OEMs and their transition to electric vehicle production. According to McKinsey, European automotive companies are investing heavily in semiconductor capabilities and digital manufacturing technologies to maintain competitiveness against Chinese and American competitors.
Based on geography, the market has the following categories:
North America
U.S. (Larger-Country Market)
Canada (Faster-Growing Country Market)
Europe
Germany (Largest Country Market)
U.K. (Fastest-Country Market)
France
Italy
Spain
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Regional Market)
Japan
China (Largest Country Market)
India (Fastest-Growing Country Market)
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country Market)
Mexico (Fastest-Growing Country Market)
Rest of LATAM
Middle East and Africa
Saudi Arabia (Largest Country Market)
South Africa
U.A.E. (Fastest-Growing Country Market)
Rest of MEA
Automotive Manufacturing Equipment Market Share
The automotive manufacturing equipment market exhibits a consolidated structure, with the top 5 key players collectively holding more than 60% of the total market share, making it a consolidated market. This concentration reflects the high barriers to entry, significant capital requirements, and technological expertise needed to develop and manufacture sophisticated automotive production equipment.
Major companies maintain their competitive positions through continuous innovation, strategic partnerships, and global service networks. The market leaders leverage their extensive experience in automotive manufacturing processes to develop integrated solutions that combine robotics, automation systems, and digital technologies. These companies focus on providing comprehensive manufacturing ecosystems rather than individual equipment pieces.
Leading market players estimate that ABB holds approximately 10% market share in 2024, followed by FANUC Corporation and KUKA AG with significant portions of the remaining market. These companies achieve their positions through superior product quality, extensive global presence, and strong relationships with major automotive OEMs. Their success stems from the ability to provide end-to-end manufacturing solutions that integrate seamlessly with existing production systems.
Key competitive strategies include partnerships with technology providers to integrate artificial intelligence and IoT capabilities into manufacturing equipment. Companies are also expanding their service offerings to include predictive maintenance, remote monitoring, and performance optimization services. The shift toward electric vehicle manufacturing is creating opportunities for companies that can quickly adapt their equipment offerings to meet new production requirements.
The market presents opportunities for companies that can develop flexible, modular manufacturing systems capable of handling both traditional and electric vehicle production. As automotive manufacturers seek to optimize capital utilization, equipment suppliers that offer adaptable solutions for multiple vehicle platforms gain competitive advantages.
Recent strategic activities include technology partnerships, facility expansions, and product portfolio enhancements focused on electric vehicle manufacturing capabilities. Companies are investing heavily in research and development to create next-generation manufacturing equipment that incorporates artificial intelligence, machine learning, and advanced robotics capabilities.
Top Automotive Manufacturing Equipment Manufacturers:
ABB Group
FANUC AMERICA CORPORATION
KUKA AG
Yaskawa Electric Corporation
Kawasaki Heavy Industries Ltd.
AMADA CO. LTD.
AIDA ENGINEERING LTD.
Dürr Group
Schuler Group GmbH
Universal Robots A/S
TGW Logistics Group GmbH
TRUMPF
Automotive Manufacturing Equipment Market News
In February 2025, Dassault Systèmes SA partnered with KUKA AG to integrate its 3DEXPERIENCE platform into KUKA's mosaixx digital ecosystem, enabling virtual twin simulations and real-time data-driven design to enhance robotics and automation efficiency across industries, including automotive.
In November 2024, FANUC Corporation introduced the M-950iA/500 high-performance industrial robot designed for lifting heavy components up to 500 kg. It features a 2,830 mm reach and wide motion range suitable for automotive and construction applications, including welding, drilling, and palletizing.
In October 2024, ABB Ltd. partnered with NAMTECH to launch a School of Robotics in India, focusing on developing industry-focused curricula and hands-on training programs to cultivate a skilled workforce in robotics and automation for the expanding Asian manufacturing sector.
In May 2024, ABB Ltd. launched the IRB 7710 SFX press tending robot, specifically designed for automotive stamping lines. It is capable of handling up to 15 strokes per minute with tilt and shift capabilities for enhanced flexibility in high-volume production environments.
In April 2024, ABB Ltd. announced plans to spin off its Robotics division into a separately listed company by the second quarter of 2026, allowing both entities to sharpen strategic focus and accelerate growth in the rapidly evolving automation market.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws