U.S. CAD Software Market Size & Share Analysis - Emerging Trends, Growth Opportunities, Competitive Landscape, and Forecasts (2026 - 2032)
This Report Provides In-Depth Analysis of the U.S. CAD Software Market Report Prepared by P&S Intelligence, Segmented by Technology (Two-Dimensional Software, Three-Dimensional Software), Model (Solid, Surface, Wireframe), Deployment (On-Premises, Cloud), Level (Pro, Intermediate, Beginner), Application (Aerospace & Defense, Automotive, Manufacturing, Healthcare, Media & Entertainment, Arts), and Geographical Outlook for the Period of 2021 to 2032
Explore the market potential with our data-driven report
U.S. CAD Software Market Overview
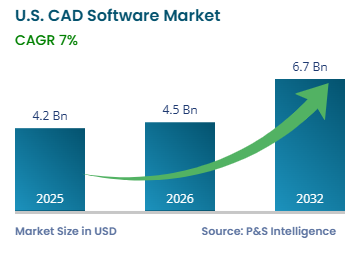
The U.S. CAD software market size was USD 4.2 billion for 2025, and it will grow by 7.0% during 2026–2032, to reach USD 6.7 billion by 2032.
The market is driven by the accelerating integration of three-dimensional modeling, generative design, and cloud-native collaboration tools across aerospace, automotive, and manufacturing design workflows. This integration is positioning CAD platforms as core infrastructure for digital product development nationwide.
The strength of the U.S. manufacturing sector reinforces this demand. The sector's contribution to the nation's GDP reached USD 2.4 trillion in 2023, equal to 10.2% of total GDP. This contribution reflects the continued need for advanced CAD software across product design, engineering, and production environments. The National Institute of Standards and Technology's ongoing digital thread and model-based definition initiatives are also supporting broader adoption of CAD-enabled digital engineering and model-based manufacturing practices among small and medium-sized manufacturers. These initiatives are broadening the addressable base beyond large enterprises.
Key Market Insights
The solid category holds the largest market share, of 60%, in 2025, due to its extensive use in designing manufacturable components across major engineering industries.
The surface category will have the highest CAGR, of approximately 7.7%, driven by growing demand for complex freeform designs across automotive, aerospace, consumer products, and industrial design.
The on-premises category holds the larger market share, of 70% in 2025, driven by strong demand from aerospace and defense manufacturers.
The manufacturing category holds the largest market share, of 35%, in 2025, driven by extensive CAD adoption across product design and production engineering.
South will have the highest CAGR, of approximately 7.9%, driven by expanding automotive and aerospace manufacturing.
U.S. CAD Software Market Trends and Drivers
AI-Integrated and Cloud-Native Design Tools Are Key Trends
Vendors are embedding generative AI, automated feature recognition, and cloud-native collaboration directly into CAD workflows. This integration is shifting the primary purchase criterion from raw modeling power toward integrated design-to-manufacturing intelligence. Autodesk's continued expansion of AI-assisted design generation within its Fusion platform and Siemens' rollout of cloud-based Solid Edge X illustrate how established vendors are re-architecting desktop-first tools into subscription-based, collaborative environments. This transformation is further reflected in Dassault Systemes' November 2025 release of SOLIDWORKS 2026, which introduced AI-powered generative design, enhanced drawing automation, and improved data management capabilities through integration with the 3DEXPERIENCE platform, enabling more intelligent and collaborative product development workflows.
The launch of Autodesk's AI-powered AutoCAD 2026, featuring Autodesk AI enhancements for intelligent drafting, automated workflows, and connected cloud collaboration, demonstrates the industry's shift toward productivity-driven design platforms that integrate artificial intelligence directly into engineering workflows. This shift is compressing design iteration cycles and enabling geographically distributed engineering teams to co-edit models in real time rather than exchanging static files. This transformation is expected to continue reshaping purchasing behavior through 2032. Organizations are increasingly adopting cloud-enabled and hybrid CAD environments alongside existing on-premises deployments.
Aerospace and Advanced Manufacturing Expansion Are Biggest Drivers
Sustained growth in aerospace, defense, and advanced manufacturing employment is fueling CAD software demand, as many engineering and product development roles rely on licensed CAD platforms for design, modeling, and engineering workflows. The U.S. Bureau of Labor Statistics estimates that employment of aerospace engineers will grow 6% from 2024 to 2034, faster than the average for all occupations. This growth is supporting continued demand for engineers with proficiency in 3D modeling and CAD-based product development.
Combined with continued reshoring of automotive and electronics manufacturing capacity, this workforce growth is expanding the addressable seat base for CAD vendors beyond incumbent installed accounts. This expansion is reinforcing multi-year revenue visibility even as per-seat pricing faces competitive pressure from cloud-native entrants.
Skilled Engineering Workforce Shortages Is Key Restraint
A persistent shortage of skilled design engineers is constraining the pace at which manufacturers can adopt and fully utilize advanced 3D and solid-modeling CAD platforms. The National Association of Manufacturers reports that the U.S. manufacturing sector could face a shortfall of up to 1.9 million skilled workers by 2033. Employers continue to cite talent attraction and retention among their most significant business challenges.
This workforce shortage is challenging for manufacturers adopting advanced digital engineering workflows, where proficiency in 3D CAD, simulation, and model-based design requires specialized training and practical experience. Vendors are responding with simplified interfaces and AI-assisted modeling tools aimed at lowering the skill threshold. This constraint is expected to persist through the medium term as engineering education and workforce development struggle to keep pace with industry demand.
Healthcare's Shift toward Patient-Specific Design Is Biggest Opportunity
Healthcare's transition toward patient-specific, CAD-designed implants and surgical guides is opening a growth pathway beyond CAD software's traditional industrial base. The U.S. Food and Drug Administration provides regulatory guidance for additively manufactured medical devices, with numerous 3D-printed orthopedic, craniomaxillofacial, and dental products reviewed and cleared through established regulatory pathways, including the 510(k) process. This regulatory clarity is encouraging medical device manufacturers to invest in surgical-planning CAD software that converts patient CT and MRI scans into manufacturable 3D models, a workflow increasingly adopted for orthopedic, dental, and craniomaxillofacial applications.
Moreover, Materialise introduced its fully integrated Mimics platform in December 2024. This platform combines AI-enabled segmentation, cloud collaboration, and patient-specific device design into a unified workflow that enables hospitals and medical device manufacturers to accelerate personalized treatment planning and product development. As personalized medicine expands, CAD vendors offering healthcare-specific modeling, segmentation, and surgical planning capabilities are well positioned to capture growth opportunities within a historically underpenetrated end market.
U.S. CAD Software Market Segmentation Analysis
Technology Analysis
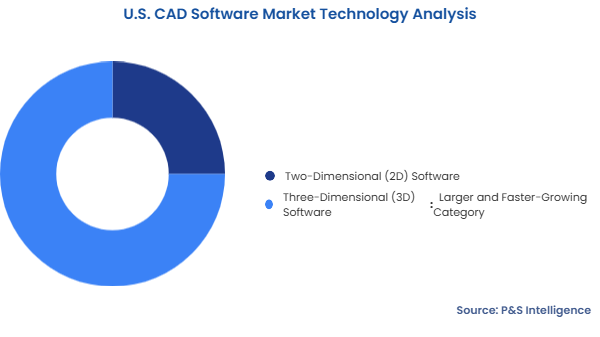
The three-dimensional (3D) software category holds the larger market share, of 75%, in 2025, and it will have the higher CAGR, of approximately 7.2%, driven by increasing adoption of digital product development, simulation-based engineering, additive manufacturing, and digital twin technologies across aerospace, automotive, industrial equipment, electronics, and medical device manufacturing. The U.S. National Institute of Standards and Technology highlights that small and medium-sized manufacturers are increasingly adopting digital manufacturing and design technologies to improve productivity, product quality, and operational efficiency. This adoption reinforces demand for advanced 3D CAD software across U.S. manufacturing industries.
The technologies analyzed in this report are:
Two-Dimensional (2D) Software
Three-Dimensional (3D) Software (Larger and Faster-Growing Category)
Model Analysis
The solid category holds the largest market share, of 60%, in 2025, driven by its role as the foundational geometric representation for manufacturable, closed-volume parts across aerospace, automotive, industrial equipment, and precision engineering. The National Institute of Standards and Technology contributed a new hybrid geometric modeling capability to ISO 10303 (STEP), the internationally adopted standard for product data interoperability. This contribution strengthens support for the exchange of complex solid models across CAD, CAE, and manufacturing systems.
The surface category will have the highest CAGR, driven by rising demand for freeform, aesthetically complex geometry in automotive exteriors, aerospace structures, consumer products, and advanced industrial design applications. Dassault Systemes' continued enhancements to its CATIA platform, including advanced Class-A surfacing and generative design capabilities, support this growth. These capabilities enable manufacturers to develop increasingly complex products with greater design precision and engineering efficiency.
The models analyzed in this report are:
Solid (Largest Category)
Surface (Fastest-Growing Category)
Wireframe
Deployment Analysis
The on-premises category holds the larger market share in 2025, driven by the continued reliance on locally hosted infrastructure among aerospace and defense manufacturers handling export-controlled technical data. The National Institute of Standards and Technology's SP 800-171 framework, which governs protection of Controlled Unclassified Information on contractor systems, drives many defense-sector CAD users toward tightly controlled, self-managed environments.
The cloud category will have the higher CAGR, of approximately 7.4%, driven by commercial and mid-market manufacturers prioritizing remote collaboration, subscription flexibility, and reduced IT overhead, drawing these manufacturers away from legacy on-premises installations. Moreover, Autodesk's continued expansion of its cloud-based Fusion platform reinforces this momentum. The platform integrates CAD, CAM, CAE, and collaborative product development within a unified environment, and it enables engineering teams to design and iterate more efficiently across distributed workflows.
The deployment types analyzed in this report are:
On-Premises (Larger Category)
Cloud (Faster-Growing Category)
Level Analysis
The intermediate category holds the largest market share, of 65%, in 2025, driven by its widespread adoption by small and medium-sized manufacturers, engineering service providers, architectural firms, and product design companies, as these organizations require 3D modeling capabilities without the complexity and cost of professional-tier platforms. The U.S. National Institute of Standards and Technology highlights that small and medium-sized manufacturers are increasingly adopting digital manufacturing and design technologies to improve productivity, quality, and operational efficiency. This adoption is supporting continued demand for intermediate-level CAD solutions across the U.S. industrial base.
The pro category will have the highest CAGR, driven by engineering teams increasingly adopting advanced simulation, generative design, model-based engineering, and digital twin capabilities that require professional-tier CAD platforms. The U.S. Bureau of Labor Statistics projects mechanical engineering employment to grow by 9% from 2024 to 2034, supporting sustained demand for advanced CAD software. This outlook reinforces long-term demand for advanced CAD solutions across manufacturing, aerospace, automotive, and industrial engineering applications.
The levels analyzed in this report are:
Pro (Fastest-Growing Category)
Intermediate (Largest Category)
Beginner
Application Analysis
The manufacturing category holds the largest market share, of 35%, in 2025, driven by the scale of the domestic manufacturing base, which relies on CAD for product design, prototyping, tooling, and production engineering. According to the National Institute of Standards and Technology, manufacturing value added reached a seasonally adjusted annual rate of approximately USD 2.93 trillion in the third quarter of 2024, accounting for about 10% of U.S. gross domestic product. This scale highlights the breadth of design-intensive production activities that support demand for CAD software.
The healthcare category will have the highest CAGR, driven by patient-specific implant design, surgical planning, and medical device development increasingly relying on CAD-based segmentation of CT and MRI imaging data. The increasing adoption of 3D-printed patient-specific medical devices and digital surgical planning workflows across orthopedic, dental, and craniomaxillofacial applications supports this growth.
The applications analyzed in this report are:
Aerospace & Defense
Automotive
Manufacturing (Largest Category)
Healthcare (Fastest-Growing Category)
Media & Entertainment
Arts
Others
Drive strategic growth with comprehensive market analysis
U.S. CAD Software Market Regional Outlook
West CAD Software Market Size
West holds the largest market share, of 40%, in 2025, driven by dense clusters of aerospace, semiconductor, and advanced industrial design activity across California and Washington. The U.S. Bureau of Labor Statistics (BLS) reports that the Los Angeles–Long Beach–Anaheim metropolitan area is among the nation's largest employment centers for aerospace engineers, while Washington remains a leading hub for commercial aircraft design and manufacturing, reinforcing the West region's concentration of aerospace design and engineering activities that drive demand for advanced CAD software.
The U.S. Census Bureau's 2024 Manufacturing Week analysis highlights California as one of the nation's leading semiconductor manufacturing states, reinforcing the region's position as a center for advanced electronics design and engineering. This concentration of design-intensive aerospace and semiconductor firms sustains elevated demand for advanced 3D, solid-modeling, and professional-grade CAD software across the region. The West is expected to retain its leadership as continued investment in semiconductor fabrication, aerospace innovation, and digital engineering strengthens its technology ecosystem.
South CAD Software Market Size
South will have the highest CAGR, of approximately 7.9%, supported by sustained automotive and aerospace manufacturing investment across Texas, Georgia, and the broader Southeast. According to the U.S. Bureau of Economic Analysis, Texas generated USD 330.8 billion in manufacturing gross domestic product in 2024, the highest among all U.S. states. This output reinforces the region's expanding role in advanced manufacturing and engineering activities that rely extensively on CAD software.
Moreover, the lower operating costs and expanding production capacity continue to draw automotive and aerospace suppliers toward Texas, South Carolina, and Tennessee. This pull is accelerating CAD software adoption among mid-market manufacturers building new design and engineering capabilities in the region.
The regions analyzed in this report are:
Northeast
Midwest
West (Largest Category)
South (Fastest-Growing Category)
U.S. CAD Software Market Share Analysis
The market is semi-consolidated, with a limited number of established vendors accounting for a large share of enterprise deployments across manufacturing, aerospace, automotive, architecture, engineering, and industrial design. Companies such as Autodesk, Dassault Systemes, Siemens Digital Industries Software, PTC, and Bentley Systems maintain leading market positions. Comprehensive product portfolios anchor these positions, recurring subscription revenue models sustain them commercially, and deep integration with engineering and manufacturing workflows embeds these vendors within customer operations. Additionally, the presence of specialized software developers offering cloud-native CAD, industry-specific design solutions, and niche applications for electronics, healthcare, and infrastructure keeps the market competitive. High switching costs and long-term enterprise contracts strengthen the position of leading vendors, while integration with PLM and digital engineering ecosystems deepens this advantage. Smaller providers continue to find room for innovation within this structure.
Key Players in the U.S. CAD Software Market:
Autodesk, Inc.
Dassault Systemes SE
Siemens AG
PTC Inc.
Bentley Systems, Incorporated
Trimble Inc.
Hexagon AB
Nemetschek SE
Vectorworks, Inc.
Graebert GmbH
ZWSOFT Co., Ltd.
Bricsys NV
U.S. CAD Software Market News
In May 2026, Autodesk, Inc. entered into a definitive agreement to acquire MaintainX for approximately USD 3.6 billion in an all-cash transaction. The acquisition extends Autodesk's design-to-operations platform by connecting CAD-originated product data with real-world maintenance workflows.
In May 2026, PTC Inc. announced that the U.S. Army designated its Windchill product lifecycle management solution as the service's official Enterprise Product Data Management (ePDM) platform. The designation positions Windchill as the authoritative system of record for CAD-linked product data across Army weapon system development and sustainment.
In January 2026, Bentley Systems, Incorporated completed the acquisitions of Talon Aerolytics and the technology and technical expertise of Pointivo, strengthening its Asset Analytics portfolio. The deals extend Bentley's digital-twin and AI capabilities into telecommunications tower and road-network infrastructure design.
In December 2025, Trimble Inc. launched SketchUp AI, adding AI-assisted rendering and object-generation capabilities to its design software. The launch targets faster concept visualization for architecture, construction, and product design workflows.
Frequently Asked Questions About This Report
What is driving the growth of the U.S. CAD Software Market?+
The market is primarily driven by the increasing adoption of digital engineering, Industry 4.0, smart manufacturing, and product lifecycle management (PLM), which require advanced CAD software for efficient product design and development.
How is artificial intelligence transforming CAD software?+
Artificial intelligence is enhancing CAD software through generative design, automated modeling, design optimization, feature recognition, and predictive engineering, enabling engineers to reduce design time and improve product performance.
Why are businesses adopting cloud-based CAD software?+
Organizations are adopting cloud-based CAD software to enable real-time collaboration, remote access, centralized data management, automatic software updates, and lower infrastructure and maintenance costs.
Which industries are the primary users of CAD software in the United States?+
CAD software is widely used across manufacturing, automotive, aerospace & defense, architecture, engineering & construction (AEC), industrial equipment, electronics, and healthcare device manufacturing for design, simulation, and documentation.
How is CAD software supporting smart manufacturing initiatives?+
CAD software supports smart manufacturing by integrating with digital twins, simulation, CAM, PLM, IoT, and automated production workflows, enabling faster product development, improved design accuracy, and more efficient manufacturing processes.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws