This Report Provides In-Depth Analysis of the Thermoplastic Polyester Engineering Resins Market Report Prepared by P&S Intelligence, Segmented by Product Type (Polybutylene Terephthalate, Polyethylene Terephthalate, Polycyclohexylene Dimethylene Terephthalate), Application (Automotive, Electrial Appliances, Food & Beverage, Industrial Equipment), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Thermoplastic Polyester Engineering Resins Market Future Outlook
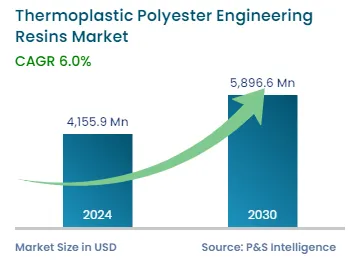
The thermoplastic polyester engineering resins market size was USD 4.2 billion in 2024, and it will grow by 6.0% during 2025–2032, to reach USD 6.6 billion by 2032.
This is primarily ascribed to the rising usage of these resins for a broad range of nonstructural applications because they can be used without filters and are normally harder and more ductile than thermoset resins. Moreover, these are easy to recycle and widely available to fulfill domestic needs. The increasing requirement from the electronics and automobile industries is also rapidly boosting the growth of the industry.
Polyester is widely used in textiles for clothing, home furnishings, and industrial fabrics due to its strength and durability. It is also used in plastic bottles (PET), packaging, films, and automotive parts. Its resistance to shrinking, stretching, and wrinkling makes it ideal for a range of consumer and industrial applications.
The automotive industry's shift toward electric vehicles has emerged as a significant growth catalyst for thermoplastic polyester engineering resins. These materials offer exceptional mechanical strength, chemical resistance, and dimensional stability while contributing to vehicle weight reduction, a critical factor in enhancing electric vehicle range and efficiency. Travel range refers to the distance an EV can cover on a fully charged battery, which is a critical factor influencing people to buy an EV or not. This makes vehicle weight reduction essential for enhancing efficiency and range. A reduction of 1 kg in vehicle weight can increase the driving range by approximately 0.05 to 0.13 km. For a medium-sized EV, a 10% reduction in weight could lead to a 6–10% increase in range, depending on the vehicle's design and usage patterns.
In addition, polyethylene terephthalate and polybutylene terephthalate engineering resins have high performance and a high molecular weight that can be turned into functional parts and components, which are used in diversified assemblies of industries such as electrical/electronics, automotive, industrial equipment, and appliances. Moreover, these resins can be shaped any way, when soft, and they retain that shape after hardening. This engineering plastic increases the strength of materials when it is combined with carbon nanotubes and glass fiber. Thus, TPER companies are focusing on capturing new application areas of the product.
Sustainability and Circular Economy Initiatives Are Key Trends
Environmental sustainability is a key trend shaping the thermoplastic polyester engineering market.
Global plastic pollution has reached crisis levels, with over 400 million tonnes of plastic produced annually, of which over 14 million tonnes end up in oceans each year.
Only 9% of plastic waste is recycled, while 79% accumulates in landfills or the environment, threatening ecosystems and human health.
Manufacturers are increasingly focusing on developing recyclable and bio-based thermoplastic polyester variants to meet stringent environmental regulations and corporate sustainability targets.
2025 is a pivotal year for plastics recycling, while major initiatives and commitments focused on improving recycling and creating a circular economy for plastics have designated this year as a key milestone to meet sustainability goals.
This sustainability focus has led to increased research and development investments in chemical recycling technologies and the incorporation of recycled content in thermoplastic polyester engineering resins, creating a circular economy model for these high-performance materials.
The development of thermoplastic polyester resins from renewable or bio-based sources is gaining attention to reduce the carbon footprint.
The use of TPER in lightweight automotive and electronic components contributes to energy efficiency and lower emissions, supporting broader sustainability goals.
Environmental regulations, such as EU REACH and RoHS, are encouraging manufacturers to adopt recyclable and environmentally friendly TPER materials.
Corporate sustainability targets and ESG initiatives by major automotive, electronics, and packaging companies are driving the adoption of recyclable and circular TPER solutions.
Automotive Lightweighting Initiatives Are Biggest Driver
The automotive industry's relentless pursuit of lightweight materials represents the primary growth driver for the thermoplastic polyester engineering resins market.
As of the most recent data, global transportation emissions total about 8.5 to 9.0 Gigatonnes of COâ‚‚ equivalent per year, which accounts for roughly 15% of the total global greenhouse gas emissions.
In the automotive sector, thermoplastic polyester alloys are used in manufacturing interior and exterior components.
Thermoplastic polyester engineering resins, including polybutylene terephthalate (PBT) and polyethylene terephthalate (PET), are increasingly replacing traditional metals in automotive applications due to their superior strength-to-weight ratio and design flexibility.
According to OICA, a total of 92,504,338 automobiles were produced worldwide in 2024.
As OEMs move toward EVs, the propulsion system and infrastructure also add a significant weight penalty.
As per the IEA, in 2024, global electric vehicle sales surged to 17 million units, marking over a 25 % increase from 2023.
EV batteries are significantly heavier than internal combustion engines, driving manufacturers to incorporate more plastic into more components like the chassis and battery casings, to partially offset that additional battery weight, a technique known as compensatory lightweighting.
This trend has accelerated the adoption of thermoplastic polyester engineering resins in under-the-hood components, electrical systems, and structural parts.
Major automotive manufacturers are increasingly utilizing these materials in applications ranging from engine covers and air intake manifolds to electrical connectors and sensor housings, where high temperature resistance and dimensional stability are crucial.
Leading automotive OEMs worldwide are investing to replace metals with high-performance polymers in both internal and external vehicle components.
Global manufacturers are adopting compensatory lightweighting strategies in electric vehicles, characterized by the usage of thermoplastic polyester resins in chassis, battery casings, and structural parts, to offset heavier EV batteries.
The polyethylene terephthalate category held the largest market share, of 60%, in 2024, and it will have the highest CAGR, driven by its increasing adoption in electrical and electronics applications, where their superior electrical properties, transparency options, and excellent dimensional stability provide significant advantages. PET, made up of ethylene glycol (EG) and terephthalic acid (TPA), is the most used thermoplastic polymer across the globe. Its demand is increasing due to its mechanical and electrical features, and it is widely used in switches, motor housings, sensors, and other electrical systems.
In addition, polyethylene terephthalate is used in the synthetic fiber, electronics, food & beverage, automotive, textile, and food packaging industries. In the textile industry, semi-crystalline plastic and naturally colorless properties are hiking its demand for making clothes. Further, when it is mixed with cotton, it reduces the shrinking and wrinkling and builds the fabric more resistant to drops of water.
Moreover, the demand for PET is also growing, due to the increasing need from the healthcare and 3D printing sectors. It offers high performance and other benefits, such as high rigidity, high melting point, and low moisture. Further, it is FDA-approved for food contact products. It is also used to manufacture food containers, beverage bottles, and other packaging materials.
The product types analyzed in this report are:
Polybutylene Terephthalate
Polyethylene Terephthalate (Largest and Fastest-Growing Category)
Polycyclohexylene Dimethylene Terephthalate
Application Analysis
The automotive category held the largest market share, of 45%, in 2024, and it will have the highest CAGR. This dominance reflects the automotive industry's extensive use of thermoplastic polyester engineering resins in both traditional and electric vehicle applications, ranging from under-the-hood components to interior and exterior parts. In addition, thermoplastic polyester engineering resins are high-performance materials, flexible in shape, and have high chemical tolerance, which help automakers cut the cost of production and reduce wastage. These resins are not only more cost-effective than metals but also enable automakers to make their vehicles more efficient by delivering endurance, corrosion resistance, high-temperature resistance, shatterproof, strength, good current tolerance, maximum output at a cheaper cost, and flexibility in construction.
The applications analyzed in this report are:
Automotive (Largest and Fastest-Growing Category)
Electrical Appliances
Food & Beverage
Industrial Equipment
Drive strategic growth with comprehensive market analysis
Asia-Pacific held the largest market share, of 40%, in 2024, and it will have the highest CAGR, of approx. 6.5%. This is mainly ascribed to the rising need for electronics and automobiles in the region. The demand for automobiles is rapidly increasing in regional countries such as India, China, Australia, and Indonesia. Moreover, India’s economy is expanding on the back of its electrical, automotive, and consumer electronics sectors. Thus, this factor drives the demand for plastics, which, in turn, boosts the TPER market growth. Furthermore, these resins are broadly adopted to increase the durability of fibers and glass plastics. For instance, the adoption of glass plastics in the manufacturing industry is increasing, which is expected to boost the thermoplastic polyester engineering resins market in the region.
Government-backed initiatives, such as India’s Production-Linked Incentive (PLI) scheme for electronics manufacturing, are further accelerating the regional demand for TPER in the automotive, electrical, and consumer electronics sectors. Recycling programs and stricter environmental regulations in China and India are also promoting the use of sustainable engineering plastics. Data from the Society of Indian Automobile Manufacturers (SIAM) shows that in 2023–24, India produced 5.06 million passenger vehicles, 1.03 million commercial vehicles, and 23.88 million two-wheelers—contributing significantly to its position as the fourth-largest global auto producer.
China Thermoplastic Polyester Engineering Resins Market Size
China is the largest consumer and manufacturer of engineering resins in the Asia-Pacific region. The low cost of production and the largest supplier of raw materials have supported the country to be the largest producer of thermoplastic polyester engineering resins. The Made in China 2025 initiative supports advanced manufacturing and encourages the adoption of new materials and engineering plastics across high-value sectors. According to the China Association of Automobile Manufacturers (CAAM), 2024 saw record-breaking auto output of 31.282 million vehicles and sales of 31.436 million units, rising 3.7% and 4.5% year-on-year. New energy vehicles (NEVs) reached 12.888 million produced and 12.866 million sold, growing 34.4% and 35.5%.
North America Thermoplastic Polyester Engineering Resins Market Size
The North American market is expected to witness a significant growth rate during the forecast period. This can be mainly attributed to the presence of key industry players, the surging demand for recycled plastics, and the rising focus on fuel-efficient cars, due to which manufacturers are widely using TPER to make their vehicles lightweight. Also, the region has the presence of several manufacturers of engines, components, equipment, and other materials, and it is known for aircraft production. The stringent Corporate Average Fuel Economy standards in the U.S. and similar regulations in Canada are forcing automotive OEMs to adopt lightweight, high-performance engineering plastics.
U.S. Thermoplastic Polyester Engineering Resins Market Size
The U.S. market is predicted to experience significant growth in the coming years, with several factors driving the market. Increasing demand for automotive components is predicted to be a primary driver of the global market throughout the forecast period. The region's market growth is propelled by the rapid adoption of electric vehicles and stringent fuel efficiency standards that necessitate lightweight materials.
The geographical breakdown of the market is as follows:
North America
U.S. (Largest Country)
Canada (Fastest-Growing Country)
Europe
Germany (Largest Country)
U.K. (Fastest-Growing Country)
France
Italy
Spain
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Regional Market)
The market is fragmented due to the presence of numerous international and regional players, each holding relatively small market shares. While major companies such as BASF SE, DuPont, Toray Industries, and Celanese have strong capabilities and brand recognition, they compete along with many mid-sized and niche manufacturers specializing in specific grades, applications, or regions. Additionally, diverse end-use industries, including automotive, electronics, packaging, and consumer goods, require tailored solutions, enabling smaller suppliers to remain competitive.
Top Thermoplastic Polyester Engineering Resin Manufacturers:
In January 2024, BASF SE launched its largest thermoplastic polyurethane facility at the Zhanjiang Verbund site. The intelligent factory uses advanced technologies, such as automated guided vehicles and sophisticated automation systems, allowing BASF to satisfy the increasing demand for recyclable Elastollan TPU in the industrial, e-mobility, and new energy sectors of APAC.
In January 2024, Mitsubishi Chemical Group began sampling the NOVADURAN ZR Series, a foaming grade of PBT resin with ultra-low specific gravity. They were trialed in the production of lightweight, rigid components, including automotive parts, without complex processes or specialized molding equipment. This will contribute to weight reduction, better fuel efficiency, and lower COâ‚‚ emissions.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws