Get a Comprehensive Overview of the Satellite Launch Vehicle Market Report Prepared by P&S Intelligence, Segmented by Orbit (GEO, MEO, LEO), Launch Activity (Commercial, Government & Military), Payload (Nano and Micro (0–200 Kg), Small (201–1,200 Kg), Medium (1,201–2,200 Kg), Large (above 2,201 Kg)), Application (Communication, Earth Observation & Remote Sensing, Space Exploration, Surveillance & Reconnaissance) Launch (Single-Use/Expendable, Reusable), Stage (Single, Multistage), and Geographic Regions. This Report Provides Insights from 2019 to 2030.
Explore the market potential with our data-driven report
Satellite Launch Vehicle Market Future Prospects
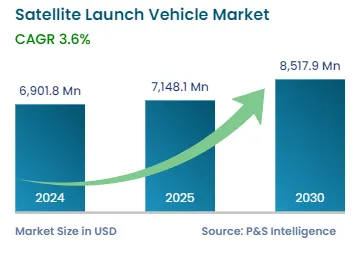
The global satellite launch vehicle market is valued at an estimated USD 6,901.8 million in 2024, and it will advance with a CAGR of 3.6% during 2024–2030, to reach USD 8,517.9 million by 2030. The increasing number of launches of satellites for communication purposes, weather forecasting, earth observation, and military purposes is fueling the market expansion. Moreover, the growing trend of reusable launch vehicles, for cutting costs and achieving reliable and on-demand space access, is boosting the growth of the satellite launch vehicle industry.
Technological Developments Are Latest Market Trends
The implementation of AI and machine learning in the development of SLVs is a key market trend.
AI improves mission efficiency by reducing downtime, itself by speeding up physical detection and diagnosis.
In addition, AI can help in simplifying the assembly and testing of these vehicles, to further save cost and time and optimize the manufacturing process.
Furthermore, SLVs’ communication and navigation systems can be assisted by AI to help astronomers.
Other trends, including the development of small launch vehicles to carry small satellites, thus saving operational cost and investments in hardware development, are supporting the market growth.
Growing 5G Satellite Communication Market Is Key Market Driver
The global continues to expand, boosted by the increasing launches of communication satellites.
According to the Union of Concerned Scientists, of the 6,718 working satellites in the earth’s orbit in December 2023, 4,823 were communication satellites.
Technological advancements and the surge in the need for high-speed connectivity with low latency drive the demand for 5G communications via satellites.
5G networks are playing a critical role in assisting governments and policymakers in creating smart cities, thereby allowing inhabitants to participate and realize the socioeconomic benefits provided by an advanced, digital, data-intensive economy.
With such developments, the demand for SLVs is predicted to expand in the coming years.
In addition, the increasing defense expenses by developing countries, such as India, China, and South Korea, for advancing the defense communication technology, is the major growth driver for the industry growth.
Moreover, with the increasing number of internet users all over the world, a huge amount of data is being generated, which further makes the satellite spectrum highly crowded and congested.
This drives the demand for satellites, further fueling the market growth.
High Cost of Rockets Hampers Market Growth
Rockets for space missions are extremely costly to manufacture, from R&D and simulation to component production and final integration.
Additionally, their safety and reliability are of great concerns for governments, which is why the regulations imposed on manufacturers are strict.
Complying with them requires extensive expertise and system testing, which adds to the overall costs.
To be able to launch satellites for critical applications, such as telecommunications, broadcasting, navigation, weather monitoring, and military purposes might necessitate design modifications in the launch vehicles.
Additionally, numerous companies operate in this market with advanced technologies and decades of experience, which restrains new companies from accessing it.
Another key concern associated with satellite launch vehicles is air pollution.
While NASA uses liquid hydrogen and oxygen in its rockets, which cause no GHG emissions, other public and private space agencies still rely on petroleum- and chemical-based fuels.
For instance, SpaceX’s Falcon 9 uses kerosine and liquid oxygen, while Starship uses methane, all of which release GHGs upon ignition.
Hence, the race to create sustainable rockets will demand even more investment than currently, thus restraining the growth of the market to some extent.
Satellite Launch Vehicle Market Analysis
Orbit Analysis
The market is dominated by the LEO category, with around 50% revenue share in 2024. It is also the fastest-growing category, with 3.6% CAGR. Satellites operating in LEO offer faster communications and low-latency networking and are easy to set up, thus ideal for deployment. Moreover, huge investments by government and private organizations are being made to deploy satellites in LEO. For instance, Space Exploration Technologies Corp. is developing the “Starlink” satellite internet constellation in the low earth orbit. Further, according to a private organization, there are about 3,700 satellites in LEO.
Furthermore, the GEO category is set to follow LEO, as satellites made for the geostationary orbit offer superior telecommunication and observation functionalities. According to the same source, there are about 560 GEO satellites orbiting the earth.
The following orbits have been considered:
GEO
MEO
LEO (Largest and Fastest-Growing Category)
Launch Activity Analysis
With 75% market share in the satellite launch vehicle market, the commercial category dominates the launch activity segment. It will also be the fastest-growing category in the forecast period, with 4.0% CAGR.
This can be attributed to the growing number of commercial satellite launches, in tune with the commercialization of space exploration programs. The growing commercial activities, including satellite navigation, satellite television, and commercial satellite imagery, along with the decreasing costs for launch and space hardware, are the major reasons for the category’s domination.
The report offers insights into these launch activities:
Commercial (Larger and Faster-Growing Category)
Government & Military
Payload Analysis
The nano and micro payload category holds the largest revenue share, in 2024, and it will also witness the highest CAGR, over this decade. The growth in the number of nanosatellites and the integration of composites to reduce satellite weight will propel the use of nano and micro payload launch vehicles. As it is not feasible to carry small payloads in large launch vehicles, as larger rockets cost more to manufacture and operate, launch vehicles specially designed to carry nano and microsatellites are expected to offer market players lucrative opportunities in the forecast period.
The segment is categorized as follows:
Nano and Micro (0–200 kg) (Largest and Fastest-Growing Category)
Small (201–1,200 kg)
Medium (1,201–2,200 kg)
Large (above 2,201 kg)
Application Analysis
Communication applications dominate the market in 2024. This is primarily due to the increasing need for 5G and satellite connections in several commercial fields, such as logistics and shipping, automobiles, and civilian aircraft. Moreover, the increase in internet users and volume of data, together with the increasing demand for low-latency transmission, are driving the market category.
The highest CAGR, of 4.2%, is expected in the earth observation & remote sensing category. This is attributed to the growing demand for accurate weather forecasting and government’s rising focus on environmental monitoring, urban planning, and disaster management. Moreover, earth observation is done for military surveillance purposes and to offer high-resolution commercial satellite imagery for diverse applications, from navigation to project progress monitoring.
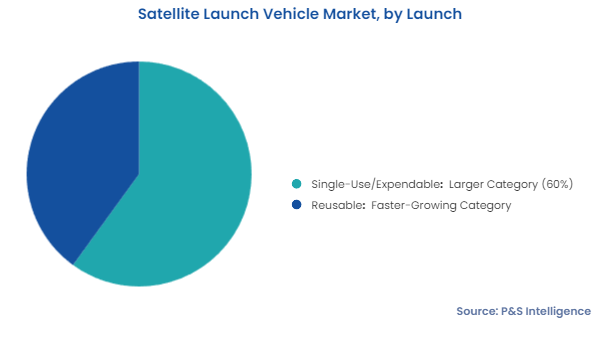
The single-use/expendable category holds the larger share, of 60%, in 2024 as these vehicles emerged earlier than reusable ones. This is why they have been the traditional choice of space exploration companies for launching satellites and other kinds of payloads into space.
The reusable bifurcation will grow faster, over the forecast period. This is attributed to the lower cost of developing these rockets as the same one can be used repeatedly. SpaceX’s Falcon 9 is partially reusable, while the Starship is fully reusable. Amidst the growing competition in the space launch industry, where cost is key, reusable rockets can offer cost-effective services to satellite owners and operators.
Below are the segment categories:
Single-Use/Expendable (Larger Category)
Reusable (Faster-Growing Category)
Stage Analysis
The multistage bifurcation is both the larger and faster-growing category. Because they are larger, multistage rockets can carry more fuel, thus offering the ability to put satellites in higher orbits. They can also carrier heavier loads and multiple satellites, which can offer cost-effectiveness in case more than one satellite needs to be launched in short time. Saturn V (NASA), Ariane 1, 2, and 4 (ESA), and GSLV and PSLV (ISRO) are all multistage rockets.
The segment is divided as below:
Single
Multistage (Larger and Faster-Growing Category)
Drive strategic growth with comprehensive market analysis
Regional Analysis
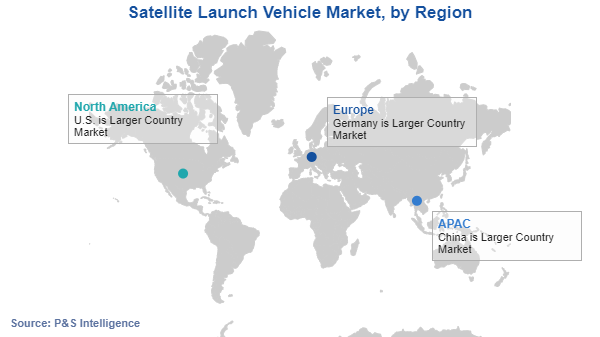
North America leads the satellite launch vehicle market, with a revenue share of around 45% in 2024, which can be attributed to the growing commercial launch activity in the region.
Furthermore, the presence of major market players is contributing to the region’s dominance.
Additionally, the continent’s advanced technologies and availability of a large pool of technically skilled workers are fueling the region’s market progress.
The U.S. is home to both NASA and SpaceX, two of the foremost space exploration companies in the world.
Additionally, out of the 6,718 satellites orbiting the earth in December 2023, 4,511 belonged to the U.S. 56 to Canada.
The U.S. is also home to almost all of the satellite and launch vehicle manufacturers, as well as major commercial operators, such as SpaceX, Iridium, ORBCOMM, Viasat, and Globalstar.
These companies, the DoD, NOAA, and NASA widely use these satellites for commercial and military purposes.
APAC is expected to grow the fastest in the industry, with a CAGR of 4.6%, during the forecast period.
This can be attributed to the growing satellite launches in the region for communication and space exploration purposes.
Furthermore, the increasing government investment and participation of private players in the industry, to develop the 5G network, has significantly boosted the market.
India, China, and Japan are regional leaders in space exploration, with numerous satellites in orbit, many placed in orbit via indigenously developed launch vehicles.
All these countries are bolstering their defense capabilities, for which remote earth monitoring is vital.
The regional breakdown of the market is as follows:
Brazil (Largest and Fastest-Growing Country Market)
Mexico
Saudi Arabia
South Africa
U.A.E.
Rest of LAMEA
Satellite Launch Vehicle Market Share
The market is consolidated as space launch vehicles are not easy to develop, requiring years of expertise and tonnes of money. This is why only a few major companies are able to manufacture rockets at scale for commercial and government satellite launches. Moreover, due to the expensive and critical nature of rockets, satellites, and space exploration programs in general, users generally preferred the established players.
In recent years, players operating in the satellite launch vehicle market have been involved in several strategic and technological developments in order to achieve industry dominance. Some of the strategic measures taken by the players are product development and innovation, partnerships and collaborations, and business expansions and investments.
Key Manufacturers of Satellite Launch Vehicles:
Space Exploration Technologies Corp. (SpaceX)
Blue Origin Enterprises L.P.
Innovative Solutions in Space B.V. (ISISPACE)
Mitsubishi Heavy Industries Ltd.
Northrop Grumman Corporation
The Boeing Company
Indian Space Research Organisation (ISRO)
Japan Aerospace Exploration Agency (JAXA)
National Aeronautics and Space Administration (NASA)
European Space Agency (ESA)
Lockheed Martin Corporation
State Corporation for Space Activities (Roscosmos)
Satellite Launch Vehicle Market News
In August 2024, SpaceX launched 23 Starlink satellites into LEO on the Falcon 9 from the Kennedy Space Center at Cape Canaveral, Florida.
In February 2024, Innovative Solutions in Space B.V. (ISISPACE) announced SATORO PTE. LTD. as its distributor for small satellite projects in Southeast Asia.
In October 2023, Blue Origin Enterprises L.P. unveiled the Blue Ring spacecraft platform with multiple mission capabilities, including transportation, hosting, refueling, logistics, data relay, and in-space cloud computing. The platform can accommodate satellites and other kinds of payload weighing over 3,000 kg in total.
In October 2023, Mitsubishi Heavy Industries Ltd. and Viasat signed bilateral agreements with the UK Space Agency (UKSA) and Japan Aerospace Exploration Agency (JAXA) for the development of the InRange in-orbit telemetry relay service, which Mitsubishi’s H3 launch vehicle will act as the demonstration platform for.
Frequently Asked Questions About This Report
What will be the revenue of the satellite launch vehicle market by 2030?+
In 2030, the market for satellite launch vehicles will value USD 8,517.9 million.
What is the biggest satellite launch vehicle industry trend?+
Technological advancements are trending in the satellite launch vehicle industry.
What is the nature of the satellite launch vehicle market?+
The market for satellite launch vehicles is consolidated.
Which orbit has the highest satellite launch vehicle industry value?+
Low earth orbit dominates the satellite launch vehicle industry.
What is the most-lucrative region in the satellite launch vehicle market?+
APAC has the highest CAGR in the market for satellite launch vehicles.
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws