This Report Provides In-Depth Analysis of the Plasticizers Market Report Prepared by P&S Intelligence, Segmented by Product Type (Phthalates, Non-Phthalates, End Use), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Plasticizers Market Outlook
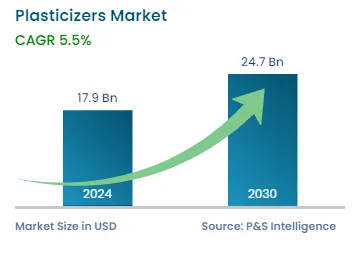
The global plasticizers market is estimated to have generated revenue of USD 17.9 billion in 2024, and it is expected to grow at a CAGR of 5.5% during the forecasted period, to reach USD 27.2 billion by 2032. This is because the foremost end user of such products, i.e., the construction industry, is growing significantly across the world, wherein the demand for flexible polymers like PVC is high.
In addition, the rise in the adoption of non-phthalates, an inflated molecular weight of phthalate plasticizers, increased growth of such materials in the packaging industry, and high need for polymers in the consumer goods sector are driving the market. Furthermore, the steady growth occurred globally in their demand, due to the rising requirement for plastic-based products in various industries, such as automotive, construction, packaging, and textiles; and ongoing investigations and growth attempts to make plasticizers safer and more sustained.
Moreover, the production of PVC necessitates some chemicals for softness, such as dioctyl phthalate (DOP), diisononyl phthalate (DINP), dioctyl terephthalate (DOTP), and dibutyl phthalate (DBP). The growth of the plasticizers sector is forecasted to push the development of bio-based plasticizers and new applications of the plasticizers. Some of the popular types that are available and extremely used in the market include terephthalates, phthalates, epoxies, and aliphatics. Due to the increasing requirement for eco-friendly plasticizers to safeguard both the environment and human health, the demand for eco-friendly plasticizers is ballooning rapidly.
Shift toward Non-Phthalate and Bio-Based Plasticizers Is Key Trend
The shift toward non-phthalate and bio-based plasticizers has become one of the defining trends in the global plasticizers market, fundamentally reshaping both production and consumption patterns. For decades, phthalates such as di(2-ethylhexyl) phthalate (DEHP) and dibutyl phthalate (DBP) dominated the market due to their cost-effectiveness and versatility. However, mounting evidence linking certain low-molecular-weight phthalates to endocrine disruption, reproductive toxicity, and environmental persistence has led to a wave of regulatory bans and restrictions in major markets like the European Union, North America, and parts of Asia. This regulatory landscape is pressuring industries to pivot toward safer, eco-friendly alternatives.
One of the most-prominent alternatives is the class of non-phthalate plasticizers, including Diisononyl cyclohexane-1,2-dicarboxylate (DINCH), Di(2-ethylhexyl) terephthalate (DOTP), and trimellitates. They are now widely used in sensitive applications such as medical devices, food-contact packaging, and children’s toys, where safety standards are extremely stringent. Companies like Evonik (with its ELATUR® series), Eastman (with Eastman 168™), and BASF are leading in scaling up these formulations. The adoption rate of such plasticizers is rising as downstream manufacturers aim to align with regulations such as REACH in Europe and CPSC standards in the U.S., which explicitly restrict hazardous phthalates.
Simultaneously, the industry is witnessing rapid growth in bio-based plasticizers, which are derived from renewable feedstocks like soybean oil, castor oil, epoxidized vegetable oils, citrates, and even algae. These not only reduce dependence on fossil resources but also lower carbon footprints in line with global sustainability targets. Bio-based plasticizers often exhibit comparable or even superior properties in terms of thermal stability, migration resistance, and biodegradability. Their adoption is especially strong in markets where green building certifications (e.g., LEED, BREEAM) and corporate ESG commitments drive material selection.
Rising Construction & Infrastructure Development Is Driver for the Market Growth
The construction and infrastructure sector is the largest consumer of plasticizers, accounting for a major portion of global demand, particularly in applications such as flooring, roofing membranes, wall coverings, pipes, and cables. Rapid urbanization, population growth, and government-backed housing and infrastructure projects are significantly boosting the use of flexible PVC, which heavily relies on plasticizers to enhance flexibility, durability, and weather resistance. For example, plasticized PVC pipes are widely used in water supply, sewage, and drainage systems due to their cost-effectiveness and long service life compared to alternatives like metal or concrete.
Governments across the globe are investing in large-scale infrastructure programs, such as smart cities, affordable housing schemes, and renewable energy projects. In Asia-Pacific, China and India are leading the demand surge, with urban housing, metro rail, and renewable energy installations fueling PVC consumption. In the Middle East, initiatives under Saudi Vision 2030 and U.A.E.’s infrastructure diversification plans are further accelerating construction activity, creating sustained demand for plasticizers in flooring, wall finishes, insulation materials, and industrial piping. Similarly, infrastructure renewal in Europe and North America, including upgrades to water distribution networks and energy grids, is generating new opportunities for plasticizers.
The growing trend of sustainable and green building materials is also shaping demand. Plasticizers are crucial in manufacturing eco-friendly PVC products that comply with international construction safety and environmental standards. Non-phthalate and bio-based plasticizers are increasingly being adopted in flooring and interior applications to meet stringent regulations on emissions and indoor air quality. This trend aligns with the rising demand for LEED-certified and energy-efficient buildings, further embedding plasticizers as essential additives in construction.
Moreover, the shift toward modern construction technologies, such as prefabricated buildings and modular construction, has amplified the use of flexible polymers and composites. Plasticized materials offer ease of installation, reduced maintenance, and resilience under extreme conditions, making them indispensable in high-speed construction projects. This is particularly evident in developing economies where rapid infrastructure rollout demands cost-efficient yet durable solutions.
Volatility in Raw Material Prices Is Hampering Market Growth
One of the most significant challenges confronting the global plasticizers market is the volatility of raw material prices, since most conventional plasticizers are synthesized from petrochemical derivatives. Feedstocks such as phthalic anhydride, adipic acid, isophthalic acid, and alcohols like 2-ethylhexanol and butanol are directly tied to crude oil and natural gas markets. Any fluctuation in oil prices, driven by geopolitical instability, OPEC production decisions, or disruptions in supply chains, immediately translates into higher or unstable costs for plasticizer manufacturers. This cost unpredictability complicates production planning and pricing strategies, eroding profitability for producers.
Additionally, the issue is further compounded by the globalized nature of chemical supply chains. Many regions, particularly in Asia-Pacific, depend heavily on imports of certain feedstock chemicals. For example, supply bottlenecks in Europe or the Middle East can create ripple effects across Asian markets, leading to price spikes and shortages. Logistics disruptions, such as the COVID-19 pandemic’s port closures or the recent Red Sea shipping crisis, have highlighted how fragile these supply chains can be. Such events add to cost instability and force companies to absorb higher input expenses or pass them on to customers, reducing competitiveness.
Plasticizers Market Segmentation Analysis
Product Analysis
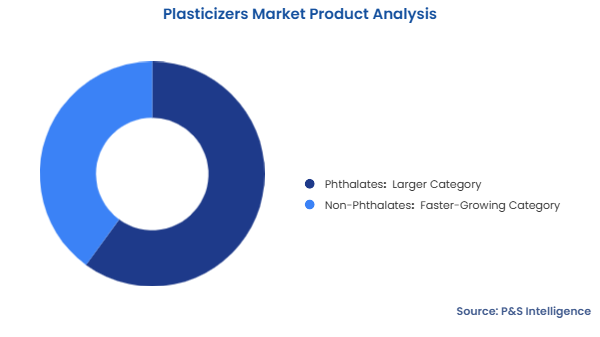
The phthalates category dominates the market with 60% value share in 2024, and it is projected to witness the same trend in the expected future as well. This is because phthalates have high presentation properties, such as low transition temperature, strong solvent, low volatility, stability, low diffusion, flame retardance, flexibility, durability, and improved processing characteristics; are the most frequently utilized type of plasticizer in different industries; and are available at an economic cost.
Moreover, it is the most commonly used by SMEs because it is economical. To have plasticity in plastic materials, phthalates add durability and transparency and are operated along with PVC materials. Also, these can enhance the performance of plastics by transmitting beneficial properties including softness, workability, and elasticity.
The non-phthalates category is projected to witness the faster growth in the plasticizers market during the forecast period. This can be due to their prominent outcome features and are used as an alternative to phthalate plasticizers, due to their advantages like flexibility, durability, and environment-friendliness. In comparison with traditional plasticizers and compatibility with recycled plastics, non-phthalates are attractively considered due to their improved performance, are less toxic in nature, and are considered safer alternatives to use in materials.
Based on product type, the market has the following categories:
The wires & cables category accounted for the largest market value share in 2024, of 30%, and is set to remain in the leading place during the forecast period. This is due to the increasing demand for electrical devices in different countries and the surging usage of wires and cables in various industries such as automotive, construction, and electrical and electronics. The manufacturing of wires and cables necessitates the usage of a huge capacity of PVC to provide better protection and insulation.
The films & sheets category is forecasted to witness the highest CAGR during the prediction period. This can be ascribed to the rising demand for packed food and beverages, which are laminated by plasticizer-based films and sheets, and the increasing use of protective coatings for other products. Moreover, plasticizers enhance the flexibility and effects of films and sheets, which make them more usable for several end-use applications. To meet the evolving consumer needs and industry requirements, important aspects such as formability, appearance, and barrier properties of films and sheets are considered.
Based on end use, the market has the following categories:
Wires & Cables (Largest Category)
Flooring, Roofing, & Cladding
Films & Sheets (Fastest-Growing Category)
Automotive Parts
Medical Equipment
Toys & Child Care Products
Others
Drive strategic growth with comprehensive market analysis
Plasticizers Market Geographical Analysis
Asia-Pacific Plasticizers Market
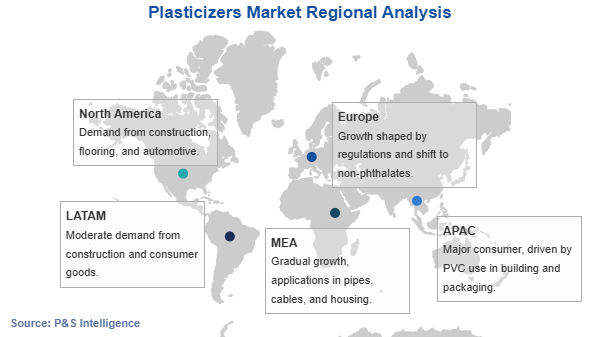
The APAC plasticizers market accounted for the largest revenue of with the highest market share of 45%, in 2024 and it will have the highest CAGR, of 5.7%. The presence of several growing end-use sectors, such as electrical and electronics, manufacturing, infrastructure, aerospace, building & construction, automotive, healthcare, and chemical, in countries like India, Indonesia, Japan, South Korea, China, Australia, and various other Southeast Asian nations, which are boosting the requirement for plasticizers for various applications.
Moreover, the APAC market is expected to witness high demand for plasticizers in the future, owing to the surging need for electrical and electronic components, the increasing adoption of mobile phones, and the rising consumption of such chemicals in the construction and packaging industries, in the region. In addition, industry contributors are also taking a range of strategic ambitions to extend their universal footprint, with main market developments such as new product launches, predetermined agreements, mergers and acquisitions, expanding investments, and alliances with other organizations. Thus, competitors in the plasticizer industry offer lucrative items to increase and get through in a progressively competitive and surging market environment.
China Plasticizers Market
China holds the largest share in the APAC plasticizers market. According to PlasticsEurope, China’s PVC production was 12.1 million tonnes in 2017, which jumped to 21 million tonnes in 2022. The demand for the PVC products is expected to increase in a differentiated array of end-use industries. Furthermore, emerging economies and their corresponding rapid urbanization and industrialization are leading to an increase in infrastructural development, renovation, and refurbishment activities. The rapid development boosts the growth of various sectors, such as automotive and construction, in turn, positively affecting the plasticizers market. It is expected to grow in the future owing to the high investments in transportation, energy, and housing projects, reconstruction of real estate properties, increasing tourism activities, and infrastructure development.
China’s dominance in the market is due to the significant growth in its automotive and construction industries. According to the Organisation Internationale des Constructeurs d’Automobiles (OICA), the total number of vehicles produced by China in 2024 was 31,281,592, out of which 27,476,886 cars and 3,804,706 commercial vehicles. This high-volume automobile manufacturing generated a significant demand for instrument panels and associated moldings, sun visors, synthetic leather seat coverings, headlining, seals, mud flaps, noise and vibration reduction components, floor coverings, exterior side moldings, and protective strips. The PVC used to manufacture these automobile components requires plasticizers, such as DOTP, DOA, and DOP, for flexibility and softness.
The geographical breakdown of the market is as follows
North America
U.S. (Larger-Country Market)
Canada (Faster-Growing Country Market)
Europe
Germany (Largest Country Market)
U.K. (Fastest-Country Market)
France
Italy
Spain
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Regional Market)
Japan
China (Largest Country Market)
India (Fastest-Growing Country Market)
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country Market)
Mexico (Fastest-Growing Country Market)
Rest of LATAM
Middle East and Africa
Saudi Arabia (Largest Country Market)
South Africa
U.A.E. (Fastest-Growing Country Market)
Rest of MEA
Plasticizers Market Share Analysis
The plasticizers market is generally fragmented, owing to the presence of a large number of regional and international manufacturers competing across diverse end-use industries. Applications such as construction, automotive, packaging, consumer goods, medical, and electrical/electronics create a wide scope, allowing multiple players to establish their presence without any single company dominating the global landscape. This diversity in applications and geography makes the overall market competitive, with fragmented shares distributed among various producers.
However, fragmentation does not mean the market lacks structure—leading global chemical companies such as BASF SE, Evonik Industries, ExxonMobil, and LG Chem continue to hold strong positions due to their large-scale production capacities, integrated value chains, and broad product portfolios. Despite this, their market shares remain moderate, as smaller regional firms and specialized producers maintain significant footholds in local markets by offering cost-effective or application-specific solutions.
In contrast, the bio-based plasticizers segment shows signs of consolidation. With increasing regulatory restrictions on phthalate-based products and rising demand for sustainable alternatives, only a handful of companies with advanced R&D and technological expertise have been able to commercialize eco-friendly plasticizers successfully. This has allowed major players in this sub-segment to secure a comparatively larger share of the market. As regulatory frameworks tighten, this segment may see further consolidation as established chemical giants and innovative niche firms expand their portfolios through acquisitions or partnerships.
Key Plasticizers Companies:
UPC Technology Corporation
BASF SE
Evonik Industries AG
Exxon Mobil Corporation
Eastman Chemical Company
Nan Ya Plastics Corporation
Mitsubishi Chemical Corporation
LG Chem Ltd.
KLJ Group
Arkema SA
Perstorp Holding AB
Lanxess AG
Plasticizers Market News
In May 2025, LG Chem introduced ultra-high-molecular-weight PVC with improved flame resistance, heat stability, and flexibility, designed for use in electric vehicle charging cables.
In March 2025, BASF SE entered into a long-term agreement with Braven Environmental LLC for the supply of advanced recycled feedstock. The material, derived from mixed plastic waste, will be used to partially replace fossil-based resources at the BASF TotalEnergies Petrochemical facility in Port Arthur, Texas. Braven will supply the feedstock from a planned multi-unit facility in Texarkana, Texas.
In February 2025, BASF SE expanded its North American plasticizer portfolio to include biomass-balanced and Ccycled grades from production sites in Pasadena, Texas, and Cornwall, Ontario. The products and facilities have received ISCC PLUS certification.
In October 2024, Evonik Industries AG announced plans to expand production capacity for its non-phthalate PVC plasticizers, di-isononyl-1,2-cyclohexanoate (DINCH) and di-isononyl-1,4-cyclohexane-dicarboxylate (DINCD), at its Marl, Germany site. DINCH is used in medical device applications, while DINCD is applied in vinyl floorings and other flexible PVC uses.
In August 2024, BASF SE and UPC Technology Corporation signed a memorandum of understanding for the supply of plasticizer alcohols and catalysts for phthalic anhydride and maleic anhydride. The agreement also covers collaboration on reducing carbon emissions in related operations and products.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws