Lung Cancer Surgery Market Size & Share Analysis - Trends, Drivers, Competitive Landscape, and Forecasts (2026 - 2032)
This Report Provides In-Depth Analysis of the Lung Cancer Surgery Market Report Prepared by P&S Intelligence, Segmented by Surgical Procedures (Thoracotomy, Minimally Invasive Surgeries), Product Type (Surgical Instruments, Monitoring & Visualizing Systems, Endosurgical Equipment), End User (Cancer Hospitals, Ambulatory Surgical Centers, Research Laboratories), and Geographical Outlook for the Period of 2021 to 2032
Explore the market potential with our data-driven report
Lung Cancer Surgery Market Future Outlook
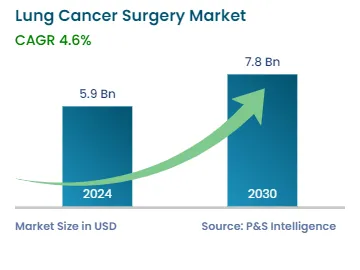
The lung cancer surgery market size was USD 6.1 billion for 2025, and it will grow by 4.7% during 2026–2032, to reach USD 8.4 billion by 2032.
The growth can be primarily attributed to the rising incidence of lung cancers, extensive tobacco smoking trend among youngsters, rising geriatric population, and availability of reimbursements. According to the International Agency for Research on Cancer (IARC), lung cancer accounted for approximately 2.6 million new cases globally in 2024, making it the most frequently diagnosed cancer worldwide and reinforcing sustained demand for surgical intervention, particularly for patients eligible for curative treatment. This growing disease burden is increasing the number of patients requiring surgical evaluation, particularly those diagnosed at early and localized stages where surgery remains the preferred curative treatment.
In addition, the expansion of lung cancer screening programs and growing awareness of early diagnosis are enabling timely surgical intervention, thereby improving patient outcomes and increasing procedure volumes. Moreover, the growing emphasis on the early diagnosis and treatment of this condition, growing adoption of minimally invasive procedures as well as robotic surgeries, and rising pace of technological advancement in the associated surgeries will propel the growth of the market during the forecast period.
Key Market Insights
The thoracotomy category holds the larger market share of 75% in 2025, due to its continued use for advanced and complex lung cancer surgeries requiring open surgical access.
The monitoring & visualizing systems category will have the highest CAGR, of approximately 5.0%, driven by rising adoption of intraoperative imaging technologies that improve tumor margin identification and lymph node localization.
The ambulatory surgical centers category will have the highest CAGR of approximately 5.2%, driven by the increasing adoption of minimally invasive thoracic procedures and the shift toward outpatient surgical care.
North America holds the largest market share of 40% in 2025, driven by the high incidence of lung cancer, technological advancements, increasing tobacco use, and early screening initiatives.
Asia-Pacific will have the highest CAGR of approximately 5.6%, supported by improving healthcare infrastructure, rising adoption of minimally invasive surgeries, and expanding cancer screening and treatment services.
Lung Cancer Surgery Market Trends & Drivers
Robotic-Assisted and Minimally Invasive Platforms Are Key Trends
The center of gravity in lung cancer surgery continues to shift from open thoracotomy toward video-assisted thoracoscopic surgery (VATS) and robotic-assisted thoracoscopic surgery (RATS). The clinical benefits of these minimally invasive techniques, including smaller incisions, reduced chest wall trauma, shorter hospital stays, lower postoperative complication rates, and faster recovery, are accelerating their adoption. As surgeon expertise and hospital investment in advanced surgical technologies continue to grow, robotic-assisted surgery has become a standard approach at many high-volume thoracic centers.
According to the Cleveland Clinic's 2025 Thoracic Surgery Outcomes Report, 92% of lobectomies performed for stage I lung cancer in 2024 were completed using video- or robot-assisted thoracoscopic surgery, demonstrating the widespread adoption of minimally invasive surgical platforms. This trend is driving demand for robotic surgical systems, high-definition visualization platforms, endoscopic staplers, and advanced thoracic surgical instruments, while encouraging hospitals to further expand their minimally invasive thoracic surgery capabilities.
Expanded Screening Eligibility and Rising Incidence Are Biggest Drivers
The expansion of lung cancer screening eligibility criteria is structurally driving surgical volumes upward. Earlier tumor identification under these expanded criteria increases the proportion of patients who qualify for curative-intent resection rather than systemic therapy alone. Broader screening access translates directly into a larger addressable surgical population, including lobectomy and sub-lobar resections for early-stage disease.
According to a 2025 study published by the American Association for Cancer Research (AACR), using 2022 Behavioral Risk Factor Surveillance System (BRFSS) data, 17.24% of U.S. adults eligible for lung cancer screening underwent low-dose CT screening. This uptake reflects the continued implementation of the revised U.S. Preventive Services Task Force screening criteria. The increasing uptake of LDCT screening is enabling earlier diagnosis of lung cancer and expanding the pool of patients eligible for curative surgical resection. This expanding pool is driving demand for thoracic surgical procedures, advanced surgical instruments, and robotic-assisted surgical systems, supporting sustained market growth.
High Capital Costs and Unproven Incremental Outcomes Are Key Restraints
Despite the growing adoption of robotic-assisted thoracic surgery, high capital acquisition costs, ongoing maintenance expenses, per-procedure consumable costs, and extensive surgeon training requirements continue to constrain adoption among small and mid-sized hospitals. Healthcare providers must carefully balance these investments against budget limitations and competing capital priorities, especially where established video-assisted thoracoscopic surgery (VATS) already delivers favorable clinical outcomes at a lower cost.
Recent peer-reviewed studies indicate that robotic-assisted thoracic surgery continues to incur higher procedural costs than VATS while providing largely comparable perioperative and oncological outcomes for many patients. Healthcare providers, especially in resource-constrained healthcare systems, often prioritize the more cost-effective VATS approach and delay investments in robotic surgical platforms, restraining demand for robotic surgical systems, advanced thoracic surgical instruments, and related accessories.
Government-Led Screening Expansion in Emerging Markets Is Biggest Opportunity
Beyond established Western markets, government-sponsored screening infrastructure in Asia-Pacific is opening a growth pathway for surgical device and instrument manufacturers. As national screening programs mature in China and India, previously undiagnosed early-stage patients are increasingly being identified as surgical candidates. This shift is creating demand for both conventional and minimally invasive surgical capacity in historically underserved markets.
In 2024, China introduced the Lung Cancer Screening and Early Diagnosis and Treatment Program to standardize nationwide low-dose CT (LDCT) screening, early diagnosis, and treatment for high-risk populations. The program recommends annual LDCT screening for high-risk individuals aged 50–74 years to improve early detection and timely surgical intervention. The expansion of organized screening programs is increasing the number of patients diagnosed at resectable stages. This growing patient pool is driving demand for thoracic surgical procedures, advanced surgical instruments, and robotic-assisted surgery systems.
Lung Cancer Surgery Market Segmentation Analysis
Surgical Procedure Analysis
The thoracotomy category holds the larger market share of 75% in 2025, due to its continued use for advanced and complex lung cancer surgeries requiring open surgical access. Its critical role in managing advanced-stage tumors, centrally located lesions, and anatomically complex cases that require open surgical access continues to support this dominance. The high procedural volume of thoracotomy-based lobectomies and other major lung resections continues to drive demand for surgical instruments, stapling devices, retractors, and powered surgical equipment across hospitals and specialized cancer centers. In March 2024, Intuitive Surgical received U.S. FDA clearance for the da Vinci 5 Surgical System. The system's enhanced computing capabilities and improved surgeon ergonomics strengthen the adoption of advanced thoracic surgical technologies for lung cancer treatment.
The minimally invasive surgeries category will have the higher CAGR of approximately 4.9%, owing to the increasing usage of these procedures, advancement in their technologies, favorable reimbursement regulations, and growing trend of robot-assisted surgical operations. The segment is witnessing the fastest growth due to its ability to reduce postoperative pain, shorten hospital stays, minimize surgical complications, accelerate patient recovery, and improve overall clinical outcomes compared with conventional open surgery, encouraging wider adoption across hospitals and cancer centers.
The surgical procedures analyzed in this report are:
The surgical instruments category holds the largest market share of 60% in 2025. This can be ascribed to the rising volume of surgeries for lung cancer due to its high incidence and the increasing government funding for cancer diagnosis and treatment. In addition to that, the advances in surgical instruments considerably increase their versatility and simplify their usage during complex operations. Moreover, the advent of the powered and tissue-specific endoscopic stapling technology, which offers the advantage of better resource usage, lower cost, and improved clinical outcomes over manual staplers, has revolutionized the field. For instance, in November 2025, Medtronic plc launched the Signia Circular Stapler with Tri-Staple Technology, expanding its intelligent stapling portfolio with enhanced tissue compression and staple-line performance for complex surgical procedures, including thoracic and lung cancer surgeries.
The monitoring & visualizing systems category will have the highest CAGR, driven by rising adoption of intraoperative imaging technologies that improve tumor margin identification and lymph node localization. A National Institutes of Health-funded study demonstrated that near-infrared fluorescence imaging enabled real-time intraoperative visualization of thoracic anatomical structures during both open and video-assisted thoracic procedures, supporting expanding clinical use of visualization-based systems.
The product types analyzed in this report are:
Surgical Instruments (Largest Category)
Hand Instruments
Staplers
Forceps
Retractors
Rib Shears
Trocar
Cutters
Clamps
Scissors
Elevators
Powered Surgical Equipment
Monitoring & Visualizing Systems (Fastest-Growing Category)
Cameras & Video Support
Endoscopic Trocars with Optical Views
Endosurgical Equipment
End User Analysis
The cancer hospitals category holds the largest market share in 2025, supported by the comprehensive surgical infrastructure, multidisciplinary oncology teams, and the ability to manage complex thoracic procedures requiring advanced perioperative care. A peer-reviewed analysis of SEER-Medicare data indicates that hospital-based surgical treatment remains the predominant care setting for patients with surgically resectable early-stage non-small cell lung cancer. This predominance reinforces the leading position of cancer hospitals in performing lung cancer surgeries.
The ambulatory surgical centers category will have the highest CAGR of approximately 5.2%, driven by the increasing adoption of minimally invasive thoracic procedures, advances in perioperative care, and healthcare policies supporting the transition of appropriate surgical procedures to outpatient settings. Improvements in video-assisted thoracoscopic surgery, robotic-assisted surgery, and enhanced recovery protocols are enabling select thoracic procedures to be performed safely in ambulatory settings.
Drive strategic growth with comprehensive market analysis
Lung Cancer Surgery Market Regional Outlook
North America Lung Cancer Surgery Market Size
North America holds the largest market share of 40% in 2025, owing to the increasing pace of technological advancements in the treatment of lung cancer, high incidence of the disease, widespread lung cancer screening programs, and the growing adoption of minimally invasive and robotic-assisted thoracic surgeries. Well-established thoracic surgery infrastructure and widespread adoption of minimally invasive and robotic-assisted surgical techniques support high surgical procedure volumes across the region. Favorable reimbursement policies and the presence of leading cancer centers contribute to improved patient outcomes. According to a 2024 U.S. National Health Interview Survey analysis, approximately 12.7 million adults in the United States were eligible for annual low-dose CT lung cancer screening under USPSTF guidelines, supporting early diagnosis and increasing the number of patients undergoing curative surgical resection.
Additionally, Canada is the fastest-growing country in North America, driven by expanding lung cancer screening programs, increasing adoption of minimally invasive and robotic-assisted thoracic surgeries, and continued investments in healthcare infrastructure. Growing access to specialized cancer care and early diagnosis is increasing the number of patients eligible for curative surgical procedures.
U.S. Lung Cancer Surgery Market Size
The U.S. market is the largest in the North American lung cancer surgery market, due to the high prevalence of lung tumors, advanced facilities, high awareness regarding the treatment, and high spending by the government and private sector on the advancement of the healthcare expenditure of the country. The widespread adoption of minimally invasive and robotic-assisted thoracic surgery and comprehensive lung cancer screening programs support market growth. According to the U.S. Centers for Disease Control and Prevention (CDC), the 5-year relative survival rate for lung cancer reached 28.6% for cases diagnosed during 2015–2021. This survival rate reflects improvements in early diagnosis and treatment that continue to increase the number of patients eligible for curative surgical resection.
Asia-Pacific Lung Cancer Surgery Market Size
Asia-Pacific will have the highest CAGR of approximately 5.6%, due to the rapid enhancement in the healthcare infrastructure of the region, increasing government funding and awareness-raising initiatives, and growing medical tourism industry in emerging economies, such as India and China, expanding adoption of minimally invasive and robotic-assisted thoracic surgeries, and improving access to specialized cancer hospitals and early screening programs.
Moreover, India is the fastest-growing country market, propelled by rising incidence and expanding tertiary cancer care access. Indian Council of Medical Research (ICMR), through its National Cancer Registry Programme, indicates that lung cancer incidence in India is projected to increase from 63,708 cases in 2015 to 81,219 cases in 2025, expanding the surgically eligible patient pool. The growing patient population is accelerating demand for lung cancer surgeries, advanced surgical instruments, robotic-assisted procedures, and specialized thoracic oncology services.
China Lung Cancer Surgery Market Size
China holds the largest country-level share within the Asia-Pacific lung cancer surgery market, driven by the sheer scale of its lung cancer burden, rapid expansion of tertiary cancer hospitals, and growing domestic adoption of both open and minimally invasive thoracic surgical techniques. Government-led national cancer screening initiatives have further expanded the pool of surgically eligible patients. According to the National Cancer Center (NCC) of China, lung cancer was the most commonly diagnosed cancer among men in 2022, accounting for 658,700 new cases, or 26.0% of all male cancer diagnoses, underscoring the substantial demand for surgical treatment across the country.
Europe Lung Cancer Surgery Market Size
Europe is the second-largest regional market, driven by advanced healthcare infrastructure, high adoption of minimally invasive surgeries, and favorable reimbursement policies. Germany holding the largest country-level share, supported by its advanced healthcare system, high per-capita access to thoracic oncology centers, and strong national emphasis on robotic and minimally invasive surgical adoption. France represents the fastest-growing country market within the region, driven by expanding lung cancer screening programs and rising adoption of minimally invasive thoracic procedures. According to the OECD and the European Commission's Germany Cancer Profile 2025, the number of cancer cases in Germany is projected to increase by 15% between 2022 and 2040, highlighting the growing demand for advanced oncology services, including lung cancer surgery.
The regions and countries analysed in this report are:
North America (Largest Regional Market)
U.S. (Larger Country)
Canada (Faster-Growing Country)
Europe
Germany (Largest Country)
U.K.
France (Fastest-Growing Country)
Italy
Spain
Rest of Europe
Asia-Pacific (Fastest-Growing Regional Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country)
Mexico (Fastest-Growing Country)
Rest of LATAM
Middle East & Africa
Saudi Arabia (Largest and Fastest-Growing Country)
South Africa
U.A.E.
Rest of MEA
Lung Cancer Surgery Market Competitive Landscape
The lung cancer surgery market is semi-consolidated because it is characterized by a limited number of established medical device manufacturers with strong competitive positions across robotic surgical systems, advanced visualization platforms, and thoracic surgical instruments. Regulatory approval requirements create barriers to entry for new competitors. The capital investment needed to develop and commercialize robotic-assisted technologies, together with extensive surgeon training programs, further limits the participation of new competitors. Leading companies such as Medtronic plc, Johnson & Johnson, Intuitive Surgical, Olympus Corporation, and KARL STORZ have built hospital relationships, distribution networks, and product portfolios. High switching costs associated with capital equipment investments, surgeon familiarity, and long-term clinical partnerships reinforce the competitive positions of incumbent manufacturers across the global market.
Leading Companies in the Lung Cancer Surgery Market:
Johnson & Johnson
Intuitive Surgical, Inc.
Medtronic plc
Olympus Corporation
Teleflex Incorporated
FUJIFILM Holdings Corporation
Siemens Healthineers AG
KARL STORZ SE & Co. KG
B. Braun SE
CONMED Corporation
Stryker Corporation
Richard Wolf GmbH
Lung Cancer Surgery Market News
In September 2025, Olympus Corporation launched the BF-UC190F endobronchial ultrasound (EBUS) bronchoscope across Europe, the Middle East and Africa (EMEA) and major Asia-Pacific markets, with a subsequent launch planned in Japan. The bronchoscope features 170-degree upward angulation, enabling improved access to challenging segmental and sub-segmental airways for more accurate endobronchial ultrasound-guided transbronchial needle aspiration (EBUS-TBNA) in lung cancer diagnosis and staging.
In August 2024, KARL STORZ SE & Co. KG completed the acquisition of Asensus Surgical, Inc. to establish a dedicated surgical robotics hub and accelerate the development of Performance-Guided Surgery by combining Asensus' expertise in digital surgery, artificial intelligence, and robotics with KARL STORZ's leadership in endoscopy and visualization technologies.
Frequently Asked Questions About This Report
What is driving the growth of the lung cancer surgery market?+
The market is driven by the rising incidence of lung cancer, increasing adoption of minimally invasive and robotic-assisted surgeries, expansion of lung cancer screening programs, and continuous advancements in surgical imaging and navigation technologies.
Why is robotic-assisted lung cancer surgery gaining popularity?+
Robotic-assisted surgery is gaining popularity due to its high precision, improved dexterity, enhanced visualization, smaller incisions, reduced blood loss, shorter hospital stays, and faster patient recovery compared with conventional open surgery.
Which region dominates the global lung cancer surgery market?+
North America dominates the market owing to its advanced healthcare infrastructure, high adoption of robotic surgical systems, favorable reimbursement policies, and established lung cancer screening programs.
How is minimally invasive surgery transforming the lung cancer surgery market?+
Minimally invasive techniques, including video-assisted thoracoscopic surgery (VATS) and robotic-assisted thoracic surgery (RATS), are transforming the market by reducing surgical trauma, shortening hospital stays, and improving patient recovery.
What are the major trends shaping the lung cancer surgery market?+
Key trends include increasing adoption of robotic-assisted thoracic surgery, wider use of video-assisted thoracoscopic surgery (VATS), integration of AI-enabled surgical planning and imaging, and growing implementation of enhanced recovery after surgery (ERAS) protocols.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws