This Report Provides In-Depth Analysis of the Hemato Oncology Testing Market Report Prepared by P&S Intelligence, Segmented by Offering (Services, Assay Kits and Reagents), Cancer Type (Leukemia, Lymphoma, Myeloproliferative Neoplasms), Technology (Polymerase Chain Reaction, Immunohistochemistry, Next-Generation Sequencing, Cytogenetics), End User (Clinical Laboratories, Hospitals, Academic and Research Institutes), and Geographical Outlook for the Period of 2021 to 2032
Explore the market potential with our data-driven report
Hemato Oncology Testing Market Overview
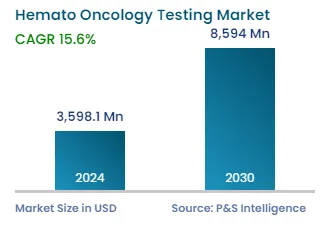
The hemato oncology testing market size was USD 4.1 billion for 2025, and it will grow by 15.7% during 2026–2032, to reach USD 11.4 billion by 2032.
This growth is driven by the rising clinical burden of hematological malignancies and the transition of hematologic diagnosis from morphology-based assessment to integrated molecular, immunophenotypic, and cytogenetic profiling. Analysis published in the Chinese Medical Journal reported 1,311,104 new cases and 700,205 deaths from hematological malignancies worldwide in 2022. The study projects new cases to increase by 69.6% by 2050, supporting the growing demand for recurrent hemato-oncology testing. Over the past few years, there have been several clinical trials for hematological malignancies, and healthcare providers increasingly utilize hemato oncology testing technologies for effective diagnosis.
Apart from the significant prevalence of hematological cancers and an increase in the count of partnerships among the players, the growing awareness regarding the availability of technologically advanced diagnostic solutions, favorable reimbursement policies, and increase in the healthcare spending all help the hemato oncology sector advance. The collaborations among various government and non-government organizations to create awareness regarding the types of malignancies and the importance of early diagnosis, along with the growing geriatric population, will further propel the growth of the market. In recent years, tremendous work has been done in the research field to understand the molecular pathogenesis behind the disease, more specifically acute myeloid leukemia, which has resulted in remarkable progress in precision medicine.
Key Market Insights
The services category holds the larger market share, of 70%, in 2025, driven by the rising incidence of leukemia, lymphoma, and multiple myeloma.
The assay kits and reagents category will have the higher CAGR, of approximately 15.9%, driven by the growing adoption of companion diagnostics and decentralized molecular testing.
The lymphoma category holds the largest market share, of 60%, in 2025, and it will have the highest CAGR, of approximately 16.0%, driven by its complex diagnostic requirements.
The hospitals category holds the largest market share, of 60%, in 2025, driven by advanced diagnostic infrastructure and specialized expertise in hematological malignancies.
Asia-Pacific will have the highest CAGR, of approximately 16.6%, driven by the rising burden of hematological malignancies, expanding precision medicine, and increasing adoption of molecular diagnostics.
Hemato Oncology Testing Market Trends & Drivers
Genomically Defined Disease Classification Is Key Trend
The classification of hematological malignancies is increasingly shifting from morphology-based diagnosis to genomically defined disease classification, driving greater adoption of molecular diagnostics in clinical practice. Advances in next-generation sequencing, cytogenetics, and biomarker testing are enabling more accurate disease classification, risk stratification, treatment selection, and measurable residual disease monitoring. According to the European Commission's SANGUINE project, hematological malignancies account for approximately 10% of the 2.7 million new cancer cases diagnosed annually in the European Union, highlighting the growing need for advanced molecular diagnostic technologies. This transition is accelerating the demand for comprehensive hemato oncology testing across hospitals, clinical laboratories, and specialized cancer centers.
Molecular genetic abnormalities are incorporated as key diagnostic criteria for several hematological malignancies, including acute myeloid leukemia, in the 5th edition of the World Health Organization Classification of Haematolymphoid Tumours, emphasizing the growing role of genomic profiling in routine clinical decision-making. As healthcare providers increasingly adopt standardized molecular testing workflows for precision medicine, demand for advanced hemato oncology testing technologies is expected to continue growing.
Population Ageing and Rising Hematologic Cancer Incidence Are Biggest Drivers
The growing geriatric population and rising incidence of hematological malignancies are major factors driving the demand for hemato oncology testing, as older adults are at a significantly higher risk of developing diseases such as leukemia, multiple myeloma, and myelodysplastic syndromes, increasing the need for early diagnosis, molecular characterization, treatment selection, and disease monitoring. For instance, according to the U.S. National Cancer Institute, the median age at diagnosis is 68 years for acute myeloid leukemia and 69 years for multiple myeloma, demonstrating the strong association between advancing age and the occurrence of hematological malignancies. In addition, improvements in patient survival are expanding the number of individuals requiring long-term follow-up, further increasing the utilization of molecular and cytogenetic testing.
According to the Global Burden of Disease Study 2023 published in The Lancet, there were 18.5 million new cancer cases and 10.4 million cancer deaths worldwide in 2023, and the study projects cancer deaths to increase by 90.6% in low- and middle-income countries by 2050, compared with 42.8% in high-income countries, highlighting the growing need for cancer diagnostics and monitoring services. As the burden of hematological malignancies continues to rise, healthcare providers are increasingly adopting advanced molecular diagnostic technologies to support accurate diagnosis, prognosis, measurable residual disease monitoring, and precision medicine, thereby driving the growth of the market.
Reimbursement Fragmentation and Specialist Workforce Scarcity Are Key Restraints
Limited reimbursement for comprehensive molecular testing and serial disease monitoring remains a significant challenge for the hemato oncology testing market. Although clinical guidelines increasingly recommend genomic profiling and measurable residual disease testing, reimbursement policies vary considerably across healthcare systems, limiting patient access to advanced molecular diagnostics and slowing their routine clinical adoption.
Another major challenge is the shortage of skilled hematopathologists, molecular pathologists, and bioinformatics professionals required to perform and interpret complex molecular and genomic tests. According to the World Health Organization, limited access to accurate diagnosis remains one of the major barriers to improving cancer outcomes, particularly in resource-constrained settings. Workforce shortages continue to delay diagnosis, limit testing capacity, and constrain the broader adoption of advanced hemato oncology testing technologies.
Measurable Residual Disease Monitoring and Underbuilt Diagnostic Capacity Are Biggest Opportunities
Measurable residual disease (MRD) monitoring is emerging as a significant growth opportunity for the hemato oncology testing market, as it transforms a single diagnostic event into a continuous disease monitoring process. Clinical guidelines for acute lymphoblastic leukemia, acute myeloid leukemia, and multiple myeloma increasingly recommend MRD assessment to evaluate treatment response, guide therapeutic decisions, and detect disease relapse. Patients require repeated molecular testing throughout diagnosis, treatment, and follow-up, creating sustained demand for advanced hemato oncology testing technologies.
Another major opportunity lies in expanding molecular diagnostic infrastructure across emerging economies. According to the World Health Organization, only 26% of low-income countries reported pathology services as generally available in the public sector, highlighting substantial gaps in access to cancer diagnostics. Expanding laboratory networks, strengthening pathology services, and increasing investments in molecular diagnostic capabilities are expected to improve access to advanced hemato oncology testing and create significant growth opportunities in underserved markets.
The services category holds the larger market share, of 70%, in 2025, because of the rising incidence of multiple myeloma, non-Hodgkin’s lymphoma, and leukemia. The complexity of diagnosing and monitoring these diseases requires advanced molecular testing, specialized laboratory infrastructure, and expert interpretation, increasing reliance on specialized reference laboratories and clinical testing service providers. In addition, the U.S. Congressional Research Service reported that, on March 31, 2025, a federal district court vacated the FDA's Laboratory Developed Test rule, reinforcing the role of specialized laboratory service providers in advanced molecular diagnostics.
The assay kits and reagents category will have the higher CAGR, of approximately 15.9%, supported by the decentralization of molecular testing into hospital laboratories and the growing adoption of companion diagnostics for precision medicine. As healthcare providers expand in-house molecular testing capabilities, demand for standardized, validated assay kits and reagents continues to increase. The U.S. Food and Drug Administration continues to expand its list of authorized companion diagnostic devices, with new approvals in 2025 for biomarker-based assays supporting targeted therapies across multiple cancers, reinforcing the increasing use of validated assay kits and reagents in routine clinical practice.
The offerings analyzed in this report are:
Services (Larger Category)
Assay Kits and Reagents (Faster-Growing Category)
Cancer Type Analysis
The lymphoma category holds the largest market share, of 60%, in 2025, and it will have the highest CAGR, driven by the heterogeneous nature of lymphoma, which requires the integration of immunohistochemistry, flow cytometry, cytogenetics, fluorescence in situ hybridization, and molecular testing for accurate disease classification, treatment selection, and disease monitoring. The increasing adoption of precision therapies, including bispecific antibodies and CAR-T cell therapies, is accelerating the demand for comprehensive molecular testing before and after treatment. In addition, Blood Cancer United estimates that 192,070 people in the U.S. will be diagnosed with leukemia, lymphoma, or myeloma in 2025, highlighting the increasing burden of hematological malignancies and the growing demand for advanced hemato oncology testing and disease monitoring.
The cancer types analyzed in this report are:
Leukemia
Acute myeloid leukemia (AML)
Acute lymphocytic leukemia (ALL)
Lymphoma (Largest and Fastest-Growing Category)
Non-Hodgkin's lymphoma
Hodgkin's lymphoma
Myeloproliferative Neoplasms
Polycythemia vera (PV)
Essential thrombocythemia (ET)
Myelofibrosis (MF)
Technology Analysis
The polymerase chain reaction category holds the largest market share, of 45%, in 2025. This can be ascribed to the advantages offered by this technology, including high accuracy, sensitivity, efficiency, rapid turnaround time, lower cost compared to next-generation sequencing, and simpler instrumentation. The increasing adoption of precision medicine and biomarker-guided therapies has accelerated the use of PCR-based testing for biomarker detection, measurable residual disease monitoring, and companion diagnostics. PCR remains a cornerstone technology for treatment selection, disease monitoring, and routine molecular testing in hematological malignancies.
The next-generation sequencing category will have the highest CAGR, driven by declining sequencing costs and the growing adoption of comprehensive genomic profiling that enables the simultaneous analysis of multiple clinically relevant genetic alterations. Supporting this adoption, the U.S. National Institutes of Health, through the National Cancer Institute, launched the myeloMATCH precision medicine umbrella trial, which uses rapid sequencing-based genomic profiling to assign patients with acute myeloid leukemia and myelodysplastic syndromes to mutation-matched treatment arms, highlighting the expanding clinical adoption of next-generation sequencing in hemato oncology.
The hospitals category holds the largest market share, in 2025, driven by the presence of trained healthcare professionals, advanced laboratory settings, the rising incidence of blood cancers, and the availability of a wide range of diagnostic tests. Supporting this, a real-world study published in Wiener klinische Wochenschrift involving 447 patients with acute myeloid leukemia at an Austrian tertiary cancer center demonstrated the routine use of comprehensive molecular diagnostics within the treating hospital, highlighting the important role of hospitals in providing advanced hemato oncology testing services.
The academic and research institutes category will have the highest CAGR, of approximately 16.1%, reflecting their role in validating assays before clinical adoption and in running biomarker-stratified clinical trials that support the development of new diagnostic technologies for hematological malignancies. Supporting this, a peer-reviewed study published in Cancers demonstrated that an academic-developed targeted next-generation sequencing panel for pediatric acute leukemia identified clinically significant genetic alterations, with 49% of detected mutations and 97% of identified gene fusions having direct clinical impact, highlighting the important contribution of academic research to the validation and advancement of hemato oncology testing.
The end users analyzed in this report are:
Clinical Laboratories
Hospitals (Largest Category)
Academic and Research Institutes (Fastest-Growing Category)
Drive strategic growth with comprehensive market analysis
Hemato Oncology Testing Market Regional Analysis
North America Hemato Oncology Testing Market Size
North America holds the largest market share, of 40%, in 2025, driven by the high prevalence of hematological malignancies, widespread adoption of advanced molecular diagnostic technologies, favorable reimbursement policies, and a well-established healthcare infrastructure. This position rests on three structural advantages, including established reimbursement pathways for molecular pathology procedure codes that make multi-gene panel testing economically viable at the hospital level, an unusually dense network of independent reference laboratories that centralize low-volume, high-complexity assays, and a regulatory environment in which FDA-cleared assays, such as clonoSEQ for measurable residual disease, have established clinical precedent for sequencing-based monitoring in leukemia and lymphoma. According to the American Cancer Society, an estimated 67,790 new cases of leukemia and 23,910 deaths from leukemia are expected to occur in the U.S. in 2026.
U.S. Hemato Oncology Testing Market Size
The U.S. represents both the largest country market within North America, driven by a concentration of NCI-designated cancer centers running protocol-driven molecular workups, early payer recognition of measurable residual disease testing, and the co-development of companion diagnostics alongside targeted hematology therapeutics. According to the American Cancer Society, an estimated 79,320 new cases and 19,970 deaths from non-Hodgkin lymphoma are expected to occur in the U.S. in 2026.
Additionally, the National Cancer Institute (NCI) Surveillance, Epidemiology, and End Results (SEER) Program estimates that 36,000 new cases of multiple myeloma will occur in the U.S. in 2026, with a five-year relative survival rate of 63.7%. Improving survival extends the surveillance window for patients, increasing the need for recurring monitoring throughout the disease course. This increased monitoring requirement continues to drive demand for hemato oncology testing.
Asia-Pacific Hemato Oncology Testing Market Size
Asia-Pacific will have the highest CAGR, of approximately 16.6%, driven by the rising burden of hematological malignancies, increasing healthcare expenditure, rapid investments in genomic and molecular diagnostic infrastructure, expanding adoption of precision medicine, and improving access to advanced diagnostic technologies. The growing use of next-generation sequencing, molecular diagnostics, and biomarker-based testing is accelerating the diagnosis and monitoring of hematological malignancies, supporting robust market growth across the region.
Japan illustrates this regional momentum. In September 2024, the country approved HemeSight, its first comprehensive genomic profiling assay for hematological malignancies. Beginning in March 2025, the assay became eligible for reimbursement under the national health insurance system, expanding access to genomic testing for leukemia, lymphoma, and multiple myeloma. This reflects the region's continued investment in precision diagnostics and advanced hemato oncology testing.
China Hemato Oncology Testing Market Size
China is the largest country market within Asia-Pacific, driven by its large patient population, expanding network of cancer centers, growing adoption of molecular diagnostics, and progressive integration of precision medicine into clinical practice. Domestic assay manufacturers continue to strengthen their presence in PCR-based testing through cost-effective solutions, while advanced next-generation sequencing services are increasingly available at leading tertiary hospitals and specialized laboratories. In addition, the National Health Commission of the People's Republic of China continues to promote standardized pathological and molecular diagnostic practices through its national guidelines for malignant lymphoma, supporting the broader adoption of precision diagnostics and strengthening demand for hemato oncology testing across the country.
India Hemato Oncology Testing Market Size
India is the fastest-growing country market within Asia-Pacific, expanding from a relatively small installed base as private diagnostic chains extend molecular testing services beyond metropolitan centers and public tertiary hospitals strengthen their cytogenetics and molecular diagnostics capabilities. Cost-sensitive procurement continues to favor PCR and immunohistochemistry, while hub-and-spoke laboratory networks are gradually improving access to centralized next-generation sequencing services.
According to the Indian Council of Medical Research, National Centre for Disease Informatics and Research, through the National Cancer Registry Programme, India's total cancer incidence is projected to increase by 12.8% by 2025 compared with 2020 levels. The programme also estimated 55,573 leukemia cases and 43,567 non-Hodgkin lymphoma cases in 2022, highlighting the growing burden of hematological malignancies and the increasing need for molecular diagnostics, disease monitoring, and precision medicine. Continued expansion of advanced diagnostic infrastructure and broader adoption of genomic testing are expected to further support the growth of the hemato oncology testing market in India.
The regions and countries analysed in this report are:
The market is fragmented, with competition among multinational in vitro diagnostics companies, molecular diagnostics specialists, sequencing technology providers, hospital laboratories, and independent clinical laboratory networks. The market spans multiple technology platforms, including polymerase chain reaction, next-generation sequencing, flow cytometry, cytogenetics, and immunohistochemistry, allowing companies to establish specialized positions across different testing modalities rather than competing across the entire value chain. While leading companies such as F. Hoffmann-La Roche Ltd., Abbott Laboratories, Thermo Fisher Scientific Inc., QIAGEN N.V., Illumina Inc., and Bio-Rad Laboratories Inc. maintain strong positions in diagnostic instruments, assay kits, reagents, and sequencing platforms, numerous regional laboratories, specialized diagnostics companies, and service providers compete in molecular testing and laboratory services. Additionally, continuous technological innovation, disease-specific expertise, regulatory requirements, strategic collaborations, and the presence of specialized players across different segments of the value chain create a competitive environment with no single company dominating the market.
Leading Companies in the Hemato Oncology Testing Market:
Abbott Laboratories
F. Hoffmann-La Roche AG
QIAGEN N.V.
Thermo Fisher Scientific Inc.
Bio-Rad Laboratories, Inc.
Illumina, Inc.
Siemens Healthineers AG
Sysmex Corporation
Danaher Corporation
Invivoscribe, Inc.
ARUP Laboratories, Inc.
NeoGenomics, Inc.
Hemato Oncology Testing Market Developments
In May 2026, Sysmex Corporation introduced the XR-Series hematology platform through Sysmex America, Inc., featuring the XR-10 Automated Hematology Module with 3D scattergram technology to enhance blood cell analysis while maintaining compatibility with existing XN-Series workflows.
In February 2026, Invivoscribe, Inc. launched the LeukoStrat KMT2A + MRD Assay and Software, a digital PCR assay supporting screening and measurable residual disease monitoring of KMT2A rearrangements in acute myeloid leukemia. The assay was introduced as a standalone kit, with laboratory testing services planned through the company's LabPMM laboratory network.
In July 2025, Bio-Rad Laboratories, Inc. completed the acquisition of digital PCR developer Stilla Technologies, strengthening its digital PCR portfolio and expanding its capabilities in high-sensitivity molecular diagnostics for applications including measurable residual disease monitoring and precision oncology.
In April 2025, NeoGenomics, Inc. completed the acquisition of Pathline, LLC, a CLIA-, CAP-, and New York State-certified laboratory in New Jersey providing histopathology, immunohistochemistry, cytogenetics, and flow cytometry services. The purchase secures New York State approvals and establishes local Northeast processing capacity in a region where the company had historically low penetration in hematology-oncology testing.
Frequently Asked Questions About This Report
How is artificial intelligence transforming hemato oncology testing?+
Artificial intelligence improves the analysis of genomic and pathology data, accelerates variant interpretation, supports clinical decision-making, and enhances the accuracy and efficiency of blood cancer diagnosis.
Why is measurable residual disease (MRD) testing becoming a standard of care?+
MRD testing enables the detection of very low levels of residual cancer cells after treatment, helping clinicians evaluate treatment response, predict relapse, and optimize personalized treatment strategies.
How are genomic biomarkers improving blood cancer diagnosis and treatment?+
Genomic biomarkers identify disease-specific mutations and chromosomal abnormalities, enabling precise disease classification, risk stratification, targeted therapy selection, and treatment monitoring.
What role does next-generation sequencing (NGS) play in hemato oncology testing?+
How are liquid biopsy technologies influencing hemato oncology testing?+
Liquid biopsy enables minimally invasive detection and monitoring of circulating tumor DNA and other biomarkers, allowing disease monitoring, relapse detection, and treatment response assessment without repeated bone marrow biopsies.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws