Fill Finish Manufacturing Market Size Estimation
Key Highlights
| Study Period | 2021 - 2032 |
| Market Size in 2025 | USD 12.2 Billion |
| Market Size in 2026 | USD 13.4 Billion |
| Market Size by 2032 | USD 25.3 Billion |
| Projected CAGR | 11% |
| Largest Region | North America |
| Fastest-Growing Region | Asia-Pacific |
| Market Structure | Fragmented |
Market Size
Explore the market potential with our data-driven report
Fill Finish Manufacturing Market Insights
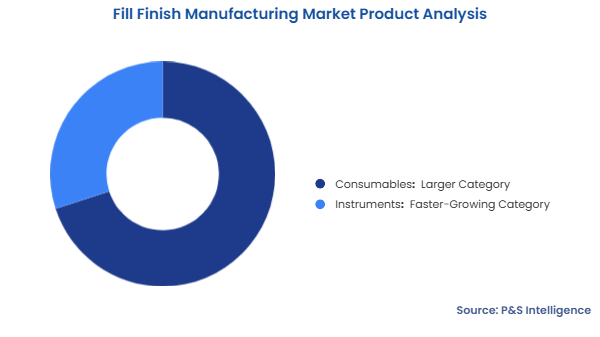
- The consumables category holds the larger market share, of 70%, in 2025, driven by the widespread adoption of single-use components and their recurring demand across manufacturing processes.
- The instruments category will have the higher CAGR, of 11.2%, driven by the adoption of automated fill finish systems and aseptic robotics.
- The contract manufacturing organizations category holds the largest market share, of 75%, in 2025, and it will have the highest CAGR, of 11.3%, driven by increasing outsourcing of fill finish operations.
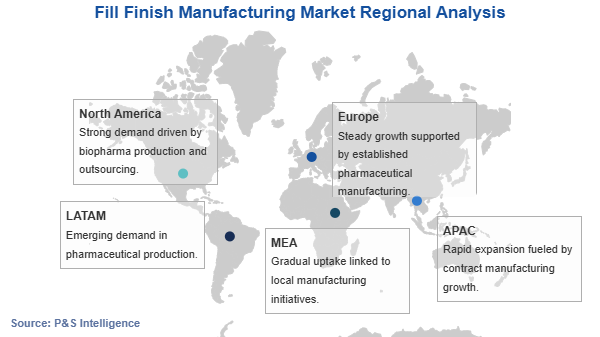
- North America holds the largest market share, of 40%, in 2025, supported by its strong biopharmaceutical base and injectable drug adoption.
- Asia-Pacific will have the highest CAGR, of 11.1%, driven by the rapid expansion of biopharmaceutical manufacturing across the region.
Fill Finish Manufacturing Market Analysis
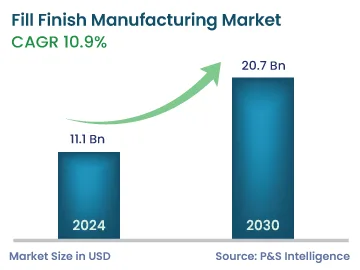
The fill finish manufacturing market size was USD 12.2 billion for 2025, and it will grow by 11.0% during 2026–2032, to reach USD 25.3 billion by 2032.
This process plays an important role in the pharmaceutical and biotechnology industries by being the last stage in the production procedure, wherein synthetic and biologic drugs are poured into their respective containers and packaged for distribution. Moreover, the market is propelled by the growing incidence of chronic diseases, such as cancer, diabetes, and autoimmune disorders. These conditions often require the effective administration of injectable medicines, thus creating the need for efficient fill finish processes. According to the World Health Organization, chronic diseases account for approximately 74% of all global deaths annually, highlighting the increasing long-term demand for injectable therapeutics and related manufacturing processes.
Furthermore, technological advancements have played a vital role in shaping the success of the market players. Automation and robotics have advanced production efficiency, accuracy, and sterility, thus reducing the risk of infection and human errors during the fill finish process. The regulatory landscape also impacts the market due to the stringent guidelines and high-quality requirements set by governments to make sure drug products are safe and effective.
Fill Finish Manufacturing Market Trends & Drivers
Automation and Innovation in Fill Finish Operations Are Key Trends
The advancements in technology have revolutionized fill finish processes, especially in terms of efficiency, accuracy, and quality. Automated systems have the ability to handle higher production volumes with precision and speed, thus minimizing human mistakes and augmenting productivity. Robots are used for vial filling, stoppering, capping, and labeling, thereby ensuring consistent operations. Moreover, regulatory authorities such as the U.S. Food and Drug Administration and the European Medicines Agency have increasingly emphasized the adoption of advanced aseptic processing technologies and automation to enhance sterility assurance and reduce contamination risks in pharmaceutical manufacturing.
Moreover, single-use systems have received traction in the fill finish manufacturing market due to their several benefits. These systems include disposable components, such as bags, tubing, filters, and connectors. Such disposable consumables eliminate the need for extensive cleaning and sterilization procedures, thus decreasing the threat of cross-contamination. They, additionally, provide increased flexibility in manufacturing, as they allow for rapid changeovers between different drug products. Government-backed initiatives, such as those supported by the Biomedical Advanced Research and Development Authority, are accelerating the adoption of flexible manufacturing approaches, including single-use systems and advanced aseptic technologies across biologics and vaccine production. Advanced aseptic technologies, including isolators and restricted-access barrier systems (RABS), create controlled surroundings that prevent infection. Aseptic processing techniques also contribute to improving product stability and shelf life, which is essential for injectable drugs, especially biologics. In addition, regulations such as EU GMP Annex 1 are enforcing stricter contamination control requirements, encouraging the adoption of advanced aseptic and automated fill finish systems globally.
Increasing Demand for Injectable Drugs Is Biggest Driver
The fill finish manufacturing market is strongly driven by the increasing demand for injectable drugs. They are used for the prevention, treatment, and management of a variety of diseases, including cancers, diabetes, autoimmune issues, and infections. Such diseases require long-term treatment, often involving the regular administration of injectable medicines. As the occurrence of these diseases continues to rise, the demand for parenteral drugs will also increase. According to the International Diabetes Federation, approximately 589 million adults globally are living with diabetes, with insulin and GLP-1 therapies widely administered through injections. The growing adoption of biologics and personalized therapies, many of which require parenteral administration, is further strengthening the demand for fill finish services.
Moreover, the aging population is a major contributing factor to the rising demand for injectables. As human beings age, they are more likely to fall prey to chronic diseases. Additionally, older individuals often have difficulty swallowing drugs or possess reduced gastrointestinal absorption capabilities, which makes injectable medicines popular. According to the United Nations, the global population aged 65 years and above is expected to exceed 1.6 billion in the coming decades, significantly increasing the demand for chronic disease treatments, including injectables.
Personalized drug development involves tailoring treatments to patients, based on their genetic makeup and lifestyle. Many personalized remedies, such as targeted treatments for cancer, require administration via injection. For instance, Merck & Co. has introduced a subcutaneous injectable version of its cancer immunotherapy drug Keytruda, enabling administration in a few minutes compared to traditional intravenous infusion, thereby improving patient convenience and supporting the shift toward injectable therapies. The shift toward personalized medicine, thus, drives the demand for injectable medications and, in turn, for fill finish services.
Expansion of Vaccine and Biologics Manufacturing Capacity Is Key Opportunity
The increasing global focus on strengthening vaccine and biologics manufacturing capacity presents a major opportunity for the fill finish manufacturing market. Governments and international organizations are actively investing in regional production capabilities to improve supply chain resilience and reduce dependency on imports. In regions such as Africa, studies indicate that out of 11 vaccine manufacturers in Africa, 10 have operational formulation and fill finish capabilities, highlighting fill finish as a key entry point for localized pharmaceutical production.
Large-scale investments and company-led developments are further accelerating this opportunity. For instance, Moderna has announced an investment of over USD 140 million to expand its manufacturing network by integrating fill finish capabilities into its mRNA production facilities. This integration enables end-to-end domestic production. Such developments reflect a broader global shift toward localized and integrated pharmaceutical manufacturing.
High Capital Investment and Skilled Workforce Shortage Are Key Restraints
High capital investment requirements for establishing and maintaining aseptic production facilities are a primary restraint on the fill finish manufacturing market. Advanced fill finish lines, including isolators, automated systems, and sterile environments, require substantial upfront costs. According to the International Society for Pharmaceutical Engineering, aseptic manufacturing facilities require extensive cleanroom infrastructure and highly specialized equipment, which raises capital expenditure and operational complexity.
Market expansion is constrained in developing regions, where financial and technical resources remain limited. The shortage of skilled professionals capable of handling complex aseptic processes is a second major restraint. Fill finish operations demand personnel trained in sterile handling and validation, as well as quality assurance. A growing global talent gap in biopharmaceutical manufacturing is reinforcing this restraint. According to the Biotechnology Innovation Organization, the biopharmaceutical industry is facing a workforce gap, with demand for skilled talent outpacing supply in aseptic manufacturing and biologics production. This shortage impacts operational efficiency, increases labor costs, and slows down the scaling of fill finish capabilities worldwide.
Fill Finish Manufacturing Market Segmentation and Category Analysis
Product Analysis
The consumables category holds the larger market share, of 70%, in 2025, driven by the widespread adoption of single-use components and their recurring demand across manufacturing processes. This category is further supported by the increasing need to reduce the risk of cross-contamination and enable faster changeovers between different drug products, thereby strengthening overall demand. According to the World Health Organization, over 16 billion injections are administered globally each year, reinforcing strong demand for consumables.
The instruments category will have the higher CAGR, of 11.2%, driven by the growing adoption of automated fill finish systems and advanced aseptic robotics, as these technologies support advanced aseptic manufacturing capabilities across fill finish lines. Continuous investments in upgrading fill finish lines with high-speed and precision-based equipment are further accelerating segment growth. According to the International Society for Pharmaceutical Engineering, the adoption of automated and closed aseptic systems is increasing across global manufacturing facilities.
The products analyzed in this report are:
- Consumables (Larger Category)
- Instruments (Faster-Growing Category)
End User Analysis
The contract manufacturing organizations category holds the largest market share, of 75%, in 2025, and it will have the highest CAGR, of 11.3%, driven by the increasing outsourcing of fill finish operations by pharmaceutical and biopharmaceutical companies to reduce capital investment and improve operational efficiency. Growing demand for biologics and injectable therapies, along with the need for flexible and scalable manufacturing solutions, is further accelerating the expansion of CDMOs globally.
The end users analyzed in this report are:
- Contract Manufacturing Organizations (Larger & Faster-Growing Category)
- Pharmaceutical and Biopharmaceutical Companies
Drive strategic growth with comprehensive market analysis
Fill Finish Manufacturing Market Regional Outlook
North America Fill Finish Manufacturing Market Size
North America holds the largest market share, of 40%, in 2025, due to its strong biopharmaceutical production base, advanced aseptic processing capabilities, and high adoption of injectable drug therapies. A well-established network of pharmaceutical companies and CDMOs operates across the region. Growing focus on supply chain localization and reducing dependence on overseas production has accelerated fill finish facility development across the United States and Canada. Advanced technologies and a skilled workforce further strengthen the region's market leadership.
Government initiatives and large-scale investments aimed at strengthening domestic biomanufacturing are reinforcing this dominance, with programs supported by the Biomedical Advanced Research and Development Authority allocating over USD 2 billion to expand biopharmaceutical manufacturing capacity, including fill finish capabilities. The Government of Canada has committed over USD 1.2 billion to strengthen its healthcare system and infrastructure, which indirectly supports the broader biopharmaceutical manufacturing ecosystem. Eli Lilly and Company has announced multiple large-scale investments. These include a USD 6 billion manufacturing facility in the U.S. focused on injectable therapies. These combined efforts are cementing North America's leadership in the global fill finish manufacturing market.
Asia-Pacific Fill Finish Manufacturing Market Size
Asia-Pacific will have the highest CAGR, of 11.1%, driven by the rapid expansion of biopharmaceutical manufacturing across the region. Rising investment in biologics and vaccine production is further strengthening regional growth. Government support for infrastructure development is accelerating the region's emergence as a key hub for injectable drug manufacturing. Lower operational costs and a skilled workforce underpin the region's cost competitiveness. An increasing focus on supply chain diversification is further accelerating regional growth.
Country-level initiatives and investments across major Asia-Pacific economies are reinforcing this growth. In Japan and Australia, the Supply Chain Resilience Initiative is enabling supply chain diversification and regional manufacturing collaboration for pharmaceuticals. China is contributing to regional growth through government support under the Made in China 2025 strategy. This initiative prioritizes the development of high-end biopharmaceutical manufacturing, including biologics and advanced drug production infrastructure. South Korea is rapidly expanding its biomanufacturing capacity. Samsung Biologics and Lotte Biologics are investing heavily in large-scale biologics production facilities. South Korea's government has launched national strategies such as the Presidential Bio Committee to strengthen the biotechnology sector.
India Fill Finish Manufacturing Market Size
India is one of the fastest-growing countries in the Asia-Pacific fill finish manufacturing market, driven by the rapid expansion of its biopharmaceutical sector. Growing capabilities in biologics and vaccine production are accelerating fill finish infrastructure development.
Government-backed initiatives promoting biotech hubs and biomanufacturing parks are strengthening domestic production capabilities and infrastructure. Programs led by the Department of Biotechnology, including Biotech Parks and Biotechnology Incubators, support infrastructure development for biologics and vaccine manufacturing. The Production Linked Incentive (PLI) Scheme for Pharmaceuticals, launched by the Government of India, provides financial incentives to boost domestic manufacturing of critical drugs and biologics. The National Biopharma Mission, with an outlay of approximately INR 1,500 crore, supports innovation and capacity building across advanced biopharmaceutical manufacturing technologies.
The regions and countries of the market are as follows:
- North America (Largest Regional Market)
- U.S. (Larger Country Market)
- Canada (Faster-Growing Market)
- Europe
- Germany (Largest Country Market)
- U.K.
- France (Fastest-Growing Country Market)
- Italy
- Spain
- Rest of Europe
- Asia-Pacific (Fastest-Growing Regional Market)
- China (Largest Country Market)
- India (Fastest-Growing Country Market)
- Japan
- South Korea
- Australia
- Rest of APAC
- Latin America
- Brazil (Largest Country Market)
- Mexico (Fastest-Growing Country Market)
- Rest of LATAM
- Middle East and Africa
- Saudi Arabia (Largest Country Market)
- South Africa
- U.A.E. (Fastest-Growing Country Market)
- Rest of MEA
Fill Finish Manufacturing Market Share Analysis
The market is fragmented, with the presence of numerous global CDMOs competing alongside pharmaceutical companies and regional specialists across drug formats including vials, syringes, and biologics. The increasing trend of outsourcing has enabled multiple players to expand across the Asia-Pacific and Europe. The market also exhibits characteristics of partial consolidation. A few large players hold substantial shares, and their manufacturing infrastructure and regulatory expertise span multiple global markets. This reach gives them a structural competitive advantage. This balance between widespread participation and the influence of key players reflects a market that is fragmented overall but still shows elements of concentration.
Leading Companies in the Fill Finish Manufacturing Market:
- Catalent Inc.
- Vetter Pharma International GmbH
- Lonza Group
- Thermo Fisher Scientific
- WuXi Biologics
- Samsung Biologics
- Baxter BioPharma Solutions
- Recipharm AB
- Piramal Pharma Solutions
- Ajinomoto Bio-Pharma Services
- Fujifilm Diosynth Biotechnologies
- PCI Pharma Services
Fill Finish Manufacturing Market News
- In October 2025, Lonza Group signed a long-term commercial supply agreement for its U.S. Vacaville facility. This agreement expands its biologics manufacturing and drug product (fill finish) services to support growing client demand.
- In June 2024, Vetter Pharma International GmbH announced the expansion of its aseptic filling capacity in Germany. The expansion incorporates advanced syringe filling technologies to support high-value biologics and complex injectable drugs.
- In June 2023, Lonza Group and Vertex Pharmaceuticals entered into a collaboration agreement to support the manufacturing of advanced biologics and cell-based therapies, covering drug product and fill finish services and strengthening Lonza's integrated CDMO capabilities.
- In June 2023, Samsung Biologics and Pfizer expanded their manufacturing collaboration agreement to encompass drug substance and drug product (fill finish) services, supporting Pfizer's biologics pipeline.