This Report Provides In-Depth Analysis of the Cloud-Native Application Protection Platform Market Report Prepared by P&S Intelligence, Segmented by Offering (Platforms, Professional Services), Cloud Type (Public, Private), Vertical (Retail & E-commerce, BFSI, IT & Telecommunications, Healthcare & Life Sciences, Energy & Utilities), Enterprise Size (Large Enterprises, SMEs), and Geographical Outlook for the Period of 2019 to 2032
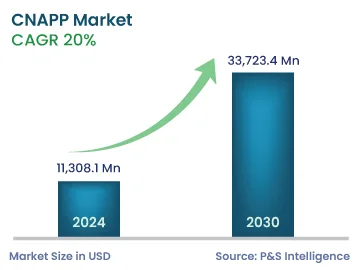
The cloud-native application protection platform market size is an estimated USD 15.0 billion for 2025, and it will grow by 19.2% during 2026–2032, to reach USD 51.2 billion by 2032.
The market growth is attributed to the increasing usage of cloud-based servers and the rising number of cyberattacks across industries, which have influenced organizations to take proactive measures and provide protection to their data and infrastructure in public, private, and hybrid cloud environments.
CNAPP is a developing cloud security platform that streamlines cloud security by integrating the capabilities of tools, such as cloud security posture management (CSPM), cloud service network security (CSNS), and cloud workload protection platform (CWPP), in a single holistic platform. These platforms allow enterprises leveraging multi-cloud to subscribe to third-party security vendors, which would provide a consolidated view into cloud environments.
Additionally, the shift toward the microservice architecture and containerization has fundamentally transformed how organizations develop and deploy applications, creating complex security requirements that traditional perimeter-based approaches cannot adequately address. CNAPP solutions have emerged as the strategic response to these challenges, providing unified security visibility and protection across hybrid and multi-cloud environments while enabling organizations to maintain the agility and innovation benefits of cloud-native development practices.
Shift-Left Security Practices and DevSecOps Integration Are Key Trends
The integration of security practices early in the software development lifecycle, commonly known as shift-left security, has become a fundamental trend driving CNAPP adoption.
DevSecOps is the practice of integrating security testing at every stage of the software development process, representing a significant evolution from traditional approaches where security was addressed only after development completion.
Organizations are recognizing that security testing tends to occur after the software is built, and any issues, particularly with security testing, may slow down or even halt development.
The implementation of shift-left practices has evolved beyond simple vulnerability scanning.
DevSecOps is not just about when security happens; it is about who owns it, how it is automated, and how it is embedded across the entire software supply chain.
This comprehensive approach includes multi-factor authentication, 2FA, or third-factor authentication, which are essential to achieving Zero Trust, with these controls providing additional verification layers for users both inside and outside the enterprise.
AI/ML integration is increasingly being adopted in DevSecOps pipelines to automate threat detection, vulnerability prioritization, and remediation, reducing manual workload and improving speed.
Infrastructure as code security is becoming an essential part of shift-left practices, as misconfigurations in IaC templates can expose cloud-native environments to risks before deployment.
Rising Sophistication of Cloud-Native Security Threats Is Biggest Driver
The key driver for the cloud-native application protection platform market is the exponential increase in sophisticated cyber-attacks specifically targeting cloud environments.
According to reports, 83% of the organizations dealt with at least one cloud security incident in 2024, and companies faced an average of 2,300 cyberattacks every week.
The complexity of these attacks has evolved significantly, with phishing being the most prevalent cloud security breach, affecting 73% of the organizations.
Additionally, access-related vulnerabilities are behind 83% of the cloud security breaches, with the top industries affected being media, healthcare, and utilities.
Organizations face not only direct financial losses but also operational disruption.
Firms lose an average of USD 6.2 million each year due to compromised cloud accounts—about 3.5% of their revenues—and enduring around 138 hours of application downtime annually.
Additionally, the rise of multi-cloud and hybrid environments, regulatory compliance pressures, for instance, GDPR, HIPAA, and human error leading to misconfigurations, further accelerate CNAPP adoption.
Organizations seek centralized visibility, automated remediation, and advanced threat detection capabilities to secure their cloud environments.
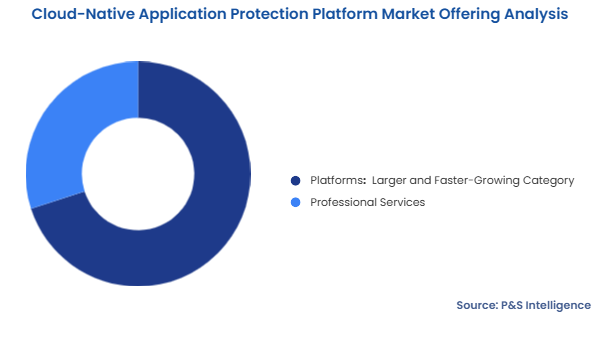
The platforms category holds the larger market share, of around 70%, in 2025, and it will have the higher CAGR. This is ascribed to the surging demand for all-in-one native systems working across applications to simplify monitoring, detecting, and acting for cloud environments and workloads; accelerate threat hunting; and check for vulnerabilities. Applications for reducing mean time to respond, helping development, security, and operation (DevSecOp) teams, addressing runtime threats, escalating major safety issues, and enabling threat hunting further help in propagating the demand for CNAPP.
Moreover, the platform provides a simplified protection and compliance tool, to reduce misconfigurations, mismanagement, and vulnerabilities of cloud-native applications. It can provide a bi-directional link and operation visibility and insight into risk analysis to improve the overall enterprise security posture. The NAPP allows the requisite department to understand paths based on relationships concerning dangers, vulnerabilities, and misconfigurations, which would enable an attacker to target an application. It also helps reduce the number of vendors and tools involved in the continuous integration and continuous deployment (Cl/CD) pipeline.
The offerings analyzed in this report are:
Platforms (Larger and Faster-Growing Category)
Professional Services
Cloud Type Analysis
The public category holds the larger market share in 2025, and it will have the higher CAGR, because of its low cost, as there is no requirement for the purchase of any hardware or software. The software, servers, hardware, and other related infrastructure are owned by third-party providers and managed by the requisite authority. Also, the public cloud deployment service is mostly being used for online offices, web-based email, applications, storage, and testing and development environments.
Moreover, the pay-as-you-go model is followed, in which users pay only for the services used, and service providers are required to provide service maintenance and help users save time and cost. The model enables enterprises to scale as per the business need, thus organizations can leverage this application to enhance their capabilities. Also, the service is highly reliable as the availability of multiple servers ensures privacy and security and safeguards against failure. Further, companies can use automated backing up data and applications while regulatory requirements are in check. Thus, these factors are driving the market growth in this category.
The cloud types analyzed in this report are:
Public (Larger and Faster-Growing Category)
Private
Vertical Analysis
The BFSI category holds the largest market share, in 2025, because cloud computing and its native architecture and models infuse BFSI business agility. Moreover, cloud computing provides a competitive edge, facilitates innovation, and reduces costs for enterprises, and it is a critical element of the digital revolution, transforming the BFSI industry. In addition, the ease of adopting open banking, the ability to provide personalized products, and leveraging of cloud cognitive services make it the stellar choice for replacing various independent tools with a single holistic security solution. The automated disaster recovery capability will further drive the demand for the technology in the industry.
The BFSI industry faces multiple safety concerns with regard to country-specific regulations, legacy architecture, and complex transitions for enterprises moving from on-premise to adopting cloud migration technologies. Also, financial institutions are focused on improving the scalability and quick provisioning of their operations. Furthermore, the deployment of CNAPP provides increased flexibility in the industry.
The financial institutions need to be compliant with several data protection laws and regulations, such as the Payment Card Industry Data Security Standard and The Personal Information Protection and Electronic Documents Act, to operate efficiently in their respective areas and get benefits of the system in saving infrastructure and license costs. Thus, these factors are expected to proliferate the adoption of CNAPP in the BFSI sector.
The IT and telecommunications category will have the highest CAGR, because it rapidly adopts cloud-native architectures to support digital transformation, 5G networks, and large-scale data operations. The increasing frequency and severity of cyber threats, stringent compliance requirements, and the need for robust cloud security across complex IT infrastructures are driving enterprises to implement CNAPP solutions faster than other industries.
The verticals analyzed in this report are:
Retail & E-commerce
BFSI (Largest Category)
IT & Telecommunications (Fastest-Growing Category)
Healthcare & Life Sciences
Energy & Utilities
Others
Enterprise Size Analysis
The large enterprises category holds the larger market share, of about 65%, in 2025, due to their substantial IT budgets, complex multi-cloud environments, and comprehensive security requirements. Large enterprises are adopting CNAPP platforms and professional services to address growing cyber threats and must comply with multiple regulatory frameworks across different jurisdictions. These organizations typically operate extensive cloud infrastructures with thousands of workloads, requiring sophisticated security solutions capable of providing centralized visibility and control.
The SMEs market category will have the higher CAGR, of 19.7%, driven by the democratization of cloud technologies and the increasing availability of cost-effective, SaaS-based CNAPP solutions. Small and medium enterprises are rapidly adopting cloud-native development practices to compete with larger organizations, but often lack the internal security expertise to protect these environments effectively. This creates substantial demand for user-friendly CNAPP platforms that offer automated security capabilities and managed services tailored to resource-constrained organizations.
The enterprise sizes analyzed in this report are:
Large Enterprises (Larger Category)
SMEs (Faster-Growing Category)
Drive strategic growth with comprehensive market analysis
Cloud-Native Application Protection Platform Market Regional Outlook
North America CNAPP Market Size
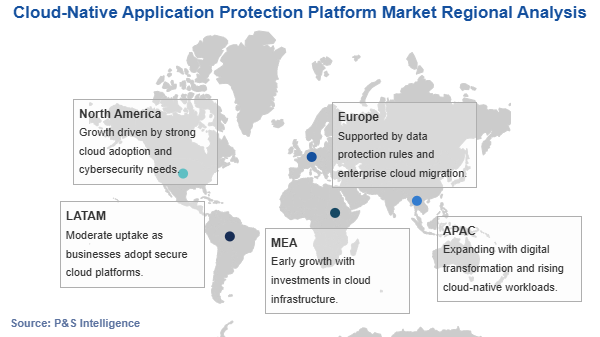
North America holds the largest market share, of about 40%, in 2025. This is primarily attributed to the region's mature cloud infrastructure, early adoption of cloud-native technologies, and the presence of major cloud service providers and CNAPP vendors. North America is expected to be the largest contributor to the global CNAPP market in terms of market share.
The region's lead is further reinforced by the increasing frequency and sophistication of cyberattacks targeting cloud environments. According to the Internet Crime Report 2024 by the FBI, IC3 continued to receive a record number of complaints from the American public; 859,532 complaints were reported during the year, which was a 33% increase from 2023, with potential losses exceeding USD 16.6 billion. Cryptocurrency-related scams accounted for over USD 6.5 billion in losses, and ransomware incidents saw a 9% rise compared to the previous year. This escalating threat landscape drives substantial investments in advanced cloud security solutions.
U.S. CNAPP Market Size
Within North America, the U.S. represents the dominant market. The country's emphasis on technological innovation and digital transformation across sectors such as finance, healthcare, and retail drives widespread CNAPP adoption. Federal initiatives promoting zero-trust architecture and stringent compliance requirements further accelerate market growth.
Asia-Pacific CNAPP Market Size
Asia-Pacific will have the highest CAGR, because the region is the global technology hub that has given rise to a new ecosystem, creating a conducive environment for tech innovations to flourish and permeate across industries. Some other major factors fueling the market growth include the surging investments by companies in artificial intelligence, cloud computing, and big data. The rapid digital transformation initiatives, increasing cloud adoption among enterprises, and growing awareness of cloud security threats, further contribute to the growth in this region.
Around 80% of IT professionals surveyed have deployed Kubernetes in production, with an additional 13% currently testing the platform, highlighting the region's accelerated adoption of cloud-native technologies. India, Singapore, and Australia are implementing national cloud strategies that emphasize security as a fundamental requirement. Additionally, the proliferation of e-commerce, fintech, and digital services in emerging markets creates substantial demand for robust cloud security solutions to protect sensitive customer data and financial transactions.
China CNAPP Market Size
China represents the largest country market within Asia-Pacific, driven by massive investments in cloud infrastructure and the presence of major domestic cloud providers. However, Japan has significant growth within the region, with enterprises rapidly modernizing legacy systems and adopting cloud-native architectures to improve competitiveness.
The geographical breakdown of the market is as follows:
North America (Largest Regional Market)
U.S. (Larger and Faster-Growing Country)
Canada
Europe
Germany (Largest and Fastest-Growing Country)
U.K.
France
Italy
Russia
Rest of Europe
Asia-Pacific (Fastest-Growing Regional Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest and Fastest-Growing Country)
Mexico
Rest of LATAM
Middle East and Africa
Saudi Arabia (Largest and Fastest-Growing Country)
The market is fragmented because it consists of many vendors, including both established cybersecurity companies and newer niche players, offering overlapping solutions such as workload protection, container security, and API protection. No single vendor dominates the market, and enterprises often use multiple tools to cover all needs. While acquisitions and partnerships are driving some consolidation, the market remains diverse and competitive, keeping it largely fragmented.
In June 2025, Fortinet Inc. enhanced its Lacework FortiCNAPP platform, strengthening code-to-cloud security for applications and workloads across hybrid and multi-cloud environments and expanding solution availability in AWS Marketplace.
In February 2025, Palo Alto Networks Inc. launched Cortex Cloud, the next version of Prisma Cloud, unifying cloud detection and response with CNAPP capabilities and AI-driven innovations for real-time threat prevention.
In February 2025, Check Point Software Technologies Ltd. entered into a strategic partnership with Wiz, integrating Wiz’s leading CNAPP technology with Check Point’s cloud network security expertise.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws