This Report Provides In-Depth Analysis of the Clinical Trial Supplies Market Report Prepared by P&S Intelligence, Segmented by Phase (Phase 1, Phase 2, Phase 3, Phase 4), Therapeutic Application (Oncology, CNS Diseases, Mental Disorders, Cardiovascular Diseases, Infectious Diseases, Metabolic Diseases, Immunology, Dermatology, Repiratory Diseases), Service (Logistics & Services, Storage & Retention, Packaging, Labeling, & Binding, Manufacturing, Comparator Sourcing), End User (Pharma & Biotech Companies, Contract Research Organizations, Medical Device Companies), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Clinical Trial Supplies Market Future Outlook
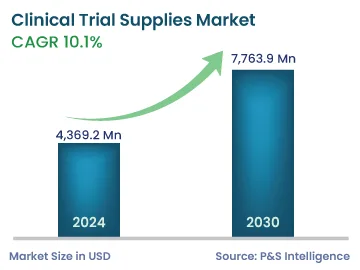
The clinical trial supplies market size was USD 4,369.2 million in 2024, and it will grow by 9.7% during 2025–2032, to reach USD 9,062.6 million by 2032.
The market encompasses essential services and materials required for conducting clinical trials, including drug manufacturing, packaging, labeling, storage, distribution, and comparator sourcing. The robust growth trajectory reflects the expanding pharmaceutical pipeline, increasing complexity of clinical trial designs, and rising emphasis on patient-centric trial approaches. ClinicalTrials.gov lists 551,947 studies across all 51 U.S. states and 224 countries and territories in 2024, receiving about 90,000 daily visitors and over 2 million unique visitors monthly. This proliferation of clinical research activities directly translates into heightened demand for specialized supplies and logistics services.
The key factors driving the growth of the market are the increasing demand for more-advanced treatments, such as personalized medicines; increasing R&D expenditure of biopharmaceutical and pharmaceutical companies, and rising prevalence of diseases, which essentially leads to the development of new drugs.
The essential aspects and significant parts of the overall expenses for biotechnology and pharma companies are research and development. These activities allow for the development of new molecules with a significant medical and commercial potential for various therapeutic applications. The investment in R&D differs as per their requirement and the nature of the drug under discovery, which is itself a time-consuming process.
Moreover, the presence of a large number of clinical trial supplies manufacturing companies with extensive product offerings helps pharmaceutical and biotechnology companies in completing their clinical trials efficiently. This shows that the outsourcing of clinical trials to contract research organizations is increasing, which has also increased the demand for various supplies.
Clinical Trial Supplies Market Trends & Drivers
Regulatory Compliance Requirements Are Key Trend
Stringent regulatory requirements governing clinical trial conduct continue to evolve, driving innovation in clinical trial supplies services.
Global regulatory authorities have strengthened their requirements for drug accountability, chain-of-custody tracking, and temperature control documentation.
The European Medicines Agency's Annex 13 guidelines and the FDA's regulations on good manufacturing practices for investigational drugs mandate comprehensive quality systems throughout the supply chain.
These requirements have prompted clinical trial supplies providers to develop advanced quality management systems, automated documentation processes, and enhanced traceability solutions.
The implementation of serialization and track-and-trace requirements adds another layer of complexity to clinical trial supplies management.
While primarily focused on commercial drugs, these regulations increasingly influence clinical trial operations as companies prepare for eventual commercialization.
The Drug Supply Chain Security Act in the U.S. requires electronic tracking of prescription drugs through the supply chain by 2025.
Clinical trial supplies providers have invested in serialization capabilities, blockchain-based verification systems, and integrated data platforms to ensure compliance while maintaining operational efficiency.
Rising Complexity of Clinical Trial Designs Is Biggest Driver
The increasing sophistication of clinical trial protocols represents a primary driver for the clinical trial supplies market.
Modern trials frequently incorporate adaptive designs, personalized medicine approaches, and biomarker-driven patient stratification, necessitating more complex supply chain management.
According to the Tufts Center for the Study of Drug Development, the average number of procedures per clinical trial protocol has increased by 70% over the past decade, while the number of eligibility criteria has grown by 60%.
This complexity translates into greater demand for specialized packaging solutions, sophisticated inventory management systems, and flexible distribution networks capable of accommodating protocol amendments.
The shift toward precision medicine has particularly intensified supply chain requirements.
Cell and gene therapy trials demand ultra-cold storage and transport, with some products needing cryogenic conditions below −150°C.
Clinical trial supplies providers have responded by investing in specialized cryogenic logistics infrastructure and developing innovative packaging solutions that maintain product integrity during extended transit times.
The phase 3 category held the largest market share, of about 55%, in 2024. This is mainly due to the higher expenses associated with this trial phase. Phase Ill requires a larger patient population compared to phase l and phase 2, which is one of the major reasons for the high cost of phase 3 trials. The average Phase 3 trial enrolls approximately 1,000-3,000 patients and lasts 1-4 years, necessitating complex supply chain orchestration to maintain drug availability while minimizing waste. The segment's dominance reflects the critical nature of Phase 3 trials in demonstrating efficacy and safety for regulatory approval, prompting sponsors to invest heavily in reliable supply chain partners.
The phase 1 category will have the highest CAGR, due to the growing R&D pipelines of pharmaceutical companies, which leads to a rise in the count of trials in the first phase. The proliferation of first-in-human studies for innovative modalities including cell therapies, gene therapies, and targeted biologics, has intensified demand for specialized handling capabilities. According to PhRMA, biopharmaceutical companies have more than 9,000 medicines in development globally, with over 70% being first-in-class compounds requiring Phase 1 evaluation. The segment's growth is further fueled by the rise of specialized Phase 1 units and early-phase clinical research organizations requiring dedicated supply chain support.
The phases analyzed in this report are:
Phase 1 (Fastest-Growing Category)
Phase 2
Phase 3 (Largest Category)
Phase 4
Therapeutic Application Analysis
The oncology category held the largest market share, of about 35%, in 2024, due to a large number of cancer drugs in the R&D pipeline, itself owing to the increasing prevalence of different types of cancer. Over 10 million people die from cancer annually, and changing lifestyles are making patient outcomes increasingly complex. This is driving the usage of enhanced technologies and data-driven approaches in oncology drug R&D. The category’s lead is reinforced by the growing focus on precision oncology, which requires specialized logistics for companion diagnostics, tissue samples, and personalized therapies.
The cardiovascular diseases category will have the highest CAGR. The rising prevalence of cardiovascular diseases across the world significantly increases the demand for therapeutics, thus resulting in the growth of the market in the cardiovascular category. Heart diseases remain the world’s biggest killer, taking almost 18 million lives a year. Key risk factors are hypertension, diabetes, smoking, high cholesterol, obesity, and sedentary lifestyle.
Older adults, men, and individuals with a family history are at higher risk, along with low-income and ethnic minority populations due to healthcare disparities. Heart disease imposes a heavy economic burden, costing the U.S. alone over USD 240 billion annually. Prevention through lifestyle changes and early intervention is critical to reducing global cardiovascular morbidity and mortality.
The therapeutic applications analyzed in this report are:
The logistics & services category held the largest market share in 2024, as efficient transportation and distribution form the backbone of clinical trial supply chains. This segment encompasses temperature-controlled shipping, last-mile delivery to trial sites, and reverse logistics for unused supplies. The complexity of managing just-in-time deliveries across global trial networks while maintaining product integrity drives continuous demand for sophisticated logistics solutions.
The manufacturing category will have the highest CAGR, propelled by the trend toward outsourcing investigational drug manufacturing to specialized providers. The increasing complexity of drug formulations, particularly for biologics and advanced therapies, requires specialized manufacturing capabilities that many sponsors prefer to access through external partners. The growth reflects sponsors' strategic focus on core competencies while leveraging external expertise for GMP-compliant manufacturing of clinical supplies.
The services analyzed in this report are:
Logistics & Services (Largest Category)
Storage & Retention
Packaging, Labeling, & Binding
Manufacturing (Fastest-Growing Category)
Comparator Sourcing
End User Analysis
The pharma & biotech companies category held the largest market share, of about 55%, in 2024, because of the increasing occurrence of chronic diseases, which has led to the growth of pharmaceutical R&D pipelines. Nearly 50,000 pharma & biotech companies are present across the globe, and all of them are engaged in developing therapeutic agents, which is increasing the number of clinical trials.
The contract research organizations category will have the highest CAGR, driven by the continued outsourcing of clinical trial management by sponsors. CROs increasingly assume responsibility for end-to-end trial execution, including supply chain management, creating substantial demand for clinical trial supplies services. Studies say that CRO service providers will make USD 179.2 billion by 2032.
The end users analyzed in this report are:
Pharma & Biotech Companies (Largest Category)
Contract Research Organizations (Fastest-Growing Category)
Medical Device Companies
Drive strategic growth with comprehensive market analysis
North America held the largest market share in 2024, driven by a growing number of clinical trials with the strengthening focus on the development of better and safer medicines. The increasing prevalence of all kinds of diseases, growing number of pharma and biotechnology companies, and favorable government legislations for pharma R&D essentially lead to the rise in the demand for the various supplies required during the clinical studies of investigational drugs. The presence of major pharmaceutical companies, leading academic medical centers, and specialized clinical research organizations creates substantial demand for comprehensive clinical trial supply solutions.
The regulatory environment in North America, particularly the FDA's stringent requirements for investigational drug handling and distribution, has fostered the development of sophisticated supply chain capabilities. The FDA's guidance on good clinical practice mandates detailed drug accountability procedures, temperature monitoring documentation, and chain of custody records throughout the clinical trial process. This regulatory rigor has prompted clinical trial supplies providers to establish state-of-the-art facilities, implement advanced quality management systems, and develop innovative technology solutions. The region's market leadership is further reinforced by substantial investments in clinical research infrastructure, with the National Institutes of Health allocating over USD 32 billion annually for medical research.
U.S. Clinical Trial Supplies Market Size
The U.S. represented the largest country market within North America. The concentration of pharmaceutical and biotechnology companies in major hubs such as Boston, San Francisco, and Research Triangle Park creates dense clusters of clinical trial activity requiring sophisticated supply chain support. The market benefits from well-developed transportation infrastructure, including specialized pharmaceutical logistics providers and extensive cold chain capabilities.
Investment in clinical trial innovation continues to drive market growth in the U.S. The adoption of decentralized clinical trial models accelerated during the COVID-19 pandemic and has become a permanent feature of the clinical research landscape. This shift has prompted clinical trial supplies providers to develop new service offerings, including patient-centric packaging, home delivery networks, and mobile nursing support for drug administration. A number of major pharmaceutical companies, such as Pfizer Inc., Bristol Myers Squibb, Novartis AG, Sanofi, and Hoffmann-La Roche Ltd., are headquartered or functional in the U.S. Moreover, as per government data, around 22,000 drugs are in their R&D pipelines; therefore, the rise in the R&D activities is expected to fuel the growth of the market.
Asia-Pacific Clinical Trial Supplies Market Size
Asia-Pacific will have the highest CAGR, driven by the expanding R&D pipelines in China, India, and Australia. Essentially, the availability of a large pool of patients to participate in clinical trials ultimately raises the demand for drug development. Additionally, there has been a rise in the number of contract research organizations conducting clinical-phase research lately. In-house clinical research is expensive and requires more resources and time, which is one of the main reasons pharma companies are outsourcing this phase of research and development. Additionally, outsourcing is an essential part of the biopharmaceutical sector, especially in the clinical phase of R&D.
The varied regulatory environment and infrastructure provide opportunities for clinical trial supply providers to offer integrated pan-Asian solutions. The development of regulatory harmonization initiatives across Asia-Pacific has facilitated market growth by reducing barriers to multi-country clinical trials. The ASEAN Common Technical Dossier and mutual recognition agreements between regulatory agencies have streamlined approval processes for clinical trial applications. However, managing clinical trial supplies across the region presents unique challenges, including diverse climatic conditions, varying cold chain infrastructure, and complex import/export regulations. Clinical trial supplies providers have responded by establishing regional distribution centers, developing country-specific expertise, and investing in temperature-controlled logistics networks. The region's market growth is further accelerated by government initiatives supporting clinical research, such as China's inclusion of innovative drug development in its national strategic priorities and India's streamlined clinical trial regulations.
China Clinical Trial Supplies Market Size
China represented the largest country market within the Asia-Pacific clinical trial supplies market. The regulatory modernization has attracted substantial investment from both domestic and international pharmaceutical companies, driving demand for clinical trial supplies services. China's large patient population, improving healthcare infrastructure, and growing biotechnology sector create favorable conditions for clinical research expansion.
The Chinese market presents unique opportunities for clinical trial supplies providers capable of navigating local requirements while maintaining global quality standards. The implementation of Marketing Authorization Holder regulations allows greater flexibility in clinical trial supply arrangements, enabling sponsors to leverage third-party logistics providers more effectively. Local clinical trial supplies providers have emerged to serve the domestic market, while international providers have established partnerships and local operations to capture growth opportunities. The market's expansion is supported by government investments in biomedical research infrastructure, with over 100 new clinical trial centers established in tertiary hospitals across major cities.
The geographical breakdown of the market is as follows:
North America (Largest Regional Market)
U.S. (Larger Country)
Canada (Faster-Growing Country)
Europe
Germany (Fastest-Growing Country)
U.K. (Largest Country)
France
Italy
Russia
Rest of Europe
Asia-Pacific (Fastest-Growing Regional Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest and Fastest-Growing Country)
Mexico
Rest of LATAM
Middle East and Africa
Saudi Arabia
South Africa (Largest and Fastest-Growing Country)
U.A.E.
Rest of MEA
Clinical Trial Supplies Market Share Analysis
The market is fragmented due to the presence of numerous regional and global players offering specialized services across logistics, packaging, labeling, storage, manufacturing, and comparator sourcing. Each clinical trial has unique requirements depending on therapeutic area, trial phase, and geographic location, leading to a diverse demand for tailored solutions. Additionally, stringent regulatory standards, varying country-specific guidelines, and the rising adoption of decentralized and hybrid trial models compel companies to operate in niche segments, making it a highly competitive market.
Key Clinical Trial Supplies Companies:
Thermo Fisher Scientific Inc.
Marken
Catalent Inc.
Parexel International
Almac Group Limited
Biocair International Limited
Sharp Services LLC
Movianto International BV
PCI Pharma Services
Eurofins Scientific
ICON plc
Lonza Group AG
Clinical Trial Supplies Market News
In March 2025, Deutsche Post AG acquired Cryoport Inc. to expand its life sciences and healthcare supply chain capabilities. This acquisition enhances DHL's ability to handle temperature-sensitive clinical trial supplies, particularly for biologics and cell therapies.
In May 2024, Myonex acquires Creapharm Group to enhance Myonex's capabilities in handling advanced therapies and strengthen its service offerings for pharmaceutical and biotech companies at both clinical and commercial stages.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws