Bio Acrylic Acid Market Size Estimation
Key Highlights
| Study Period | 2021 - 2032 |
| Market Size in 2025 | USD 592.0 Million |
| Market Size in 2026 | USD 671.9 Million |
| Market Size by 2032 | USD 1,506.1 Million |
| Projected CAGR | 14.3% |
| Largest Region | Asia-Pacific |
| Fastest-Growing Region | Asia-Pacific |
| Market Structure | Fragmented |
Market Size
Explore the market potential with our data-driven report
Bio-Acrylic Acid Market Key Insights
- Superabsorbent polymers are the largest derivative with 35% share, driven by consistent high-volume demand for disposable hygiene and medical products.
- Butyl acrylate is the fastest-growing derivative with 14.5% CAGR, supported by rising demand for durable, flexible coatings in construction and automotive.
- Paints & coatings lead application adoption, as manufacturers shift to bio-based binders to meet stricter VOC regulations.
- Surfactants are the fastest-growing application, fueled by the rapid shift toward plant-based ingredients in home and personal care formulations.
- Asia-Pacific is both the largest and fastest-growing region, with 40% share and 14.4% CAGR, benefiting from abundant agricultural feedstock and massive downstream manufacturing capacity.
Bio-Acrylic Acid Market Outlook
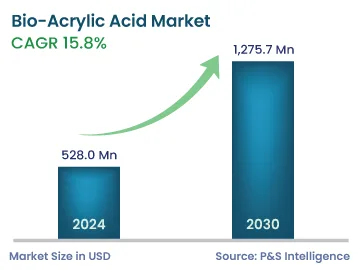
The bio-acrylic acid market size was USD 592.0 million for 2025, and it will grow by 14.3% during 2026–2032, to reach USD 1,506.1 million by 2032.
The market is expanding because brands and governments are looking for 'greener' raw materials to replace petroleum-based chemicals in everyday products. Bio-acrylic acid is derived from renewable resources (plants), but retains performance characteristics similar to conventional acrylic acid in paint, coatings, adhesive applications, and high-absorption applications. Emission and disposal regulations continue to force manufacturers to improve their manufacturing processes. Additionally, consumers continue to express growing concern over the chemical composition of the products they buy for their homes.
In response to these pressures, manufacturers are adopting cleaner production methods as well as transitioning to feedstocks that are renewable in nature. The combination of increasing regulatory requirements and changing consumer behaviour is driving faster adoption of bio-based alternatives across both consumer and industrial markets. According to the European Environment Agency, global bioplastic production capacity reached 2.0 million tonnes in 2023, but still accounted for less than 1% of total global plastics production. This highlights the significant headroom for bio-based chemicals to replace fossil-based incumbents.
Bio Acrylic Acid Market Emerging Trends & Growth Drivers
Shift from Pilot Plants to Continuous Manufacturing Is Major Trend
Producers are now developing actual large-scale production of products as opposed to running laboratory trials. Companies are transitioning from pilot plant production to continuous production to allow customers a predictable supply source. Tech groups have also changed the process by which bio-acrylic acid is developed, utilising cleaner processes that produce less waste and reduce energy use. Major chemical companies are collaborating with biotechnology companies to accelerate learning, reduce risk, and provide a more reliable supply of compatible products.
As end users desire "drop-in" products that can be used in current manufacturing facilities, suppliers will continue to develop high-quality products that meet or exceed the specifications of their petro-based counterparts. These factors are currently influencing the way the industry is developing in terms of developing a reliable, scalable, and compatible bio-based supply chain.
Global bioplastics production capacity expanded to 2.47 million tonnes in 2024, indicating a structural shift from pilot-scale development toward large-scale commercial manufacturing of renewable material alternatives. Arkema SA received full sustainability certifications for its acrylic monomer production facilities globally in 2025, supporting the availability of certified bio-attributed feedstocks for downstream chemical applications.
Large Buyer Sustainability Requirements Drive Market
An increasing number of companies now require their suppliers provide them with sustainable products or services, to adhere to their CSR policies and meet their consumers’ demand. In addition, larger purchasers have been requesting that their suppliers provide documentation regarding the origin of materials and processes used in production. These requests also trickle down through the supply chain to chemical manufacturers.
In addition, some end users are interested in reducing their exposure to oil price fluctuations by securing long term contracts on plant-based materials. As such, when large purchasers change what they will purchase, other producers rapidly adjust their product offerings to be competitive with the new purchasing patterns of the large purchaser.
According to the International Renewable Energy Agency, renewable sources accounted for 92.5% of all new global power capacity additions in 2024, reflecting the accelerating decarbonization of industrial energy inputs used across chemical manufacturing value chains. Large purchasing organisations with a combined spending power of USD 6.4 trillion in 2024 requested environmental disclosures from their suppliers, increasing pressure across supply chains to adopt traceable and sustainable raw material sourcing practices.
Bio Acrylic Acid Market Segmentation Analysis
Derivative Analysis
Superabsorbent polymers are the largest category, holding a market share of 35%, due to their use in consumer products that are repetitive purchases. Disposable diapers, hygiene pads, and medical absorbents all require rapid absorption of liquid, with an ability to retain absorbed liquids for a long period of time. The large quantities produced, along with long-term supply contracts, provide a consistent demand for this type of product.
Producers are attempting to reduce the carbon footprint of their products while maintaining their existing performance levels. Researchers are now testing and implementing bio-based feedstocks for the production of acrylic acid in order to achieve similar performance characteristics as the original material. In 2024, Nippon Shokubai announced plans to expand its installed superabsorbent polymer production capacity by 50,000 metric tonnes per year, to meet sustained global demand from hygiene and medical absorbent applications.
Butyl acrylate is the fastest-growing category, registering a CAGR of 14.5%, due to its widespread use as a flexible coating, adhesive, and sealant. Flexible coatings are used by the construction, packaging, and automotive industries to last long and remain pliable, rather than cracking when bent. Bio-based butyl acrylate allows manufacturers to meet their sustainability requirements while retaining the flexibility and durability of the existing products. Additionally, new forms of construction, as well as the increasing utilisation of lightweight materials, contribute to the growing demand for flexible binder applications. BASF SE commissioned new butyl acrylate production capacity in 2025 to support growing demand for automotive and construction coatings.

The derivatives analyzed in this report are:
- Superabsorbent Polymers (Largest Category)
- Butyl Acrylate (Fastest-Growing Category)
- Methyl Acrylate
- Ethyl Acrylate
- 2-Ethylhexyl Acrylate
- Elastomers
Application Analysis
Paints & coatings are the largest category, because nearly all buildings, machines, and manufactured goods require some type of surface protection. In order to be effective, coatings must have a binder with good adhesion and durability; therefore, acrylic-based input materials are a primary raw material. As industries continue to transition from the traditional solvent-based coatings to lower-VOC materials, they are seeking biobased raw materials to maintain the performance characteristics of coatings.
The global paints and coatings market value reached USD 190.2 billion in 2024, with forecasts for USD 255.3 billion by 2032. Architectural coatings account for 47% of the sales value, supporting sustained demand for acrylic-based binders and additives. Regulatory tightening on volatile organic compound emissions accelerates the adoption of low-VOC and resource-efficient coatings.
Surfactants are the fastest-growing category, registering a CAGR of 14.6%, due to a rapidly increasing demand for plant-based ingredients in cleaning & personal care products. Cleaning agents like soaps, detergents, and shampoos require effective surfactants to be gentle on skin and the environment. This has caused brands to aggressively push green labelling, causing the formulation community to replace traditional oil-based inputs with bio- based alternatives. Bio-acrylic acid assists in developing surfactants that meet all the new product claims, while maintaining cleaning performance.
Demand is being driven by growth in the sale of bio-based home care and personal care products. The global bio-based cosmetics & personal care ingredients market was valued at USD 5.16 billion in 2024, and it is projected to reach USD 7.32 billion by 2030, growing at a 6.2% CAGR during 2025–2030. Biobased or mineral-derived ingredients accounted for 66% of L’Oreal’s formulation inputs in 2024, reflecting the rapid substitution of petroleum-based inputs in surfactant formulations.
The applications analyzed in this report are:
- Paints and Coatings (Largest Category)
- Surfactants (Fastest-Growing Category)
- Adhesives and Sealants
- Textiles
- Sanitary Products
- Others
Drive strategic growth with comprehensive market analysis
Bio Acrylic Acid Market Regional Outlook
Asia-Pacific Bio-Acrylic Acid Market Analysis
Asia-Pacific holds the largest share, of 40%, and is growing at the highest CAGR, of 14.4%, as it is central to both the supply of raw materials for the manufacture of bio-based chemicals and the use of these products in final goods for end-users. It contains many countries with strong agricultural production (to provide plant-based feedstock) for the manufacture of bio-acrylic acids. It has a substantial number of manufacturers of packaging, textiles, hygiene, and building products, driving acrylic polymer consumption.
In addition, governments in some parts of the Asia-Pacific region are promoting local manufacturing and clean industrial processes to lower reliance on imports and to reduce pollution caused by existing chemical products. Multinational companies are shifting their sourcing to the Asia-Pacific region to take advantage of lower costs and shorter lead times to finished products. Additionally, new bio-based chemical plants are being constructed close to the end users, to provide a shorter supply chain and improve the rate of adoption.
China Bio-Acrylic Acid Market
China has the largest market size due to its massive downstream industries, such as coatings, packaging, and hygiene products. Additionally, investments in domestic biochemical production assist in reducing reliance on petro-based imports and enhance the country's ability to comply with increasingly stringent environmental regulations. According to China’s national statistics authority, national chemical fibre output reached 79.11 million tonnes in 2024, reflecting the scale of downstream textile and hygiene manufacturing that supports sustained demand for acrylic-based materials. According to China’s national economic planning authority, biomanufacturing was formally designated as a national growth engine in 2024, supporting policy-driven acceleration of bio-based materials and reduced reliance on petrochemical feedstocks.
India Bio-Acrylic Acid Market
India has the highest CAGR as a result of a large increase in homecare and personal care product demand and a government-driven boom in construction. Indian firms are implementing bio-based inputs to satisfy export requirements and increasing demand for safer, eco-friendlier consumer products. According to India’s national statistics authority, the construction sector recorded growth of 9.4% in 2024, supporting sustained coatings and adhesives demand.

North America Bio-Acrylic Acid Market Analysis
In North America, demand for bio-acrylic acid is shaped by a broader shift toward sustainability and regulatory support for renewable chemicals. Industries across personal care, packaging, coatings, adhesives, and agriculture are increasingly prioritising bio-based inputs over traditional petrochemical derivatives, driven by corporate commitments to reduce environmental impact and meet evolving consumer expectations for greener products. A strong innovation ecosystem, supported by R&D investment and advanced bio-production technologies, helps producers efficiently develop and supply bio-acrylic acid for applications like superabsorbent polymers and eco-friendly coatings.
Government programs and policies that encourage the use of bio-based materials further stimulate adoption, while collaborations between chemical companies and biotech firms accelerate commercialisation and market acceptance. This combination of sustainability trends, technical progress, and end-user demand underpins a robust and growing interest in bio-acrylic acid in the North American market.
Europe Bio-Acrylic Acid Market Analysis
Europe's market is heavily regulated by stringent laws on chemicals, waste management, and emissions, which have direct implications on the production methods and sale of bioacrylic acid. Manufacturers are required to undergo thorough compliance verifications before they can supply intermediate industries like coatings, adhesives, and personal care. It is a common practice among purchasers to require complete traceability of raw materials; hence, suppliers allocate more resources to certification and process audits. Moreover, the region houses a strong presence of speciality chemical companies that are oriented towards high-purity grades rather than large-scale production. Intraregional cross-border trade is very significant, logistics planning and regulatory compliance have become market players' routine business considerations.
The regions and countries analyzed in this report are:
- North America
- U.S. (Largest Country)
- Canada (Fastest-Growing Country)
- Europe
- Germany (Largest Country)
- U.K. (Fastest-Growing Country)
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific (Largest & Fastest-Growing Regional Market)
- China (Largest Country)
- India (Fastest-Growing Country)
- Japan
- South Korea
- Australia
- Rest of APAC
- Latin America
- Brazil (Largest Country)
- Mexico (Fastest-Growing Country)
- Rest of LATAM
- Middle East and Africa
- Saudi Arabia (Largest Country)
- U.A.E. (Fastest-Growing Country)
- South Africa
- Rest of MEA
Bio Acrylic Acid Market Share Analysis
The market is fragmented because there is no single group of players that controls supply or sets the direction for everyone else. Chemical and biotech startup firms and regional manufacturers have their own processes for producing this bio-based material. Some develop products in lower volumes, while others produce in massive volumes to serve larger industrial customers. Because the technology used to manufacture bio-acrylic acid is continuing to evolve, firms utilise a variety of feedstocks, such as sugarcane bagasse, and production processes, resulting in variable product quality and pricing.
The entry barrier for these new firms to join this industry is non-uniform; therefore, they may enter the market using new technologies or partnerships. Before committing to an extended contract, buyers also test multiple potential suppliers. This ensures that competition remains active and demand is spread among many competing firms.
Top Companies in Bio-Acrylic Acid Market:
- LG Chem Ltd.
- BASF SE
- The Dow Chemical Company
- Arkema S.A.
- Mitsubishi Chemical Corporation
- Evonik Industries AG
- Cargill, Incorporated
- Novozymes A/S
- Amyris, Inc.
- Genomatica, Inc.
- OPX Biotechnologies, Inc.
- BioAmber Inc.
- Sasol Limited
- Wanhua Chemical Group Co., Ltd.
- Shandong Kaitai Petrochemical Co., Ltd.
Bio-Acrylic Acid Market News
- In January 2026, Lakril Technologies commissioned its first continuous pilot plant for bio-acrylic acid, enabling consistent sample production for industrial testing and supporting potential scale-up of bio-based acrylic acid manufacturing capacity.
- In October 2025, Nippon Shokubai began commercial supply from new acrylic acid production capacity in Asia, increasing regional availability for downstream polymers and coatings applications.
- In August 2025, BASF started regular shipments from its butyl acrylate plant at its integrated chemical complex following initial production runs, marking the transition to active commercial supply of acrylic derivatives.
- In May 2025, Nippon Shokubai secured sustainability certification for its acrylic acid and superabsorbent polymer production lines, enabling the commercial supply of biomass-derived materials with a lower lifecycle carbon footprint.