This Report Provides In-Depth Analysis of the Automotive Hypervisor Market Report Prepared by P&S Intelligence, Segmented by Type (Bare Metal, Hosted), Automation Level (Semi-Autonomous, Fully Autonomous), Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), End User (Economy Vehicles, Mid-Priced Vehicles, Luxury Vehicles), Sale Channel (OEM, Aftermarket), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Automotive Hypervisor Market Future Outlook
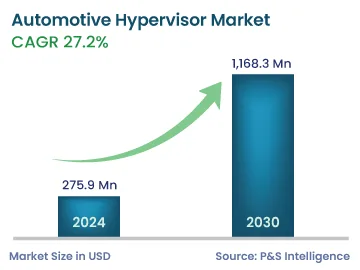
The automotive hypervisor market size will be an estimated USD 348.2 million for 2025, and it will grow by 27.2% during 2026–2032, to reach USD 1872.9 million by 2032.
The major factors responsible for the growth of the market include the rapid adoption of advanced driver assistance systems (ADAS), increasing demand for connected and autonomous vehicles, and the growing need for ECU consolidation in modern vehicles.
The surging demand for software-defined vehicles (SDVs) is a key factor driving the automotive hypervisor market size. Hypervisors support SDVs by securely running multiple operating systems on a single platform, a critical requirement for increasingly connected and autonomous vehicles. This technology allows automotive manufacturers to consolidate multiple ECUs into a single hardware platform, reducing vehicle weight, complexity, and cost while improving overall system efficiency.
The growing trend of electric powertrains, digitalization, shared mobility, and autonomous vehicles is driving the demand for advanced features in automobiles. As vehicles become more sophisticated and interconnected, the need for hypervisors will increase. A hypervisor is a software solution that enables multiple operating systems to run concurrently on a single hardware platform. It helps manage the complex systems in modern vehicles by ensuring secure and efficient communication between various components, such as safety features, the infotainment system, and autonomous driving functions. Consequently, the increasing demand for these advanced features in vehicles is boosting the market as automakers seek reliable and robust solutions to meet the challenges of this evolving industry.
Automotive Hypervisor Market Trends & Drivers
Software-Defined Vehicles (SDVs) Are Key Trend
The transition toward software-defined vehicles represents the most-significant automotive hypervisor market trend.
This evolution fundamentally changes how vehicles are designed, with hypervisors serving as the critical enabling technology.
Unlike traditional vehicles that relied on numerous discrete ECUs—sometimes exceeding 100 units in luxury vehicles—SDVs leverage hypervisors to consolidate these functions into centralized computing platforms.
As consumers want their smart devices to be always up to date, the expectation for vehicles to offer similar capabilities has grown.
Hypervisors enable this by providing the virtualization layer necessary for over-the-air (OTA) updates and continuous feature improvements.
BMW, with its upcoming Neue Klasse, is adopting modular SDV architectures that enable both scalability and updatability across a diverse range of models, from compact cars to high-end luxury vehicles.
This trend is further accelerated by regulatory requirements and consumer expectations.
According to a survey conducted by HERE Technologies, titled Safer Cars, Safer Roads, in November 2023, over 90% of the respondents in India indicated that ADAS is essential for road and driver safety.
Hypervisors enable this transformation by providing the secure, isolated environments necessary for running multiple operating systems simultaneously.
This ensures that safety-critical functions remain protected, while allowing for the integration of advanced features and regular software updates.
Adoption of Integrated ECU Platforms and ADAS/Autonomous Systems Is Biggest Driver
ECU consolidation and the rise of ADAS and autonomous driving are the key drivers for the automotive hypervisor market, increasing demand for secure, efficient computing platforms.
Traditional vehicles consist of numerous separate ECUs, each managing specific functions independently.
As the rise in electronic control units per vehicle decreases the efficiency, various automotive players are collaborating with original equipment manufacturers, consolidating ECUs without affecting their functionalities.
This consolidation subsequently decreases vehicle weight and saves space, which in turn reduces fuel consumption.
Hypervisors play a crucial role in this consolidation process by enabling multiple systems to run on a single hardware platform while maintaining isolation between critical and non-critical functions.
Type-1 hypervisors run directly on vehicle hardware, offering high performance and security.
This architecture is particularly important for safety-critical applications where system isolation is paramount.
The ability to virtualize multiple operating systems on a single ECU platform allows automakers to reduce the number of physical control units from over 100 in luxury vehicles to a more manageable number through domain controllers.
These advanced systems require sophisticated computing capabilities to process sensor data, make real-time decisions, and ensure safe operation.
In software-defined vehicles (SDVs), having multiple sensors enables higher ADAS/AD functions via OTA upgrades, with no changes to vehicle hardware.
Hypervisors facilitate this by managing the complex software environment required for autonomous driving, including sensor fusion, decision-making algorithms, and vehicle control systems.
They ensure that safety-critical ADAS functions remain isolated from infotainment and other non-critical systems, maintaining system integrity even in the event of software failures.
The bare metal category holds the larger market share, of 85%, in 2025, due to its direct hardware architecture and superior security features. Type-1 automotive hypervisors operate directly on vehicle hardware without an OS, offering high performance, strong security, and reliability for safety- and mission-critical applications. It directly controls the hardware resources and manages multiple guest OSs or virtual machines (VMs) on the same physical platforms. Moreover, it allocates hardware resources, such as the CPU, memory, storage, and 1/0 ports, to the VMs in a controlled and isolated manner. This allows multiple guest OSs to run efficiently, without interfering with each other.
The hosted category will have the higher CAGR, as this virtualization technology can run on top of the host OS. Additionally, these variants are generally easier to install and use compared to others. They also typically have user-friendly interfaces, and they can be set up quickly, without significant changes to the host system. Along with this, they allow users to run VMs with different guest OSs, thus making them suitable for running various applications and testing different software environments.
The types analyzed in this report are:
Bare Metal (Larger Category)
Hosted (Faster-Growing Category)
Automation Level Analysis
The semi-autonomous category holds the larger market share, of 80%, in 2025, because consumers are increasingly becoming interested in vehicles with advanced driver assistance features and seeking a balance between safety, convenience, and the driving experience. Moreover, the growing telecommunications & IT infrastructure, improving living standards, and rising number of upper-class people are driving the growth of this category.
The fully autonomous category could have the higher CAGR, as the technology matures and regulatory frameworks evolve, fully autonomous vehicles will increasingly rely on hypervisors to manage their sophisticated computing requirements.
The automation levels analyzed in this report are:
Semi-Autonomous (Larger Category)
Fully Autonomous (Faster-Growing Category)
Vehicle Type Analysis
The passenger cars category holds the largest market share, of 65%, in 2025, and it will have the highest CAGR, due to the rapid adoption of advanced features, including infotainment systems, ADAS, telematics, over-the-air updates, and wireless communication, in passenger cars for in-vehicle connectivity. These functionalities require efficient management and seamless integration, and the hypervisor technology plays a crucial role in ensuring reliable and secure operation. As per OICA, 67,674,745 passenger cars were manufactured worldwide in 2024, compared to 24,829,593 commercial vehicles.
Furthermore, the rising urbanization rate leads to an increase in the sale of cars, as many people use them for their daily commuting needs. Cars provide convenient and flexible transportation for daily commutes, school runs, and other routine travel. Along with this, passenger cars are at the forefront of safety advancements and the development of autonomous driving technologies. Hypervisors play a vital role in ensuring the separation and isolation of safety-critical functions, thus ensuring the proper implementation of features including automatic emergency brakes and lane keeping assistance.
The vehicle types analyzed in this report are:
Passenger Cars (Largest and Fastest-Growing Category)
Light Commercial Vehicles
Heavy Commercial Vehicles
End User Analysis
The luxury vehicles category holds the largest market share, of 60%, in 2025, and it will have the highest CAGR, due to the rising investments by automobile manufacturers to enhance vehicles' interior systems. Luxury cars are equipped with a wide range of advanced features, such as touchscreen infotainment systems, high-resolution displays, and intensive connectivity features. Moreover, they have powerful engines and advanced suspension systems, which necessitate sophisticated software management. Hypervisors ensure seamless coordination between systems in luxury cars, enhancing overall performance.
Furthermore, due to the presence of premium automotive companies, such as Audi, Mercedes-Benz, and BMW, in the U.S. and Germany, this category continues to grow in these countries. Additionally, the rising sales of luxury vehicles and the rising demand for automated systems in these vehicles propel the growth of the market in these nations.
The end users analyzed in this report are:
Economy Vehicles
Mid-Priced Vehicles
Luxury Vehicles (Largest and Fastest-Growing Category)
Sales Channel Analysis
The OEM category holds the larger market share, of 70%, in 2025, as they are responsible for integrating hypervisors during vehicle manufacturing. They prioritize safety and reliability, thus install these components to ensure that the critical functions are isolated. This is often done to meet the industry standards and government regulations for passenger, road, and vehicle safety. Major automotive manufacturers are heavily investing in driver assistance technologies, with companies like Continental AG and Bosch leading innovations in areas such as collision avoidance systems, automated parking capabilities, and advanced sensor technologies.
The aftermarket category will have the higher CAGR, propelled by the enhancing requirement and regulations over vehicle cybersecurity. As vehicles become more software-defined and updatable, the aftermarket for hypervisor-based solutions is expanding to support vehicle upgrades and retrofitting.
The sales channels analyzed in this report are:
OEM (Larger Category)
Aftermarket (Faster-Growing Category)
Drive strategic growth with comprehensive market analysis
Asia-Pacific holds the largest market share, of 40%, in 2025, and it will have the highest CAGR, of approx. 27.5%. The growing per capita income in emerging economies, such as China and India, has increased the purchasing power of customers, which is expected to raise the sale of passenger cars. In addition to this, the Asia-Pacific region is the home of some of the world's largest automotive manufacturers and component suppliers. This manufacturing strength enables the rapid adoption of new technologies across different vehicle models.
Moreover, the growing demand for OTA updates to enhance vehicle performance and address security vulnerabilities, rising advancements in automotive systems and infotainment systems, and increasing focus on enhanced safety and security in vehicles are some of the major factors propelling the market.
Additionally, the presence of major automotive manufacturers and technology companies in Japan and South Korea contributes to the region's market leadership. These countries are at the forefront of developing advanced automotive technologies, including hypervisor solutions that enable the next generation of connected and autonomous vehicles. Moreover, the easy availability of labor at a low cost for the mass production of vehicles has led to the establishment of many manufacturing plants in the region. Additionally, the emergence of local players with innovative models in developing markets is expected to drive the growth of the industry.
China Automotive Hypervisor Market Size
China plays a pivotal role in the region's dominance. The country's aggressive push toward vehicle electrification and autonomous driving, supported by substantial government investments and favorable policies, creates a robust market for automotive hypervisors. In July 2024, Baidu had 500 robotaxis in Wuhan and aimed to scale up to 1,000 units by the end of the year.
Europe Automotive Hypervisor Market Size
Europe accounts for the second-largest revenue share due to the rise in the demand for electric vehicles and the increase in the use of cutting-edge technologies in IC engines. Further, on account of the rising significance of market players such as BMW, Mercedes-Benz, and Audi, the luxury and premium automobile industry is expanding significantly in Germany.
North America Automotive Hypervisor Market Size
North America has significant growth, mainly attributed to stringent safety regulations and the early adoption of autonomous driving technologies. The U.S. leads the regional market with significant investments in autonomous vehicle development. In 2024, General Motors had more than 20 models with Super Cruise available and is expanding to 750,000 miles of mapped roads to use the system on. Major technology companies and automotive manufacturers are collaborating to develop advanced hypervisor solutions that meet the demanding requirements of autonomous driving systems.
Furthermore, the regulatory environment in North America supports the adoption of advanced automotive technologies. The NHTSA called for more advanced safety standards and announced new vehicle safety standards in early 2024, which also spurred greater adoption of advanced safety systems among automakers. This regulatory push, combined with consumer demand for advanced safety features, drives hypervisor adoption in the region.
The geographical breakdown of the market is as follows:
North America
U.S. (Larger Country)
Canada (Faster-Growing Country)
Europe
Germany (Largest Country)
U.K.
France (Fastest-Growing Country)
Italy
Russia
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Regional Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country)
Mexico (Fastest-Growing Country)
Rest of LATAM
Middle East and Africa
Saudi Arabia
South Africa (Largest Country)
U.A.E. (Fastest-Growing Country)
Rest of MEA
Automotive Hypervisor Market Share
The market is consolidated, with a few key technology companies and automotive suppliers dominating the landscape. This consolidation is largely driven by high technical barriers to entry, including stringent safety certifications and the need for deep automotive expertise, which limit the ability of new entrants to compete effectively. Developing automotive hypervisors requires significant investment in research and development, specialized knowledge of embedded automotive systems, and compliance with strict functional safety standards such as ISO 26262 ASIL D. Additionally, the need for close collaboration with automakers to integrate hypervisors seamlessly into complex vehicle architectures further strengthens the position of established players, making it difficult for smaller companies to gain a substantial market share.
Key Automotive Hypervisor Companies:
BlackBerry Limited
Renesas Electronics Corporation
NXP Semiconductors
Panasonic Holdings Corporation
Green Hills Software
Siemens AG
Visteon Corporation
Continental AG
Wind River Systems, Inc.
Elektrobit
SYSGO AG
OpenSynergy
Automotive Hypervisor Market News
In January 2025, BlackBerry Limited's QNX division announced a strategic collaboration with Microsoft Corporation to advance the development of SDVs. The collaboration will enable automakers to design, test, and refine vehicle software more efficiently through cloud-based solutions.
In November 2024, Elektrobit Automotive GmbH achieved a new milestone in software-defined mobility with the certification of its EB corbos hypervisor by TÜV SÜD. The certification, meeting the ISO 26262 ASIL B standard for automotive safety, designates the hypervisor as a Safety Element out of Context (SEooC), underscoring its readiness for safety-critical automotive applications.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws