This Report Provides In-Depth Analysis of the Automotive Filters Market Report Prepared by P&S Intelligence, Segmented by Vehicle (Passenger, Commercial), Type (Oil, Fuel, Cabin Air, Hydraulic, Transmission), Medium (Synthetic, Cellulose), Distribution Channel (Aftermarket, OEMs), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Automotive Filters Market Future Outlook
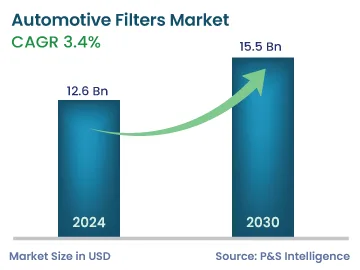
The automotive filters market size was USD 26.0 billion in 2025, and it will grow by 5.8% during 2026–2032, to reach USD 40.4 billion by 2032.
The market expansion is primarily driven by the stringent emission regulations, increasing vehicle production, and rising awareness about environmental protection across developed and emerging economies.
The growing concerns about air quality and environmental pollution have led governments worldwide to implement increasingly strict emission standards for vehicles. According to the U.S. Environmental Protection Agency, air pollution accounts for significant health impacts, with vehicular emissions contributing substantially to particulate matter and nitrogen oxides in urban areas. The EPA's 2024 Automotive Trends Report shows that automakers are investing heavily in advanced filtration technologies to meet new multi-pollutant emissions standards for model years 2027 and later.
The rise in global vehicle production, especially in emerging markets, has significantly increased the demand for automotive filters among original equipment manufacturers and aftermarket entities. The National Highway Traffic Safety Administration reports that vehicle production continues to grow despite supply chain challenges, with manufacturers focusing on integrating high-performance filters to ensure compliance with evolving safety and emission requirements. These filters play a crucial role in protecting engine components, improving air quality within vehicles, and extending vehicle lifespan through effective contamination control.
Automotive Filters Market Growth Factors
Stringent Government Emission Regulations Are Key Trends
The automotive filters market is witnessing an unprecedented transformation, driven by stringent government emission regulations implemented across major automotive markets globally.
The U.S. Environmental Protection Agency has established new multi-pollutant emission standards for model years 2027 and later, which significantly strengthens requirements for light-duty and medium-duty vehicles.
The EPA's regulatory framework extends beyond traditional emission controls to encompass comprehensive vehicle filtration systems.
The Worldwide Harmonized Light Vehicles Test Procedure (WLTP), developed under the United Nations, standardizes how vehicle emissions and fuel economy are measured across countries.
Complementing this, Global Technical Regulations (GTRs)—specifically GTR No. 15—set common emission testing protocols used by the EU, Japan, and China.
The Euro 6 standards, active since 2015, limit NOx, CO, hydrocarbons, and particulate matter, especially for diesel cars.
The EU imposes COâ‚‚ emission limits on automakers’ vehicle fleets, previously set at 95 g/km under Euro 6.
Under the Fit for 55 plan, the EU will phase out new combustion engine car sales by 2035, mandating 100% zero-emission vehicles.
China’s NEV credit system requires automakers to earn credits by producing or importing BEVs, PHEVs, and FCEVs.
This functions similarly to California’s ZEV mandate and supports China’s goals of having 25% NEVs by 2025 and net-zero emissions by 2060.
India implemented BS-VI norms in April 2020, skipping BS-V entirely to align closely with Euro 6.
The standards mandate ultra-low-sulfur fuel (10 ppm), tighter NOx, PM, and HC limits, and require onboard diagnostics and evaporative emission controls.
BS-VI applies to both petrol and diesel vehicles. India’s Corporate Average Fuel Efficiency (CAFE) Phase 2 limits fleet COâ‚‚ emissions to 113 g/km as of 2022–23.
In parallel, the FAME II scheme offers incentives for electric vehicle adoption and aims to reduce tailpipe emissions in urban transport and fleet operations.
Japan's Post-New Long-Term standards are some of the most rigorous, particularly for diesel vehicles, with extremely low thresholds for NOx and particulate emissions.
These standards ensure clean operation and high durability across the vehicle’s lifespan.
Japan uses a Low-Emission Vehicle (J-LEV) classification system that incentivizes automakers to produce cars with emissions 50–75% below the regulatory baseline.
Certified J-LEV models benefit from tax reductions and are promoted as part of Japan’s clean vehicle transition strategy.
Japan has its own test cycles (JC08 and WLTC) and mandates increasingly strict fuel economy and COâ‚‚ emissions limits.
The country promotes hybrid, battery-electric, and hydrogen fuel cell vehicles as part of its goal to achieve carbon neutrality by 2050.
Growing Environmental Health Concerns Propel Advanced Filtration Adoption
The increasing awareness of environmental health impacts from vehicular emissions has become a primary driver for advanced automotive filter adoption across global markets.
The World Health Organization reports that air pollution causes approximately 7 million deaths worldwide annually, with vehicular emissions contributing significantly to particulate matter and nitrogen oxides concentrations in urban areas.
The WHO’s data indicates that 99% of the people worldwide are exposed to air pollutant levels exceeding recommended limits, highlighting the urgent need for advanced emission control technologies such as automotive filters.
Government health agencies have documented the direct correlation between vehicular emissions and respiratory health problems, particularly in densely populated urban areas.
The EPA's analysis indicates that vehicles today are approximately 99% cleaner for common pollutants such as hydrocarbons, carbon monoxide, nitrogen oxides, and particulate emissions compared to vehicles in 1975, largely due to advanced filtration systems and emission control technologies.
The State of Global Air 2024 report reveals that air pollution has become the second-leading risk factor for death globally, accounting for 8.1 million deaths in 2021.
Heavy-duty vehicles contribute substantially to environmental pollution, accounting for over 40% of on-road nitrogen oxides emissions, over 60% of on-road particulate matter, and more than 20% of black carbon emissions according to the UN Environment Programme.
These statistics underscore the critical importance of automotive filters in reducing harmful pollutant concentrations and protecting public health.
International health organizations have identified specific pollutants of major public health concern, including particulate matter, carbon monoxide, ozone, nitrogen dioxide, and sulfur dioxide, all of which can be effectively controlled through advanced automotive filtration systems.
Government initiatives to address environmental health concerns have resulted in substantial investments in clean air technologies and emission reduction programs.
These initiatives create sustained market demand for high-performance automotive filters capable of meeting increasingly stringent health-based emission standards.
The growing recognition of environmental justice concerns has further amplified government focus on vehicular emission control and filtration requirements.
Populations living near major roadways face higher exposure to vehicular emissions, resulting in asthma, cardiovascular problems, and elevated hospitalization rates.
This awareness has led to enhanced regulatory requirements for automotive filtration systems and increased funding for clean air technology development and deployment.
Automotive Filters Market Segmentation Analysis
Vehicle Analysis
The passenger category held the larger market share, of 80%, in 2024, due to the increasing demand for luxury vehicles. Luxury vehicles feature high-quality HVAC and intake manifold filters to ensure superior comfort and optimized performance, necessitating regular filter replacements to maintain these standards. In order to maintain the performance levels of premium Vehicles, frequent filter replacements are also necessary. Moreover, with the increasing per capita income in emerging economies, the number of passenger cars being sold is also rising significantly. According to the Society of Indian Automobile Manufacturers, passenger vehicle sales increased from 30,69,523 units to 38,90,114 units from FY 2021–22 to FY 2022–23 and, further, to 42,18,750 units in FY 2023–24 and 43,01,848 units in FY 2024–25. Further, the automotive sector contributes more than 7% of India's GDP.
The commercial category will have the higher CAGR, due to the rising e-commerce activities around the world. The rapid urbanization has created new retail and e-commerce platforms, which require efficient logistics, thus leading to the growth of the market. Owners of fleets are worried about the typical annual mileage of commercial vehicles. Commercial vehicles operate in demanding conditions requiring frequent filter replacements to maintain engine efficiency and comply with emission standards. The U.S. Bureau of Transportation Statistics indicates steady growth in commercial vehicle production and usage, particularly in urban delivery and freight transportation sectors, directly supporting increased demand for automotive filters.
Commercial vehicles emit significantly more pollution than passenger vehicles across key pollutants. On average, they produce 4 to 10 times more COâ‚‚, 25 to 100 times more NOx, and 10 to 50 times more particulate matter (PM) per kilometer. This disparity is even more pronounced in real-world urban settings. For instance, in London, commercial vehicles like trucks and buses make up only about 20% of road traffic but contribute nearly 60% of vehicle-related NOx emissions. Similarly, in India, heavy-duty diesel vehicles represent less than 5% of the vehicle fleet yet are responsible for over 50% of transport-related PM emissions, highlighting their disproportionate environmental impact.
The vehicles analyzed in this report are:
Passenger (Larger Category)
Commercial (Faster-Growing Category)
Type Analysis
The cabin air category held the largest market share, of 40%, in 2024, and it will have the highest CAGR, driven by the increasing consumer awareness of air quality and health concerns. The EPA's research on indoor air quality and vehicular cabin environments has highlighted the importance of effective cabin filtration for passenger health and comfort. Rising pollution levels in urban areas and growing health consciousness among consumers contribute to increased demand for high-efficiency cabin air filters.
The types analyzed in this report are:
Oil
Fuel
Cabin Air (Largest and Fastest-Growing Category)
Hydraulic
Transmission
Medium Analysis
The synthetic category held the larger market share, of 75%, in 2024, and it will have the higher CAGR. This is due to the widespread use of synthetic filters, which offer higher filtration efficiency than traditional cellulose filters. This means the former can capture smaller particles, thus providing better protection to the engine. Apart from this, they have a lower replacement rate, which helps vehicle owners save on maintenance expenses. Synthetic media filters can capture smaller particles and maintain consistent performance throughout their service interval, making them preferred for modern high-performance engines. The EPA's emission standards increasingly require fine particle filtration capabilities that synthetic media can effectively provide.
The media analyzed in this report are:
Synthetic (Larger and Faster-Growing Category)
Cellulose
Distribution Channel Analysis
The OEMs category held the larger market share, of 85%, in 2024. The sales of filters are closely tied to the production of various types of vehicles, including passenger cars, light commercial vehicles, and heavy commercial vehicles. As these components are essential in the engine, filtering out dust, dirt, pollen, and other contaminants from the incoming air and fuel. Clean air is crucial for the proper functioning and longevity of the engine. Hence, as vehicle production increases, the demand for these filters will also rise, to keep vehicles functioning properly, safely, and fuel-efficiently.
Additionally, to increase vehicle comfort and fuel economy, market players are sourcing higher-quality raw materials and components for various automobile parts and systems. OEMs generally opt for a dedicated distribution channel to get high-quality auto parts. These contracts include the supply of a specific quantity of filters, depending on the number of vehicles planned for production.
The aftermarket category will have the higher CAGR, driven by the large installed base of vehicles requiring regular filter replacements throughout their operational life. As vehicle owners replace filters several times over a vehicle’s lifespan, the demand for aftermarket filters remains consistently strong. The National Highway Traffic Safety Administration data shows increasing average vehicle age, which supports continued growth in aftermarket filter demand.
The distribution channels analyzed in this report are:
Aftermarket (Faster-Growing Category)
OEMs (Larger Category)
Drive strategic growth with comprehensive market analysis
Automotive Filters Market Geographical Analysis
Asia-Pacific Automotive Filters Market Size
Asia-Pacific held the largest market share, of 40%, in 2024, and it will have the highest CAGR, of approx. 6.0%, driven by substantial automotive production in China, India, and Japan. The region benefits from strong domestic vehicle demand, favorable government policies supporting automotive manufacturing, and significant foreign direct investment in automotive production facilities. Government initiatives promoting cleaner transportation and emission control have further supported automotive filter demand across the region.
The region is supported by a robust domestic vehicle demand, government policies favoring automotive manufacturing, and substantial foreign direct investment in production facilities. Environmental regulations in key markets such as China and India have become increasingly stringent, requiring advanced filtration technologies to meet emission standards. The adoption of international emission standards equivalent to Euro VI has accelerated demand for high-performance automotive filters throughout the Asia Pacific region.
North America Automotive Filters Market Size
North America represents the second-largest regional market and is expected to maintain steady growth during the forecast period. The U.S. Environmental Protection Agency's stringent emission regulations and the National Highway Traffic Safety Administration's safety standards drive consistent demand for advanced automotive filters. The region's emphasis on vehicle safety, environmental protection, and fuel efficiency creates sustained market opportunities for filter manufacturers.
The region's mature automotive market is characterized by high vehicle ownership rates, extensive highway infrastructure, and regular vehicle maintenance practices that support robust aftermarket filter demand. Government initiatives promoting clean air and emission reduction continue to drive the adoption of advanced filtration technologies across passenger and commercial vehicle segments.
U.S. Automotive Filters Market Size
Under the Clean Air Act, the U.S. EPA has implemented standards that phase in from 2027 through 2032, mandating significant reductions in greenhouse gas emissions, hydrocarbons, nitrogen oxides, and particulate matter. The NHTSA has complemented EPA's emission standards with fuel economy requirements that necessitate optimal engine performance through effective filtration. The agency reports that vehicles equipped with advanced filter systems demonstrate measurably better performance in meeting both emission and fuel economy targets.
Furthermore, the EPA's Phase 3 greenhouse gas emissions standards for heavy-duty vehicles, announced in 2024, establish even more stringent requirements for commercial vehicle filtration systems. These standards apply to vocational vehicles such as delivery trucks, refuse haulers, and transit buses, as well as tractor-trailer trucks beginning with model year 2027. In November 2024, the EPA released its 50th annual Automotive Trends Report, demonstrating record-high fuel economy and record-low greenhouse gas emissions, highlighting the critical role of automotive filters in achieving environmental performance improvements.
The cumulative impact of these federal regulations extends throughout the automotive supply chain, with filter manufacturers investing heavily in research and development to meet evolving performance requirements. According to EPA's regulatory impact analysis, the implementation of these standards will result in approximately 7.2 billion metric tons of cumulative carbon dioxide reductions over the program's lifetime, emphasizing the critical role of automotive filters in achieving these environmental objectives.
Government enforcement mechanisms and compliance monitoring systems further strengthen the regulatory framework driving automotive filter demand. The EPA conducts yearly assessments of manufacturers’ compliance with greenhouse gas emission standards, with detailed reporting requirements that include filtration system specifications and performance data. This regulatory oversight ensures consistent market demand for compliant filtration technologies and drives continuous innovation in filter design and manufacturing processes.
Europe Automotive Filters Market Size
Europe also holds a significant market share, due to the growing sale of luxury vehicles and the strict government norms pertaining to harmful carbon emissions and public health improvement. Moreover, the presence of automotive manufacturers, such as BMW, Mercedes, and Volkswagen drives the market. This is because high-end vehicles have high filter replacement frequencies and employ premium-quality HVAC filters for superior comfort levels.
The geographical breakdown of the market is as follows:
North America
U.S. (Larger Country)
Canada (Faster-Growing Country)
Europe
Germany (Largest and Fastest-Growing Country)
U.K.
France
Italy
Russia
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country)
Mexico (Fastest-Growing Country)
Rest of LATAM
Middle East and Africa
Saudi Arabia (Fastest-Growing Country)
South Africa (Largest Country)
U.A.E.
Rest of MEA
Automotive Filters Market Share Analysis
The market is fragmented with numerous players competing across both OEM and aftermarket segments. The market fragmentation is driven by several factors that create opportunities for both large multinational corporations and smaller regional manufacturers to coexist and compete effectively. The fragmented nature of the market stems from diverse product requirements across different vehicle types, filter categories, and regional preferences. This diversity creates market segments where smaller, specialized manufacturers can compete effectively against larger players by focusing on specific niches, regional markets, or particular filter technologies. Additionally, geographic fragmentation also characterizes the market, with regional players maintaining strong positions in their home markets due to local automotive industry relationships, distribution networks, and cost advantages.
Key Automotive Filters Companies:
DENSO Corporation
Robert Bosch GmbH
Sogefi Group
Hengst SE
Hollingsworth & Vose
MAHLE GmbH
K&N Engineering Inc.
MANN+HUMMEL International GmbH & Co. KG
Parker-Hannifin Corporation
Ahlstrom Holding 3 Oy
Freudenberg & Co. KG
Toyota Boshoku Corporation
Automotive Filters Market News
In June 2024, MANN+HUMMEL International GmbH & Co. KG introduced its FreciousPlus cabin air filter with nanofiber technology, engineered to deliver enhanced filtration of ultrafine particles throughout the entire service interval while maintaining optimal airflow performance.
In January 2023, MANN+HUMMEL International GmbH & Co. KG announced a strategic investment in M-Filter Group for the expansion of its business in Europe.
In April 2023, Ahlstrom Holding 3 Oy introduced Ahlstrom ECO, a new range of renewable and sustainable filtration solutions for automotive applications. The impregnated filtration medium, which contains lignin, has a lower carbon footprint than the standard media containing fossil-fuel-based resins.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws