U.S. Language Learning Software Market Size & Share Analysis - Trends, Drivers, Competitive Landscape, and Forecasts (2025 - 2032)
This Report Provides In-Depth Analysis of the U.S. Language Learning Software Market Report Prepared by P&S Intelligence, Segmented by Component (Software, Services), Deployment (On-Premises, Cloud), Language Type (English, German, Spanish, Mandarin), Learning Mode (Business-to-Business, Business-to-Customer), Learning Type (Synchronous Learning, Asynchronous Learning), End User (Academic, Non-Academic), Pricing Model (Subscription-Based, One-Time Purchase, Pay-Per-Course, Enterprise & Institutional Pricing), and Geographical Outlook for the Period of 2019 to 2032
U.S. Language Learning Software Market Size Forecast
Market Statistics
Study Period
2019 - 2032
2024 Market Size
USD 3.1 Billion
2025 Market Size
USD 3.6 Billion
2032 Forecast
USD 11.6 Billion
Growth Rate(CAGR)
18.3%
Largest Region
Northeast
Fastest Growing Region
West
Nature of the Market
Fragmented
Largest End User Category
Academic
Growth Forecast
Key Players
Key Report Highlights
Market Size and Forecast
Industry Trend
Regulatory Landscape
Demand Trend Analysis
Companies Recent Strategical Developments
Key Stakeholders
Voice of Industry Experts/KOLs
Future Opportunity
Explore the market potential with our data-driven report
U.S. Language Learning Software Market Overview
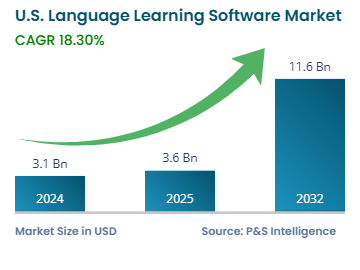
The U.S. language learning software market size was USD 3.1 billion in 2024, and it will grow by 18.3% during 2025–2032, to reach USD 11.6 billion by 2032. The market is driven by the surge in the demand for multilingual capabilities, expansion of online learning platforms, rising immigration and cultural diversity, surging number of people going on international tours from the U.S., startup of corporate training programs, and government support and sponsorship.
Subscription-based learning techniques with freemium policies have become popular in language education due to the rising usage of mobile devices by students for education. Apart from individual students, educational institutions and corporate businesses are the major end users since they require multilingual personnel.
U.S. Language Learning Software Market Dynamics
Self-Paced Learning Is Key Market Trend
Learning control has become the preferred educational method for most students since they have flexible study opportunities.
Such systems allow learners to adjust their learning pacing since they need not comply with rigid classroom schedules.
The learning approach adapts to professionals, students, and casual learners who need to organize language education between their other responsibilities.
Self-paced learning allows for better retention since being under such a strict timeline invariably leads to stress, which brings down student interest.
Growth of Corporate Language Training Is a Key Driver
Companies understand that approaching international markets with a culturally diverse workforce requires multilingual workers who can improve both internal collaboration and external customer interactions.
The healthcare, technology, and finance industries thus provide training in Spanish, Mandarin, and French.
This demand encourages organizations to develop AI-powered language learning tools that merge interactive mobile features for employees’ professional development.
Digital language training software is becoming more popular since hybrid work environments offer employees independent study options.
Over 30 million immigrants from Latin America and Asia are part of the country’s workforce, compelling them as well as their employers to learn each other’s language.
U.S. Language Learning Software Market Segmentation Analysis
Component Analysis
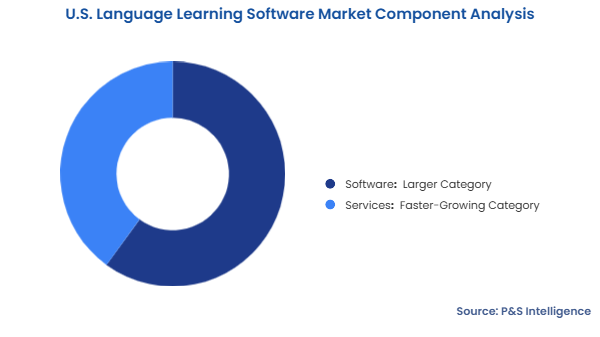
The software category held the larger market share, at 60%, in 2024, because various digital platforms and mobile apps allow users to learn languages. Any app or platform created for a language learner who would rather have their own hours and lessons will generally include interactivity through lessons, quizzes, and gamification of appeal and retention.
Platforms such as Duolingo, Babbel, or Rosetta Stone have gained traction in online and in-person communities due to their user-friendliness, accessibility, and options of many languages. That is why with the increasing use of smartphones and the internet, the usage of self-learning apps continues to rise.
The components analyzed in this report are:
Software (Larger Category)
Services (Faster-Growing Category)
Deployment Type Analysis
The cloud-based category has the larger share and the higher CAGR, of 20%. This is because cloud-based platforms provide round-the-clock access to learning material through any internet-connected device. The deployment also offers scalability, which allows people to learn at no extra costs or degradation of operational efficiency.
The deployment types analyzed in this report are:
Cloud-Based (Larger and Faster-Growing Category)
On-Premises
Language Analysis
The Spanish category held the largest market share, of 55%, in 2024, because of its widespread use and practical importance. The sizable Hispanic demographic in the U.S. chooses Spanish as a popular course because it offers substantial benefits both for everyday life and business purposes. Even native English speakers are learning Spanish to communicate with their Latino and Latina handymen and handywomen better. As per studies, almost 30% of the construction workers in the country are Hispanic, engaged most prominently in manual, low-paying jobs, such as painting and roofing.
The Mandarin category will grow at the highest CAGR, of 19.5%, during the forecast period. This is because of the worldwide political developments and a growing user base for Chinese social media apps, including Xiaohongshu. The anticipated TikTok ban has directed public attention toward Mandarin learning, driving the demand for the associated software. Of late, white-collar jobs in the U.S. have witnessed an increasing presence of Chinese immigrants, which compels U.S. natives to learn Mandarin to get the maximum out of their employees.
The language types analyzed in this report are:
Spanish (Largest Category)
Mandarin (Fastest-Growing Category)
English
German
Others
Learning Mode Analysis
The business-to-business category held the larger market share, of 70%, in 2024, because of the rising popularity of language training in the corporate sector, government agencies, and educational institutions. Organizations purchase language education systems to establish better international communication to enhance productivity levels and meet customer requirements in overseas markets. Business organizations direct their language training emphasis to industry-specific terminology to enhance their global business operations.
The business-to-customer category will grow at the higher CAGR, of 23%, during the forecast period. An increasing number of people are gaining linguistic abilities through mobile apps, AI-driven platforms, and subscription-based e-learning platforms to advance their careers, while enhancing their personal experiences and travel abilities. Online B2C learning platforms create an environment of self-paced learning, teach via gamification, and are affordable.
The learning modes analyzed in this report are:
Business-to-Business (Larger-Category)
Business-to-customer (Faster-Growing Category)
Learning Type Analysis
The asynchronous learning category held the larger market share, of 75%, in 2024. This is because it allows users to choose from educational content, and access it at their preferred speed, while not interacting with instructors or classmates in real-time. Students gain flexibility through self-paced courses, pre-recorded video lessons, mobile apps, and digital tools.
The synchronous learning category will grow at the higher CAGR, of 22%, during the forecast period. This is because students are eager for personalized and immersive learning experiences, which automatic language tutoring systems and virtual reality educational systems offer. The educational interaction system functions live in virtual classrooms, with additional possibilities for learners to interact with instructors through both live webinars and online interactive sessions.
The learning types analyzed in this report are:
Asynchronous Learning (Larger Category)
Synchronous Learning (Faster-Growing Category)
End User Analysis
The academic category held the larger market share, of 65%, in 2024, and it will grow at the higher CAGR during the forecast period. This is because most learners are professionals who want to boost their job eligibility, immigrants who want to fit in the local society better, and people learning languages for personal enjoyment, travel, cultural interaction, or career growth.
The reason behind the rising popularity of digital language learning platforms lies in their adaptability, user-friendly nature, and practical learning approach. The growth of this category is driven by the emergence of AI-driven learning tools and interactive mobile applications.
The end users analyzed in this report are:
Academic (Larger and Faster-Growing Category)
Non-Academic
By Pricing Model Analysis
The subscription-based category held the largest market share, of 45%, in 2024, and it also has the highest CAGR of 20.5%. This is because this model enables continuous and predictable revenue for organizations, which proves attractive for business sustainment in the long term. Moreover, with subscriptions, users are able to receive regular updates, new content, and features. Users can also scale their plans as necessary, thus enabling them to complete advanced courses within budget.
Subscription models also reduce the initial financial burden on customers, which is particularly relevant to individuals and families who would rather not want to pay a large one-time fee. A lot of subscription-based platforms do tend to have a free trial or freemium option, and so they draw people who may be hesitant to sign up for something directly and that helps change the way they convert those users to paying customers once they've really gotten a taste of something good.
The pricing models analyzed in this report are:
Subscription-Based (Largest and Fastest-Growing Category)
On-Time Purchase
Pay-Per-Course
Enterprise & Institutional Pricing
Drive strategic growth with comprehensive market analysis
U.S. Language Learning Software Market Regional Outlook
The Northeast held the largest market share, of 45%, in 2024 due to its large population, cultural diversity, strong academic presence, and existence of the UN headquarters. The region is home to hordes of immigrants, students, and professionals who need language skills for educational purposes, job opportunities, and social acceptance. Language learning solutions are witnessing a rising demand in the Northeast because of the presence of several prestigious educational institutions, Harvard University, MIT, NYU, Penn State, and Columbia University, where the faculty and students need strong multilingual expertise for their international research projects and global collaboration work.
The West region will grow at the highest CAGR, of 19%, during the forecast period. This is because it is home to technology-savvy residents, has multicultural characteristics, and witnesses a rising usage of digital and mobile education tools. San Francisco, Los Angeles, and Seattle are key technology innovation centers, which drives the acceptance of AI-powered learning applications. The region is also prominent among tourists, especially its Pacific Coast and Rocky Mountains.
The geographical breakdown of the market is as follows:
Northeast (Largest Category)
West (Fastest-Growing Category)
Midwest
South
U.S. Language Learning Software Market Share
The market is fragmented due to variations in learning style, language requirement, and end user demographics. Individual consumers as well as corporate buyers long for customized solutions, stimulating the popularity of specialized platforms catering to different languages, skill levels, and learning preferences. While established players are bombarded by competition, new startups have entered the fray as well with something different, such as integration with AI or gamification and industry-specific training. The rapid rate at which new technologies develop and the trend of custom, on-demand learning drive fragmentation, with vendors scrambling to meet the varying user needs.
U.S. Language Learning Software Companies:
Duolingo
Rosetta Stone
Babbel
Pimsleur
Tandem
Mango Languages
Clozemaster
Preply
Speechling
Learnship
Open English
Practice Makes Perfect
U.S. Language Learning Software Market News
In May 2024, Rosetta Stone acquired LiveMocha, a social technology platform with a large user base in LATAM, Russia, and China, for USD 8.5 million.
InJuly 2023, Preply received an additional USD 70 million in funding, reach a total of USD 120 million as its total Series C funding Amount. The funding was used to develop the AI features of is language learning app.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws