U.S. Electronic Design Automation Software Market Size & Share Analysis - Trends, Drivers, Competitive Landscape, and Forecasts (2025 - 2032)
This Report Provides In-Depth Analysis of the U.S. Electronic Design Automation Software Market Report Prepared by P&S Intelligence, Segmented by Type (Computer-aided Engineering (CAE), IC Physical Design and Verification, Printed Circuit Board and Multi-Chip Module (PCB and MCM), Semiconductor Intellectual Property (SIP)), Deployment (Cloud, On-premises), Application (Analog Design, Digital Design, Mixed-Signal Design), End Use (Aerospace and Defense, Automotive, Healthcare, Industrial, Consumer Electronics), and Geographical Outlook for the Period of 2019 to 2032
U.S. Electronic Design Automation Software Market Size Estimation
Market Statistics
Study Period
2019 - 2032
2024 Market Size
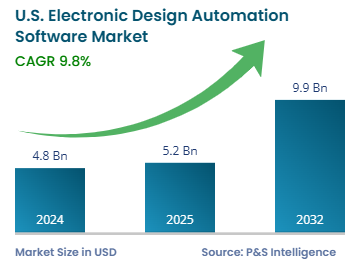
USD 4.8 Billion
2025 Market Size
USD 5.2 Billion
2032 Forecast
USD 9.9 Billion
Growth Rate(CAGR)
9.8%
Largest Region
West
Fastest Growing Region
West
Nature of the Market
Fragmented
Largest Application Category
Digital Design
Growth Forecast
Key Players
Key Report Highlights
Market Size and Forecast
Industry Trend
Regulatory Landscape
Demand Trend Analysis
Companies Recent Strategical Developments
Key Stakeholders
Voice of Industry Experts/KOLs
Future Opportunity
Explore the market potential with our data-driven report
U.S. Electronic Design Automation Software Market Overview
The U.S. electronic design automation software market valued at USD 4.8 billion in 2024, and this number is expected to increase to USD 9.9 billion by 2032, advancing at a CAGR of 9.8% during 2025–2032.
This is due to improvements in semiconductor technology, rising usage of AI and IoT, and increasing difficulty in electronic circuit designs. Innovative design applications for analog, digital, and mixed-signal applications are gaining momentum because of the increasing usage of computer-aided engineering, IC physical design & verification, and semiconductor IP. With the growth of the automotive, aerospace & defense, medical device, and consumer electronics sectors, EDA tools are being used to provide scalability and enhance design production. Chip development depends on SPICE simulation, functional verification, and timing analysis for optimization.
The market is experiencing a transformation as cloud-based deployment provides design engineers with cost-efficient and scalable solutions. The demand for logic synthesis, physical synthesis, and power optimization is rising because companies require efficient and high-performance semiconductors to advance their digital transformation efforts.
U.S. Electronic Design Automation Software Market Emerging Trends
Shift toward Cloud-Based Solutions Is Key Trend
Cloud-based EDA tools are more scalable and flexible in terms of usage than the standard on-premises solutions, enabling users to access them at their convenience.
A cloud-based EDA solution proves less expensive for users over time because they do not need to purchase initial licenses or physical hardware components.
Design teams are working on cloud-based platforms so they can collaborate regardless of distance, to obtain equivalent access to design assets.
Cloud-based EDA tools minimize the design cycle duration, which decreases product time to market.
Cloud-based EDA service providers maintain seamless software updates, which enable them to offer the newest features to their users.
Cloud-based access delivers designers advanced operational capabilities without requiring them to wait for software development or hardware implementation.
Cloud providers dedicate major resources to developing robust security frameworks, which protect the stored data, ensuring full confidentiality for user information.
Growing Demand for Advanced Semiconductors Propels Market
The growing semiconductor sector and its related fields, such as photonics and micromechanics, drive the requirement for EDA software.
Users need advanced EDA tools to create efficient processors and systems because of the rising adoption of the IoT technology in new kinds of devices.
Advanced EDA tools are needed to create intricate IC designs, especially since manufacturers want smaller electronic devices with increased performance.
This drives the demand for advanced EDA tools among businesses making smaller electronic products for consumer electronics, medical devices, and automobiles.
Using artificial intelligence and machine learning in electronic design automation tools allows designers to get a more-precise result and find new design solutions quickly.
The increasing complexity of system-on-a-chip (SoC) makes testing each design necessary to prevent any error before manufacturing.
Verification tools help designers find errors quickly, which allows them to fix them before reaching the production stage, saving time and money.
The broadening use of AI and automation across semiconductor codecs drives organizations to use stronger verification methods to test layouts faster and enhance design quality.
The consumer electronics, automotive, and telecommunications industries use functional verification tools to guarantee that their products adhere to the high performance and reliability standards.
Local synthesis tools convert high-level design descriptions into optimal structures that can meet all the required space and performance requirements.
Today's complex IC and SoC designs used in consumer technology, automobiles, and internet platforms need this basic design technique.
The growing digital design complexity leads chipmakers to use advanced logic synthesis tools.
U.S. Electronic Design Automation Software Market Segmentation Analysis
Component Insights
The computer-aided engineering (CAE) category dominates the market with a revenue share of 55% in 2024. CAE software is essential in developing complex electronic systems and testing them before production, which helps firms reduce waiting times in launching their semiconductor and electronic products. More companies are outsourcing the manufacturing, and customers want advanced computing services. The rising demand for cloud services and the rising complexity in circuit integration contribute to market development.
The report examines the following types:
Computer-aided Engineering (CAE) (Largest and Fastest-Growing Category)
IC Physical Design and Verification
Printed Circuit Board and Multi-Chip Module (PCB and MCM)
Semiconductor Intellectual Property (SIP)
Deployment Insights
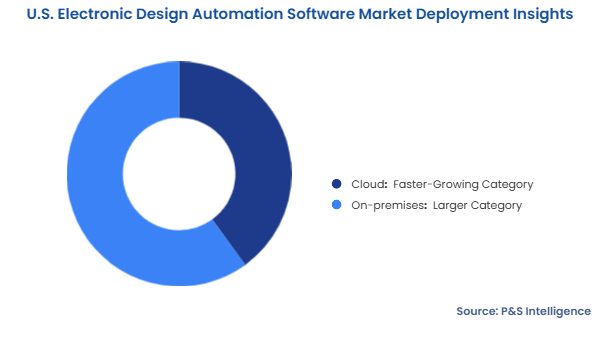
The on-premises category is the larger with 60% revenue in 2024, and this category is further expected to maintain its position during the forecast period. Organizations use on-premises deployment because it lets them handle their data securely, while customizing their system for specific needs. Companies prefer on-premises EDA solutions to maintain complete control over their electronic designs, which serve as intellectual properties with protected patents.
Here are the deployments studied in the report:
Cloud (Faster-Growing Category)
On-premises (Larger Category)
Application Insights
Digital design is the largest category with a revenue share of around 55% because of the rising demand for ICs and SoCs in all major industries. Digital design tools make circuit development easier through logic synthesis, simulation, and quality tests, to ensure that the outputs achieve all design specifications. The advancements in AI IoT and 5G communications further drive the demand for superior digital design tools.
The report examines the following applications:
Analog Design
Digital Design (Largest Category)
Mixed-Signal Design (Fastest-Growing Category)
End Use Insights
Consumer electronics holds the largest share, of around 40%, because of the growing usage of smartphones, laptops, tablets, and smart home devices. The need for increasingly complex and feature-laden consumer electronics items drives the demand for advanced EDA tools to develop complex integrated circuit with improved performances and dependability.
The end uses covered in the report are:
Aerospace and Defense
Automotive (Fastest-Growing Category)
Healthcare
Industrial
Consumer Electronics (Largest Category)
Others
Drive strategic growth with comprehensive market analysis
U.S. Electronic Design Automation Software Market Regional Outlook
West is the largest and fastest-growing region, with 45% share and 10% CAGR, respectively, led by Silicon Valley in California and Seattle in Washington. Western U.S. is home to the biggest semiconductor, technology, and EDA software companies. The research institutions and universities here need advanced EDA software systems to make chips and test their performance. The West leads the market because companies are rapidly taking advantage of the AI, 5G, and HPC technologies.
The regions analyzed in this report are:
Northeast
Midwest
West (Largest and Fastest-Growing Category)
South
U.S. Electronic Design Automation Software Market Share Analysis
The market is fragmented as a limited number of companies— Synopsys, Cadence, Siemens EDA, and Mentor Graphics Company—hold the major share combined.
New companies struggle to enter this market because producing development tools costs a lot, and the major firms control extensive intellectual property, which they rely on to build effective EDA suites.
Major EDA producers merge with any newcomer and partner with other leaders to develop more products and add advanced AI/ML features to their existing software.
U.S. Electronic Design Automation Software Companies:
Aldec Inc.
Altair Engineering Inc.
Altium LLC
Ansys Inc.
Autodesk Inc.
Cadence Design Systems Inc.
Keysight Technologies
Silvaco Inc.
Synopsys Inc.
Advanced Micro Devices Inc.
EMA Design Automation, Inc.
The MathWorks Inc.
U.S. Electronic Design Automation Software Market Developments
In August 2024, Renesas Electronics Corporation acquired Altium Limited; the acquisition was announced in February 2024.
In May 2023, Ansys Inc. entered into an agreement to acquire Diakopto.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws