U.S. Defense Equipment Market Size & Share Analysis - Key Trends, Future Opportunities, Growth Strategies, and Forecasts (2025 - 2032)
This Report Provides In-Depth Analysis of the U.S. Defense Equipment Market Report Prepared by P&S Intelligence, Segmented by By Armed Forces (Army, Navy, Air Force, Space Force), By Operation (Manual Defense Equipment, Autonomous Defense Equipment), By Propulsion (ICE, Electric, Hybrid), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
U.S. Defense Equipment Market Analysis
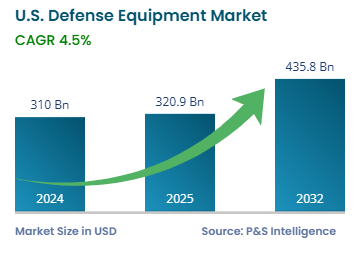
The U.S. defense equipment market size stood at USD 310 billion in 2024, and it is expected to grow at a CAGR of 4.5% during 2025–2032, to reach USD 435.8 billion by 2032.
The market is driven by increasing defense spending, technological advancements, geopolitical tensions, need for supply chain resilience, and export policy reforms. As per the Stockholm International Peace Research Institute, the defense spending of the U.S. rose by 5% in 2024 from 2023, reaching USD 997 billion. The U.S. not only spends to secure its borders and people but also other nationalities. It has been a prominent supporter of Ukraine, Israel, and Saudi Arabia, and in recent times, India and Pakistan as well. The key areas of focus for the Department of Defense include air superiority, nuclear missiles and bombs, naval might, and cyber defense and space warfare.
U.S. Defense Equipment Market Emerging Trends & Growth Drivers
Technological Advancements and Unmanned Systems Are Key Trends
Military operations are becoming automated, reflected in the rapidly increasing demand for unmanned aerial vehicles (UAVs), autonomous combat drones, and AI-infiltrated surveillance systems.
The Reaper and Predator are among the most-iconic drones used by the U.S. military.
These systems can easily monitor and gather information without human involvement, thus minimizing risk and collateral damage.
These systems enhance battlefield awareness and efficiency by harnessing real-time data for decision-making.
The U.S. military invests significantly in these technologies to ensure strategic control over likely future international security challenges and enhanced national defense.
The recently acquired and demonstrated technologically advanced defense equipment in the country include Loyal Wingman, an AI-drive aircraft; Aegis Combat System, Project Maven, RAIDER-X, an autonomous ground vehicle; F-35 Lightning II stealth fighter aircraft, direct energy weapons, hypersonic missiles, Integrated Visual Augmentation System, and optionally manned fighting vehicles.
The National Defense Authorization Act (NDAA), Federal Aviation Administration (FAA), and DoD Directive 3000.09 aim to balance security, ethics, innovation, and control.
Geopolitical Tension and Increasing Defense Spending Drive Market Growth
The increasing global security threats, especially in the European region, impels the U.S. to analyze its defense needs more closely and expand military funding for possible threats.
With numerous localized conflicts underway, such as Israel’s offensive against Hezbollah, Houthis, and Hamas, the Russia–Ukraine war, perpetual fears of hostilities between China, Taiwan, and Japan, and the ever-volatile India–Pakistan relations, the threat of all these converging into the Third World War has been looming for quite a while.
The military has begun replacing its 400 LGM-30 Minuteman ICBMs with the new-generation LGM-35A Sentinel at its air bases in Wyoming, Montana, and North Dakota.
The modernization of nuclear forces is expected to necessitate spending of USD 946 billion till 2034.
In April 2025, the government requested the Trump administration or USD 27 billion for the Golden Dome missile shield, with the project involving the construction of 14 warships.
The same month, the Pentagon requested USD 400 million more for the F-47 6th-generation stealth fighter jet being developed by The Boeing Company.
Since 2017, the country has been working on 10 Gerald R. Ford class of nuclear-powered aircraft carriers to replace its long-standing Nimitz class.
The Foreign Assistance Act, Arms Export Control Act (AECA), Mutual Defense Assistance Act, And European Deterrence Initiative (EDI) have been implemented to strengthen international relations, support counter-terrorist operations, and drive defense equipment sales for U.S. companies.
U.S. Defense Equipment Market Segmentation Analysis
Insights by Armed Forces
Navy held the largest market share, over 40%, in 2024, in terms of value, because the U.S. has been investing heavily in its naval force of late to support global maritime defense and protect its interests across the world. The U.S. maintains the world’s largest and most-potent fleet of aircraft carriers, submarines, and destroyers, which need substantial funds for operations, modernization, and technological modernization. The rising tension in the Indo-Pacific and Arctic regions compels the country to maintain naval dominance. Hence, the U.S. is increasing its funding for warships, developing new missile systems, and researching advanced technologies.
Space force will have the highest CAGR during the forecast period. Satellite communication systems, space surveillance tools, space-based tools, and systems that protect computer networks get substantial federal funding. As per government sources, the President’s Budget for the U.S. Cyber Command rose from USD 1.6 billion in 2024 to USD 1.7 billion in 2025, while the NDAA has allocated an additional USD 30 billion. Moreover, the congress has allocated USD 28.7 billion more to the U.S. Space Force for FY 2025.
These armed forces were analyzed:
Army
Artillery systems
Mortars
Howitzers
Tactical vehicles
Trucks
Fuel tankers
JLVTs
Communication & electronic warfare systems
Tactical radios
Satellite communication
Electronic countermeasures
Ground combat systems
Tanks
IFVs
APCs
Navy (Largest Category)
Surface vessels
Aircraft carriers
Cruisers
Frigates
Fighter jets
F/A-18 Super Hornet
F-35C Lightning II
Ship-launched missiles
Tomahawk
Anti-ship
Surface-to-air
Sonar systems
Towed-array
Dipping
Underwater Drones
UUVs
Mine countermeasures systems
Air Force
Fixed-wing aircraft
Fighter
Transport
Rotorcraft
Combat search
Rescue helicopters
Space systems
Military satellites
Unmanned aerial systems
Reconnaissance drones
Combat drones
Space Force (Fastest-Growing Category)
Satellites
Navigation
Weather
Ground systems
Satellite control networks
Optical systems
Launch systems
Launch vehicles
Spaceports
Launch facilities
Insights by Operation
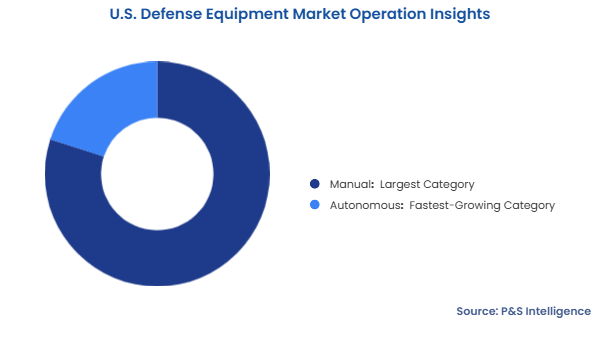
The manual bifurcation held the larger market share, of 80%, in 2024 due to the long-standing involvement of traditional defense systems, such as fighter jets, warships, and tanks, in wars and counter-terrorist operation.
The autonomous category will have the higher CAGR during the forecast period due to the advancements in AI, shift toward automation, and adoption of unmanned technologies. The idea is to improve efficiency, reduce the risk of human deaths, and support better decision making in serious situations.
These operations were analyzed:
Manual (Largest Category)
Autonomous (Fastest-Growing Category)
Insights by Propulsion
The ICE category held the largest market share, of 85%, in 2024. The defense sector relies on ICE-based terrestrial vehicles, aircraft, and ships for long missions because military operations require strong and reliable systems that can work efficiently under harsh conditions. Moreover, diesel can be easily carried in barrels and tanks, which makes ICE propulsion more convenient and ready for anything. Moreover, manned aircraft majorly rely on ATF-driven turbine engines for maximum power, range, service ceiling, and payload delivery.
The electric category will have the highest CAGR during the forecast period. The improving battery technology, increasing demand for stealth capability, and growing importance of the U.S. military on sustainability drive the usage of electric propulsion systems. Electrically driven military vehicles are quiet, less detectable, eco-friendly, and ideal for modern unmanned missions. The aircraft carriers and submarines of the U.S. Navy already operate on nuclear-powered electric propulsions, giving them practically unlimited range, except for other supplies.
These propulsions were analyzed:
ICE (Largest Category)
Electric (Fastest-Growing Category)
Hybrid
Drive strategic growth with comprehensive market analysis
U.S. Defense Equipment Market Regional Market Performance
The South held the largest market share, of 45%, in 2024. North Texas, Florida, and Alabama form the largest defense markets as they host vital defense contractors, aircraft manufacturing facilities, and major shipyards. Moreover, the tense U.S.–Mexico border necessitates the deployment of an adequate number of security personnel with the appropriate equipment to detect and apprehend illegal intruders.
The West will have the highest CAGR during the forecast period due to the fast progress in aerospace and defense technology. California is home to several key defense technology companies, space exploration ventures, and research institutions, which are focused on such next-generation military technologies as artificial intelligence defense systems and autonomous warfare. Moreover, due to its long coastline, the West has a strong presence of the navy and coast guard.
The regions analyzed for this report include:
Northeast
West (Fastest-Growing Category)
Midwest
South (Largest Category)
U.S. Defense Equipment Market Share Analysis
The market is severely consolidated as a few major players hold large shares.
The strict government rules for safety and effectiveness, the need for heavy investment in research and development, and the importance of building long-term contracts with the military make it difficult for smaller or new companies to compete.
Companies such as Lockheed Martin, BAE Systems, Boeing, Northrop Grumman, RTX, and General Dynamics supply advanced defense systems, tanks, howitzers, aircraft, missiles, and cybersecurity solutions.
Moreover, fighter engines are primarily supplied by GE Aerospace, Safran, Pratt & Whitney, and Rolls-Royce plc.
Shipbuilding is consolidated among Ingalls Shipbuilding, Newport News Shipbuilding, and General Dynamics NASSCO.
FN Manufacturing, Colt's Manufacturing Company, Barrett Firearms Manufacturing, SIG Sauer, and U.S. Fire Arms Manufacturing Company are the primary contractors for small arms, including rifles and pistols.
U.S. Defense Equipment Companies:
Lockheed Martin
Raytheon Technologies
General Dynamics
Boeing
Northrop Grumman
United Launch Alliance, L.L.C
General Electric
The Aerospace Corporation
Science Applications International Corporation (SAIC)
The MITRE Corporation
Textron Inc.
L3Harris Technologies
U.S. Defense Equipment Market Developments
In February 2024, Lockheed Martin Corporation finalized an agreement with Indra to supply four Multi-Mission Surface Combat Ships (MMSCs) to the Royal Saudi Arabian Navy with an advanced electronic defense system.
In November 2023, Northrop Grumman Corporation completed the thermal vacuum tests for the Arctic Satellite Broadband Mission (ASBM), a two-satellite constellation that will provide broadband communications to the U.S. Space Force and Space Norway in the Northern Polar Region.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws