Logo - P&S Intelligence
  • Home
  • Report Store
    • Report Store
      • Consumer Products
      • Life Sciences
      • ICT and Media
      • Semiconductor and Electronics
      • Chemicals and Materials
      • Automotive and Transportation
      • Power and Energy
      • Heating & Cooling
      • Aerospace & Defense
      • Construction & Heavy Machinery
    • Back
  • Services
  • Knowledge Center
    • Knowledge Center
      • Press Journals
      • Blogs
      • Case Studies
    • Back
  • About Us
  • Contact Us
U.S. Auto Parts Manufacturing Market
  • Buy Report
  • Home
  • Automotive and Transportation
  • Automotive Components and Electronics
  • U.S. Auto Parts Manufacturing Market

U.S. Auto Parts Manufacturing Market Size & Share Analysis - Trends, Drivers, Competitive Landscape, and Forecasts (2025 - 2032)

This Report Provides In-Depth Analysis of the U.S. Auto Parts Manufacturing Market Report Prepared by P&S Intelligence, Segmented by Component (Engine, Electrical & Electronics, Driveline and Powertrain, Interiors and Exteriors, Body and Chassis, Wheel and Tire), Vehicle Type (Passenger Cars, Commercial Vehicles, Two-Wheelers), End User (OEMs, Aftermarket), Propulsion (ICE, BEV, HEV, PHEV, FCEV), and Geographical Outlook for the Period of 2019 to 2032

  • Published: March 2025
  • Pages: 145
  • Report Code: 13366
Share:
  • Order this report
  • Inquire Before Ordering
Build Data-Driven Growth Strategies

This report contains the pivotal information you need to refine and strengthen your business strategy.

Need Assistance?
  • +91 93541 34657
  • [email protected]
  • Report Summary
  • Table of Contents
  • Sample Pages

U.S. Auto Parts Manufacturing Market Growth Potential

Market Statistics

Study Period 2019 - 2032
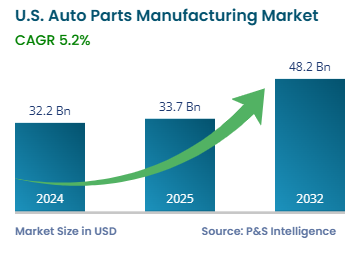
2024 Market SizeUSD 32.2 Billion
2025 Market SizeUSD 33.7 Billion
2032 ForecastUSD 48.2 Billion
Growth Rate(CAGR) 5.2%
Largest RegionMidwest
Fastest-Growing RegionSouth
Nature of the Market Fragmented
Largest End User Category OEMs

Growth Forecast

U.S. Auto Parts Manufacturing Market Growth Forecast

Key Players

U.S. Auto Parts Manufacturing Market Companies

Key Report Highlights

  • Market Size and Forecast
  • Industry Trend
  • Regulatory Landscape
  • Demand Trend Analysis
  • Companies Recent Strategical Developments
  • Key Stakeholders
  • Voice of Industry Experts/KOLs
  • Future Opportunity

Explore the market potential with our data-driven report

U.S. Auto Parts Manufacturing Market Outlook

The U.S. auto parts market size was USD 32.2 billion in 2024, and it will grow by 5.2% during 2025–2032, to reach USD 48.2 billion by 2032.

The market is driven by the growing demand for automobiles for personal, public, and freight transportation. These demands are themselves generated by a booming population, rampant urbanization, expanding industries, rising popularity of e-commerce, and people’s continuous economic prosperity.

The major influences on the industry in current times include the transition to electrification of vehicles, automation of driving functions, adoption to eco-friendly production methodologies, and variations in the cost of raw materials. Additionally, the U.S. auto parts industry enjoys an enhanced supply chain and quality workforce, making it easy for it to grow and adapt to the new trends in the automobile sector. As consumers become more sophisticated and environmental standards become stricter, the sector is undertaking research and development on efficient, high-quality, and environment-friendly components.

U.S. Auto Parts Manufacturing Market Emerging Trends

Technological Advancements in Components and Assembly Methods Are Major Trends

In recent years, auto parts markers in the U.S. have suffered a strong compulsion to adapt to the changing client needs and strict environmental restrictions. New technologies, such as robotics, 3D printing, AI, and IoT, are becoming popular as a means to improve the accuracy, efficiency, and quantity of production.

The usage of 3D printing is growing as it helps reduce material waste and produce more sustainably. Similarly, robotics enhance precision and cut labor requirement, thus adding to cost-efficient operations in two ways. Moreover, with the increasing demand for software-defined vehicles, autonomous driving, and ADAS features, an array of sensors and cutting electronic components are being developed and integrated into automobiles.

Similarly, more-efficient engines, which burn less fuel to propel the vehicle across the same distance, thus driving down emissions, are becoming popular. Another key trend is lightweight materials, which help cut the vehicle weight and emissions significantly. To integrate them into the automobile, more of adhesives and sealants are required over the conventional nuts, bolts, and welds.

Moreover, with the growing demand for personalization and more convenience, automobiles are being integrated with comprehensive digital cockpits, drive-by-wire controls, ambient and mood-based lighting, NVH materials, high-speed 5G connectivity, and self-updating computer systems.

Even EVs are continuously being enhanced to offer longer driving distances for the same amount of electricity. This offers lucrative opportunities for companies developing critical components, such as onboard chargers, traction motors, battery management systems, and battery packs.

Expanding Automotive Industry Is Key Market Driver

The quintessential driver of the demand for auto parts in the country is the expanding production of automobiles. As per OICA, automotive sales in the U.S. rose from 1,42,30,324 units in 2022 to 1,60,09,268 units in 2023, driven by the growing demand for public, personal, and freight transportation.

Trucks remain the most-important carrier of freight within the country. As per the Bureau of Transportation Statistics, they carried 12,975 million tons of the total 17,867 million tons of freight shipped around the country in 2023. Further, by 2050, 17,545 million tons of the total 24,911 tons of freight will be carried by lorries domestically. Moreover, as per the American Automobile Association (AAA), people in the country spend over an hour driving around each day.

In response, automobile production in the country rose from 10,060,339 units in 2022 to 11,189,985 units in 2023, according to OICA. While the expanding automotive production drives the demand for vehicle components among OEMs, the rising average automobile age makes the aftermarket a lucrative customer for Tier 1, 2, and 3 suppliers. The BTS reports an increase in the average passenger car age in the U.S. from 13.6 years in 2023 to 14 years in 2024. In the same way, the average operational life of light-duty trucks increased from 11.8 years to 11.9 years in the same period.

Growing Adoption of Electric Vehicles Is Main Opportunity

The growing penetration of EVs is a key opportunity since electric power trains, the latest generation of high-capacity battery packs, sophisticated thermal management systems, and lightweight materials are substantially dissimilar from the components used in the conventional IC engine vehicles. Because the federal and state governments are imposing more-stringent emission standards and providing support to EVs, OEMs are expanding EV production.

As per the International Energy Agency (IEA), EV sales in the U.S. increased by 40% in 2023 from 2022. Moreover, CNBC notes a 20% share of EVs in the total sales of vehicles in the country in 2024. The U.S. hopes to have ZEVs make up 100% of the automobile sales by 2050.

EVs have a lot more sophisticated electronic components than a traditional ICE automobile, which is why semiconductor companies with a strong focus on the automotive sector of the U.S. stand to benefit handsomely in the coming years.
Segmentation and Category Analysis

Component Analysis

  • The engine category held the largest market share, of 35%, in 2024.
  • The engine is the most-expensive and important component used in traditional ICE vehicles, which still make up most of the automotive sales.
  • An engine has multiple cylinders, ranging from two of typical two-wheelers to up to eight for an average car.
  • This means an equal number of pistons, spark plugs, pipes, pumps, and fuel and exhaust valves, along with the entire engine block and chains that connect the crankshaft and the camshaft.
  • While the demand for engine parts among OEMs may reduce in the coming years owing to the rising focus on EVs, the aftermarket is still expected to be a major consumer.
  • This is because of the rising average age of vehicles, which means that all the ICE vehicles produced till the point their production ceases will continue to operate till the end of their life.
  • This will create a requirement for the regular service, maintenance, and replacement of engine parts.
  • The electrical and electronic components category will grow at the highest CAGR, of 5.5%, during the forecast period.
  • This is due to the rise in the sales of electric vehicles, which drives the demand for components, such as batteries, traction motors, sensors, and control modules.
  • Additionally, new-generation vehicles, be it EVs or ICE variants, rely on infotainment systems, connectivity, and ADAS in contemporary times.

The components analyzed in this report are:

  • Engine (Largest Growing Category)
  • Electrical & Electronics (Fastest-Growing Category)
  • Driveline and Powertrain
  • Interiors and Exteriors
  • Body and Chassis
  • Wheel and Tire
  • Others

Vehicle Type Analysis

  • The passenger cars category held the larger market share, at 45%, in 2024.
  • This is because of the rising sale of cars to meet personal and public transportation needs.
  • While the majority of the population owns a car, a large number of people travel by taxis within and between cities.
  • The rising popularity of app-based cab services is another factor propelling the demand for car parts across the U.S.
  • The commercial vehicles category will grow at the highest CAGR, of 5.8%, during the forecast period.
  • This is due to the growing logistics fleets and rising number of buses for urban and long-distance transportation.
  • Moreover, the use of electric commercial vehicles is rising as organizations are focusing on environmental sustainability.
  • In current times, a key driver for the demand for LCVs is the booming e-commerce industry, which propels the volume of last-mile deliveries.

The vehicle types analyzed in this report are:

  • Passenger Cars (Largest Category)
  • Commercial Vehicles (Fastest-Growing Category)
  • Light Commercial Vehicles
  • Heavy Commercial Vehicles
  • Two-Wheelers

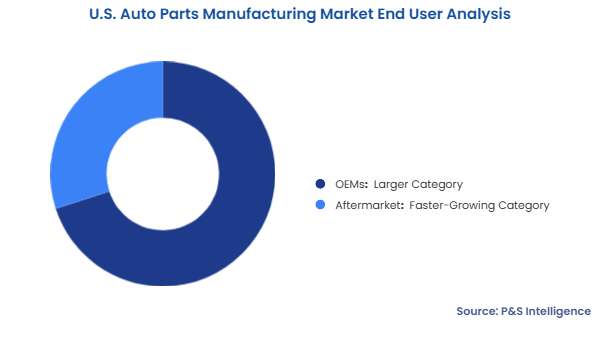
End User Analysis

  • The OEM category held the larger market share, in 2024.
  • This is because automobile manufacturers procure all kinds of auto parts in bulk to build new vehicles.
  • Since the U.S. produces millions of vehicles each year, the demand for parts among OEMs is high.
  • The aftermarket category will grow at the higher CAGR, during the forecast period.
  • This is due to the rising average age of the vehicles on American roads, which is now 12–13 years across all segments.
  • As vehicles become old, the consumption of spare parts for servicing, repairs, and replacement increases among garages and automotive workshops.
  • Moreover, the increasing popularity of buying car accessories online, as well as the popularity of customized vehicles drive the market revenue in this category.
  • The shift toward electric and hybrid vehicles is also giving a new impetus to aftermarket entities.

U.S. Auto Parts Manufacturing Market Segmentation Analysis

The end users analyzed in this report are:

  • OEMs (Larger Category)
  • Aftermarket (Faster-Growing Category)

Propulsion Analysis

  • The ICE category held the largest market share, in 2024.
  • This is because gasoline and diesel vehicles are still dominant in the country since they are well understood, available in more models, and cheaper.
  • Additionally, EVs come with a prominent range anxiety, primarily because of inefficient batteries and motors and an inadequate public EV charging infrastructure.
  • Though the uptake of EVs is rapidly increasing, they comprise a low proportion of the total stock compared to conventional internal combustion engine vehicles.
  • The BEV category will grow at the highest CAGR, during the forecast period.
  • This is because government subsidies, policies, and emission standards and the larger trend of greener mobility are stimulating EV production and sales.
  • Automakers are aggressively ramping up their EV manufacturing capabilities, therefore driving the demand for parts such as motors, batteries, and electric drivetrains at a skyrocketing rate.
  • To address range anxiety, more-efficient batteries, power converters, and motors are being developed.

The propulsions analyzed in this report are:

  • ICE (Largest Category)
  • BEV (Fastest-Growing Category)
  • HEV
  • PHEV
  • FCEV

Drive strategic growth with comprehensive market analysis

U.S. Auto Parts Manufacturing Market Regional Growth Dynamics

  • The Midwest region held the largest market share, at 40%, in 2024.
  • This is because regional states, including Michigan, Ohio, and Indiana, are among the biggest automobile makers in the world due to the presence of plants of major OEMs, such as General Motors, Ford, and Stellantis.
  • The region has a well-developed infrastructure, talented workforce, and an established supply chain, making it the largest buyer of auto parts.
  • The South region will grow at the highest CAGR, of 5.8%, during the forecast period.
  • This is due to the setup of production plants by many overseas automobile companies.
  • Additionally, the vast population generates a huge demand for vehicles, which need regular repairs and maintenance, thus propelling auto parts sales to the aftermarket.

The geographical breakdown of the market is as follows:

  • Northeast
  • West
  • Midwest (Largest Category)
  • South (Fastest-Growing Category)

U.S. Auto Parts Manufacturing Market Share

The U.S. auto parts market share is consolidated because a few giants, such as Robert Bosch GmbH, Aptiv plc, Forvia SE, and BorgWarner Inc., hold a combined major share. These firms have huge international exposure, up-to-date technology, and direct ties with the automakers. Moreover, considering the lucrative nature of the market and its potential for stiff competition, these large players often acquire smaller companies before the latter’s significance rises. Further, because automobiles are a considerable investment, people read up thoroughly on the brands and parts before getting repairs or replacements.

U.S. Auto Parts Manufacturing Companies:

  • Robert Bosch GmbH
  • ZF Friedrichshafen AG
  • BorgWarner Inc.
  • Lear Corporation
  • Aptiv PLC
  • Dana Incorporated
  • Cooper-Standard Holdings Inc.
  • Valeo SA
  • Goodyear Tire & Rubber Company
  • Forvia SE
  • Denso Corporation
  • Continental AG

U.S. Auto Parts Manufacturing Market News

  • In December 2024, Robert Bosch GmbH signed an agreement to receive up to USD 225 million in funding from the U.S. Department of Commerce under the CHIPS and Science Act to develop semiconductor components for EVs.
  • In September 2024, Tesla Inc. announced plans to increase its parts procurement from India to a worth of almost USD 1.9 billion for 2024 from USD 1bn for 2022, to minimize its dependence on China.

Want a report tailored exactly to your business need?

Request Customization

Empowering Leaders Across the Globe

Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.

Client Partners
Client Partners (mobile view)
Testimonials
Client Testimonials

Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.

McKinsey & Company

India
Unmatched Standards
Unmatched Standards

Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights

Data Security
Complete Data Security

We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws

  • Request Customization
  • Request Free Sample
close

Customize the Report to Align with Your Business Objectives

*
*
*
close

Request the Free Sample Pages

*
*
*
Connect with us
Quick Links
  • Research Methodology
  • Career
  • Media Citations
  • FAQs
  • Events and Conferences
Find Help
  • How to Order
  • Privacy Policy
  • Terms & Conditions
  • Sitemap
24/7 Customer Support
  • India: +91 93541 34657
  • For business enquiries - [email protected]
  • For career enquiries - [email protected]
  • Dun-Verified
  • Paypal-Secure

©2026 P&S Intelligence. All Rights Reserved.

We use cookies to enhance your experience. By continuing to use this site you consent to our use of cookies. Privacy Policy