Metal Cleaning Chemicals Market Size & Share Analysis - Emerging Trends, Growth Opportunities, Competitive Landscape, and Forecasts (2025 - 2032)
This Report Provides In-Depth Analysis of the Metal Cleaning Chemicals Market Report Prepared by P&S Intelligence, Segmented by Product (Solvent, Aqueous), Ingredients (Surfactants, Chelating Agents, Solvents, pH Regulators, Solubilizers), Metal Type (Steel, Aluminium, Copper), End User (Manufacturing, Automotive, Aerospace, Healthcare, Construction), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
Metal Cleaning Chemicals Market Future Outlook
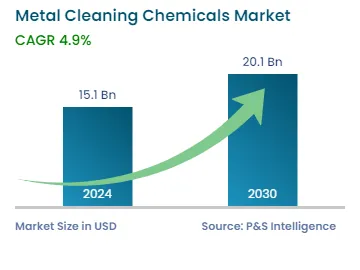
The metal cleaning chemical market size was USD 15.1 billion in 2024, and it will grow by 4.9% during 2025–2032, to reach USD 21.9 billion by 2032.
The market growth is primarily driven by the expanding manufacturing and automotive industries worldwide, coupled with stringent regulations promoting the adoption of environmentally sustainable cleaning solutions.
As industrial activities continue to surge across emerging economies, the demand for effective metal surface treatment solutions has become paramount. Metal cleansing chemicals play a critical role in removing contaminants such as oil, grease, rust, and particulates from metal surfaces, ensuring optimal equipment performance and product quality. The increasing production of lightweight aluminum and magnesium alloys in vehicle manufacturing has further intensified the need for specialized cleaning formulations.
The market is witnessing a significant shift toward aqueous-based cleaning solutions, driven by growing environmental consciousness and regulatory pressures to reduce volatile organic compound (VOC) emissions. Moreover, the rise in the need for eco-friendly solutions is owing to the growing awareness among businesses and consumers of the deadly effects of the traditional ones on human health and the environment. The demand for green detergents, water-based solutions, and bio-based solvents is on the rise due to their reduced impact on the environment, low toxicity, and enhanced worker safety.
Metal Cleaning Chemicals Market Trends & Drivers
Rising Demand for Bio-Based and Green Metal Cleaning Chemicals Is Key Trend
The shift toward sustainable and eco-friendly cleaning solutions represents a fundamental trend in the metal cleansing chemicals industry.
Bio-based alternatives, derived from plant and animal materials, are gaining significant traction as manufacturers seek to reduce their environmental footprint while maintaining cleaning efficacy.
These green formulations typically contain surfactants derived from renewable resources and are free from toxic substances, making them safer for both workers and the environment.
Companies are now innovating and offering biobased alternatives in the market. Gemtek Products offers SC Aircraft and Metal Cleaners, which is a bio-based aircraft and metal cleaning product.
The product is versatile and suitable for removing oils, fluids, carbon, fuels, and other common contaminants from aluminum, sensitive magnesium, aircraft exterior and parts, and aerospace manufacturing equipment.
The adoption of bio-based alternatives eliminates the need for special personal protective equipment (PPE), resulting in cost savings and enhanced worker safety.
The regulatory landscape is increasingly favoring environmentally sustainable solutions, with governments worldwide implementing stringent restrictions on the use of hazardous chemicals.
The European Union's REACH regulations have particularly influenced the market dynamics, pushing manufacturers to develop safer alternatives.
The CLP Regulation (EC No 1272/2008) governs the classification, labeling, and packaging of chemical mixtures, requiring safer hazard communication and supporting the industry shift toward non-toxic and environmentally safe formulations.
This regulatory pressure, combined with growing corporate sustainability commitments, is accelerating the transition toward green metal cleansing chemicals across various industries.
Growing Emphasis on Workplace Safety and Environmental Compliance Is Biggest Driver
The mandates for workplace safety and environmental compliance requirements are the key drivers for the metal cleansing chemicals landscape.
Industries are increasingly prioritizing worker health and safety, leading to a preference for low-toxicity, non-flammable cleaning solutions.
The aqueous technology is preferred as it is cost-effective and environment-friendly.
Companies are implementing comprehensive chemical management systems to ensure proper storage, handling, and disposal of cleaning chemicals.
This includes investing in employee training programs and adopting best practices for chemical safety.
The shift toward safer formulations is not merely regulatory compliance but also reflects corporate social responsibility initiatives and the recognition that worker wellbeing directly impacts productivity and operational efficiency.
Environmental sustainability has become a key differentiator in the market, with end-users increasingly demanding products with lower environmental impact throughout their lifecycle.
This includes considerations for biodegradability, reduced water consumption, and minimal ecological toxicity.
Manufacturers are responding by developing concentrated formulations that reduce packaging waste and transportation emissions while maintaining cleaning effectiveness.
The European Parliament has adopted new occupational exposure limit values, marking significant updates to workplace safety regulations.
For instance, for the first time in forty years, the occupational exposure limit for lead has been revised, lowered from 0.15 mg/m³ to 0.03 mg/m³, with the biological limit value set at 15 µg Pb/100 ml (with a transitional limit of 30 µg Pb/100 ml valid until 2028).
An overall occupational exposure limit has been established for diisocyanates, set at 6 µg NCO/m³ for an 8-hour time-weighted average (TWA), and a short-term exposure limit of 12 µg NCO/m³.
This directive enters into force on April 2, 2024, and EU member states must transpose it into national law by April 9, 2026.
Metal Cleaning Chemicals Market Segmentation Analysis
Product Analysis
The aqueous category held the larger market share, of 70%, in 2024, and it will have the higher CAGR, of 5.1%, driven by the increasing environmental regulations and growing preference for safer cleaning alternatives. Aqueous cleaners are witnessing substantial demand due to their eco-friendly nature and efficient cleaning properties. The benefits associated with aqueous metal cleaning chemicals, including non-flammability, low or no VOCs, and limited health risks, are accelerating their adoption across various industries. Advanced aqueous formulations now incorporate sophisticated surfactant systems and chelating agents that rival the performance of traditional solvents while offering superior safety profiles.
The products analyzed in this report are:
Solvent
Aqueous (Larger and Faster-Growing Category)
Ingredient Analysis
The surfactants category held the largest market share, of 25%, in 2024, reflecting their fundamental role in metal cleaning formulations. Surfactants function as the primary cleaning agents by reducing surface tension and enabling the removal of both organic and inorganic contaminants. The development of bio-based surfactants derived from renewable resources is revolutionizing this segment, offering comparable performance to petroleum-based alternatives while addressing sustainability concerns.
The chelating agents category will have the highest CAGR, of 5.4%, driven by their critical role in managing water hardness and preventing redeposition of contaminants during the cleaning process. High levels of metal ions such as calcium and magnesium in hard water have a powerful influence on chemical processes and the performance of many products. Chelating agents effectively sequester these metal ions, ensuring consistent cleaning performance across varying water conditions and enhancing the overall efficiency of cleaning formulations.
The ingredients analyzed in this report are:
Surfactants (Larger Category)
Chelating Agents (Faster-Growing Category)
Solvents
pH Regulators
Solubilizers
Metal Type Analysis
The steel category held the largest market share, of 45%, in 2024, owing to steel's position as the most widely used industrial metal globally. According to the World Steel Association, in 2023, 1,888 million tonnes of steel were produced globally. The extensive use of steel in construction, automotive, manufacturing, and infrastructure projects necessitates substantial volumes of cleaning chemicals for surface preparation, maintenance, and finishing operations.
The aluminum category will have the highest CAGR, of 5.1%, owing to its increasing production all over the world. In general, steel is stronger, but when it comes to fabricating lightweight products with great strength, aluminum is preferred. This is because it possesses a superior strength-to-weight ratio. Additionally, its malleability, elasticity, and stronger rust resistance augment its appeal. As per reports, over 77 million tonnes of aluminum were consumed in 2024.
The metal types analyzed in this report are:
Steel (Larger Category)
Aluminum (Faster-Growing Category)
Copper
End User Analysis
The manufacturing category held the largest market share, of 50%, in 2024, due to the increasing demand for metallic products with outstanding performance, such as heavy machinery, equipment, reactors, tanks, and tools. From precision machinery components to large-scale industrial equipment, manufacturing facilities require consistent and reliable cleaning solutions to maintain production quality and equipment longevity. The segment encompasses various sub-industries, including machinery manufacturing, metal fabrication, and industrial equipment production, each with specific cleaning requirements. As per studies, the output of the global manufacturing sector in 2023 was USD 16.177 trillion.
The automotive category will have the highest CAGR, of 5.4%, due to the expanding global automotive production and the increasing complexity of vehicle manufacturing processes. The automotive industry's shift toward electric vehicles and lightweight materials is creating demand for specialized cleaning chemicals compatible with new materials and manufacturing processes. Additionally, stringent quality standards in automotive manufacturing necessitate high-performance cleaning solutions for pre-treatment before painting and assembly operations. As per the OICA, 92,504,338 vehicles were manufactured worldwide in 2024.
The end users analyzed in this report are:
Manufacturing (Larger Category)
Automotive (Fastest-Growing Category)
Aerospace
Healthcare
Construction
Drive strategic growth with comprehensive market analysis
Metal Cleaning Chemicals Market Regional Outlook
Asia-Pacific Metal Cleaning Chemical Market Size
Asia-Pacific held the largest market share, of 45%, in 2024, and it will have the highest CAGR, of 5.9%, due to the surging industrialization rate and increasing metal production in the developing economies in the region. The progressing manufacturing sector, particularly in China, India, and Japan, will drive the market expansion in the years to come. China, countries in ASEAN, Japan, and India have generated a strong demand for metal cleaning chemicals in the past few years.
The region benefits from substantial foreign direct investment in manufacturing facilities, creating a robust ecosystem for industrial cleaning chemical consumption. This increasing metal production and processing activity directly translates to higher demand for metal cleansing chemicals. The presence of major steel and aluminum producers in countries like China and India, combined with the region's position as a global manufacturing hub, reinforces its market leadership.
China Metal Cleaning Chemical Market Size
China dominates the market within Asia-Pacific due to the country's massive industrial base, spanning automotive, electronics, aerospace, and general manufacturing. Government initiatives promoting advanced manufacturing and environmental sustainability are influencing the market dynamics, with increasing adoption of eco-friendly cleaning solutions in industrial applications.
As part of the 14th Five-Year Plan, China has introduced a plan to strengthen safe chemical production, including risk-screening and early-warning systems, aiming to curb major accidents by 2025. Moreover, in December 2024, China drafted a law on the safety of hazardous chemicals to strengthen safety oversight across the full lifecycle of hazardous chemicals, banning high-risk online transactions and requiring strict risk management in chemical parks.
North America Metal Cleaning Chemical Market Size
North America holds the second-largest market share due to its mature industrial infrastructure and stringent regulatory framework promoting workplace safety and environmental protection. The region's focus on advanced manufacturing technologies and high-quality standards creates demand for premium cleaning solutions. The presence of major aerospace manufacturers, automotive OEMs, and precision manufacturing facilities drives the consumption of specialized metal cleansing chemicals. Moreover, the corporate sustainability initiatives, regulatory incentives for environmentally friendly products, and increasing awareness about the health impacts of traditional cleaning chemicals, further increases the market growth. Major end-users are implementing comprehensive chemical management programs that prioritize safer alternatives while maintaining operational efficiency.
U.S. Metal Cleaning Chemical Market Size
The U.S. dominates the market with its diverse industrial base and technological leadership in manufacturing processes. The country's emphasis on sustainable manufacturing practices and worker safety regulations has accelerated the adoption of bio-based and low-VOC cleaning formulations. The reshoring of manufacturing activities and investments in domestic production capacity are expected to further boost market growth during the forecast period. The EPA Safer Choice Program labels promote cleaning products that meet stringent hazard and environmental criteria. The products on the program’s Safer Chemical Ingredients List must be minimally toxic, biodegradable, and environmentally benign.
The geographical breakdown of the market is as follows:
North America
U.S. (Larger and Faster-Growing Country)
Canada
Europe
Germany (Largest and Fastest-Growing Country)
U.K.
France
Italy
Spain
Rest of Europe
Asia-Pacific (Largest and Fastest-Growing Regional Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil
Mexico (Largest and Fastest-Growing Country)
Rest of LATAM
Middle East and Africa
Saudi Arabia (Largest and Fastest-Growing Country)
South Africa
U.A.E.
Rest of MEA
Metal Cleaning Chemicals Market Share Analysis
The market is fragmented due to the presence of a large number of regional and niche players operating across different geographies. These companies often specialize in customized solutions tailored to specific industrial needs or local regulatory requirements. Additionally, the low to moderate entry barriers, along with rising demand from small and medium-scale industries, have allowed new entrants to emerge.
Key Metal Cleaning Chemicals Companies:
BASF SE
Eastman Chemical Company
Stepan Company
Quaker Chemical Corporation
Lincoln Chemical corporation
Evonik Industries AG
The Dow Chemical Company
The Chemours Company
Kyzen Corporation
Houghton International Inc.
Ecolab Inc.
Henkel AG & Co. KGaA
Metal Cleaning Chemicals Market News
In April 2025, Quaker Chemical Corporation completed the acquisition of Dipsol Chemicals Co. Ltd., a Japan-based specialist in surface treatment and plating chemicals serving automotive and industrial sectors, for approximately USD 153 million.
In April 2024, BASF SE expanded its EcoBalanced biomass-balanced product portfolio for detergent, cleaning, and industrial formulations, in Europe. These solutions reduce carbon footprint by substituting fossil inputs with renewable feedstocks while maintaining performance.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws