Manufacturing Execution System Market Insights (2027 - 2033)
This Report Provides In-Depth Analysis of the Manufacturing Execution System Market Report Prepared by P&S Intelligence, Segmented by Offering (Software, Services), Deployment Mode (On-Premises, Cloud / Software-as-a-Service (SaaS), Hybrid), Manufacturing Type (Discrete Manufacturing, Process Manufacturing), End-Use Industry Vertical (Automotive & Transportation, Pharmaceuticals & Life Sciences, Electronics & Semiconductors, Food & Beverages / CPG, Aerospace & Defense, Chemicals & Petrochemicals, Other End-Use Verticals), Organization Size (Large Enterprises, Small & Medium Enterprises (SMEs)), and Geographical Outlook for the Period of 2022 to 2033
Explore the market potential with our data-driven report
Manufacturing Execution System Market Outlook
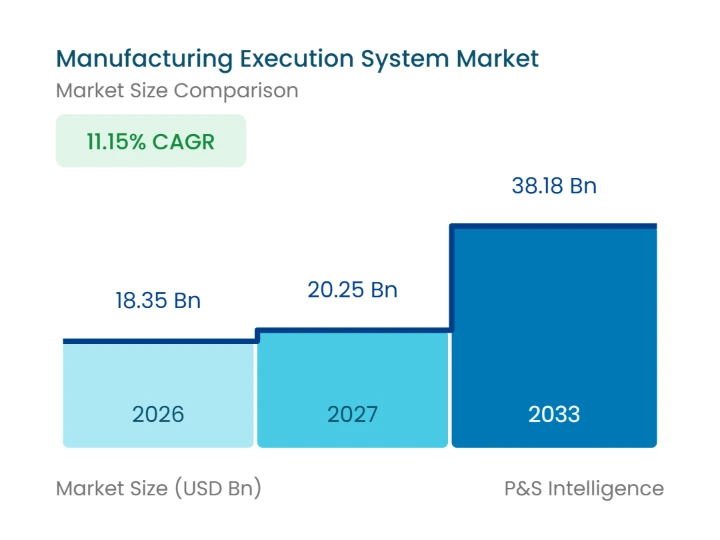
The global manufacturing execution system market size is estimated at USD 18.35 Billion in 2026 and is projected to reach USD 20.25 Billion in 2027. Spending on these systems is projected to rise to USD 38.18 Billion by 2033, advancing at a CAGR of 11.15% during 2027-2033. Plant managers in automotive, pharmaceutical, and electronics production are funding these systems to replace paper travelers and spreadsheet scheduling with line-level records that auditors and customers trust. For software vendors and system integrators, each project tends to pair a license or subscription with integration work, so services revenue rises alongside software sales.
Higher robot density on assembly and machining lines is pushing plant managers to fund execution software to schedule, track, and document automated work. According to the International Federation of Robotics, factories installed more than 600,000 industrial robots in 2025, lifting the global operational stock to a record 5 million units. That count sizes the automation base, not execution software adoption, yet every automated cell raises the cost of an untracked lot or an unplanned stop. Software that dispatches orders and captures genealogy at machine speed becomes easier to justify as automation spreads, supporting recurring orders for upgrades and new sites.
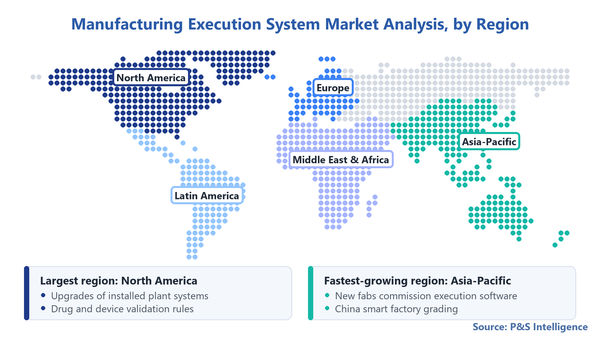
North America holds 36.5% of manufacturing execution system market revenue in 2026, led by the U.S., where pharmaceutical, aerospace, and automotive plants generate much of the spending through upgrades of systems already in service. Asia-Pacific is projected to expand at a 13.6% CAGR during 2027-2033, the quickest regional pace, as new semiconductor, electronics, and battery plants in China, India, Taiwan, and South Korea buy execution software at commissioning. North American revenue therefore depends more on replacement cycles and migration services, while Asia-Pacific orders tend to arrive with new capacity.
Key market insights
By offering, software holds 63.5% in 2026, while services is projected to advance at a 12.2% CAGR during 2027-2033.
By deployment mode, on-premises holds 49.0% in 2026, while cloud / software-as-a-service (SaaS) is projected to advance at a 16.8% CAGR during 2027-2033.
By manufacturing type, discrete manufacturing holds 53.0% in 2026, while process manufacturing is projected to advance at an 11.85% CAGR during 2027-2033.
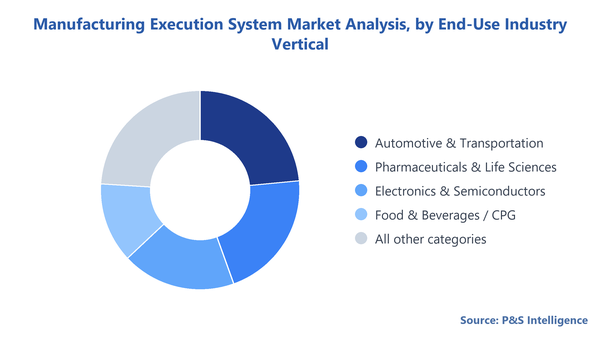
By end-use industry vertical, automotive & transportation holds 23.5% in 2026, while pharmaceuticals & life sciences is projected to advance at a 13.4% CAGR during 2027-2033.
By organization size, large enterprises holds 71.5% in 2026, while small & medium enterprises (SMEs) is projected to advance at a 13.1% CAGR during 2027-2033.
By geography, North America holds 36.5% in 2026, while Asia-Pacific is projected to advance at a 13.6% CAGR during 2027-2033.
Manufacturing Execution System Market Drivers & Opportunities
Composable shop-floor apps are reshaping how plants buy execution software
Plant engineering teams increasingly buy execution functions as separate applications, such as digital work instructions, quality checklists, and machine monitoring, instead of committing to a single multi-year suite rollout. A modular purchase lets one line go live quickly and spreads spending across operating budgets, which suits plants that cannot stop production for a full cutover. Established suite vendors have responded by adding low-code development tools to their platforms, as Siemens has done by pairing Opcenter with Mendix, so plant teams can now compare an app builder with a configurable enterprise product in the same evaluation.
Industrial investors are backing the modular model with capital. Tulip, a developer of no-code frontline operations software, announced a USD 120 million Series D round on January 13, 2026, led by Mitsubishi Electric, which brought the company's valuation to USD 1.3 billion. An automation hardware maker leading a software round suggests that equipment vendors see shop-floor apps as a way to stay involved in plant operations after the machine sale. Suite vendors could face more competition for the first line a plant digitizes, where a modular app is easiest to approve.
Skilled-labor shortages are driving spending on operator guidance software
Manufacturers that struggle to hire and retain experienced operators are buying execution software that puts work instructions, part verification, and quality checks on the screen at each station. When the system guides a newer operator through each step and blocks a wrong component or a skipped inspection, plants can protect yield without relying on long tenure, and supervisors spend less time reconciling paper records. These projects often start with electronic work instructions and data collection, then extend into dispatching and genealogy once plant teams trust the records.
Figures from the Manufacturing Institute put the U.S. need at as many as 3.8 million additional manufacturing employees between 2024 and 2033, with 1.9 million of those roles at risk of staying unfilled if skills and applicant gaps persist. A hiring gap of that size gives plant managers a labor-cost case for software that shortens operator training, which is easier to defend in a capital review than a general digitization goal. Vendors with strong operator-interface design and multilingual instruction content are better positioned for these first-phase orders.
New wafer fab start-ups are opening a high-value cleanroom software pipeline
Every new wafer fab needs an execution system running before first silicon, because lot dispatching, recipe control, and equipment status tracking flow through it from the first qualification wafer. Fab construction therefore works as a leading indicator for cleanroom execution licenses, integration contracts, and multi-year support agreements. These deployments also tend to carry higher software and services value per site than a typical discrete plant, since transaction volumes, automation interfaces, and uptime requirements are much heavier in a 300mm fab.
SEMI's third-quarter 2026 300mm Fab Outlook projects that 13 new 300mm fabs or production lines will begin operations or ship first silicon in 2026, rising to 23 in 2027. That count measures capacity coming online rather than software purchases, yet each new line needs an execution environment configured for its own tools and products. Suppliers already qualified with foundries and memory makers could convert this pipeline faster, and integrators with cleanroom experience gain implementation work that is hard to staff at short notice.
Legacy integration and validation workloads are constraining deployment speed
A typical brownfield plant runs machines from several vendors and decades, and connecting each one to an execution system requires custom interfaces, data mapping, and testing before the first order can be dispatched. In regulated plants, every configuration change also needs validation documentation, and connected production software now goes through cybersecurity review by corporate IT. These steps can stretch multi-site programs across several years, which delays license and subscription revenue for vendors and leads some smaller plants to postpone the purchase.
Vendors are responding with architectures that support staged rollouts. Rockwell Automation introduced FactoryTalk ResilientEdge on June 18, 2026, an execution layer built on FactoryTalk Optix and integrated with its Plex MES, which the company says keeps operations running if connectivity is lost and can be deployed in phases. Staged deployment lowers up-front disruption, yet it does not remove interface work on older equipment. Integration capacity is likely to remain a bottleneck on how quickly the installed base converts, which keeps experienced OT integrators busy.
Segmentation Outlook
Offering
Software holds 63.5% of manufacturing execution system market revenue in 2026, since licenses and subscriptions carry the functions every plant pays for, including dispatching, genealogy, quality records, and performance tracking. Each added line, site, or module expands seat counts and functional scope, and maintenance or subscription fees recur for as long as the system runs the floor. Plants rarely replace execution software mid-life, because routings, recipes, and historical records live inside it, which gives the installed base a steady revenue stream.
Services is projected to post the fastest growth in this axis, at a 12.2% CAGR during 2027-2033, as manufacturers migrate older on-premises systems, connect execution data to cloud ERP systems, and roll common templates across sites. Every migration needs interface building, data conversion, and, in regulated plants, validation testing, so services revenue grows with project complexity more than with seat count. System integrators with prior references in a plant's own industry are better positioned to win this work, because plants weigh sector experience heavily when choosing an implementation partner.
Deployment Mode
On-premises deployments hold 49.0% of revenue in 2026, as many plants want execution logic to run on local servers regardless of wide-area network status. Validated pharmaceutical lines, defense suppliers, and semiconductor fabs also tend to keep production data inside the plant to simplify audits, export-control compliance, and change control. Large sites with long-standing licenses and their own server rooms have little reason to move a working system, so this category depends heavily on upgrades and support renewals.
Cloud / software-as-a-service (SaaS) deployment is set to expand at a 16.8% CAGR during 2027-2033, the quickest pace among deployment models, because subscriptions remove up-front license and server spending. Vendor-managed upgrades also reduce the IT staffing burden that has held back smaller and multi-site manufacturers. Edge components that keep lines running during network outages address the main operational objection to cloud execution. For vendors, the shift turns one-time license sales into recurring subscriptions, which smooths revenue but makes customer retention the metric that matters most.
Manufacturing Type
Discrete manufacturing holds 53.0% of revenue in 2026, led by automotive, aerospace, electronics, and machinery plants that assemble products from many serialized parts. These plants need part-level genealogy so a defective component can be traced to every finished unit, which supports recalls, warranty claims, and customer audits. Frequent product-mix changes on assembly lines also make detailed scheduling and electronic work instructions daily tools. Suppliers with strong serial tracking and configuration management are better positioned in this category.
Process manufacturing is projected to post the highest growth in this axis, at an 11.85% CAGR during 2027-2033. Pharmaceutical, biotechnology, chemical, and food plants are replacing paper batch records with electronic batch records, which lets quality teams release compliant batches through review by exception instead of page-by-page checks. Recipe management and weigh-and-dispense control also reduce batch deviations, and each avoided deviation can protect a high-value lot. Vendors with ISA-88 batch libraries and prevalidated content can shorten these projects, which matters to plants that count downtime in lost batches.
End-Use Industry Vertical
Automotive & transportation holds 23.5% of revenue in 2026. Vehicle and component plants run high-volume lines where a wrong part can trigger a field recall, so carmakers require traceable production records. Global vehicle production rose from 92.7 million units in 2024 to 96.4 million in 2025, according to the International Organization of Motor Vehicle Manufacturers (OICA). That output sizes the production base automotive plants serve and is no measure of software adoption, though model launches and line retooling often reopen execution software budgets.
Pharmaceuticals & life sciences is set to post the quickest expansion among end-use verticals, at a 13.4% CAGR during 2027-2033. Drug and device makers face strict record-keeping rules, and electronic batch and device history records shorten product release times. The U.S. Food and Drug Administration issued final guidance on computer software assurance for production and quality system software on September 24, 2025, aimed at helping device manufacturers adopt new technologies. Its risk-based assurance approach can cut the documentation burden of new deployments, which removes one reason device makers delayed replacing paper systems.
Copyright P&S Intelligence. Reuse requires attribution under CC BY 4.0.
Organization Size
Large enterprises hold 71.5% of revenue in 2026. Multi-plant manufacturers have the IT staff, budgets, and compliance exposure to fund enterprise-wide programs, and they often standardize one execution platform across many sites to compare performance and shift products between plants. Their contracts also bundle integration with ERP and product lifecycle management systems, which raises the value of each deal and lengthens vendor relationships.
Small & medium enterprises (SMEs) are projected to grow at a 13.1% CAGR during 2027-2033, the highest rate in this axis. Subscription pricing and prebuilt apps lower the entry cost for plants without a dedicated IT team. Eurostat data show that 85% of large EU businesses bought cloud computing services in 2025, against 52% of SMEs, in a survey covering all business sectors. That gap leaves room for cloud purchasing to spread among smaller firms, which would make subscription execution software easier to approve. Vendors with self-service onboarding and regional channel partners can reach this segment at lower sales cost.
The following segments are analysed in this report.
Offering
Software
Services
Deployment Mode
On-Premises
Cloud / Software-as-a-Service (SaaS)
Hybrid
Manufacturing Type
Discrete Manufacturing
Process Manufacturing
End-Use Industry Vertical
Automotive & Transportation
Pharmaceuticals & Life Sciences
Electronics & Semiconductors
Food & Beverages / CPG
Aerospace & Defense
Chemicals & Petrochemicals
Other End-Use Verticals
Organization Size
Large Enterprises
Small & Medium Enterprises (SMEs)
Geographical Analysis
North America manufacturing execution system market outlook
North America holds 36.5% of global revenue in 2026, the largest regional share. The U.S. is the region's largest market, with a dense base of pharmaceutical, medical device, aerospace, and automotive plants that already run execution software and now pay to upgrade, migrate, or extend it to more lines. Validation rules for drug and device production and traceability demands from defense primes keep compliance-heavy modules in steady demand, while Canada adds automotive parts and food processing sites.
New plant construction adds a second layer of demand. The U.S. Census Bureau recorded manufacturing construction spending at a seasonally adjusted annual rate of USD 170.2 billion in September 2026, covering facilities such as semiconductor, chemical, and electrical equipment plants, many of which will start production during the forecast period. Most of those sites typically put execution software in place before output begins. Construction spending has eased from its recent peak, so the region's growth is likely to lean more on replacing legacy systems and moving them to cloud or hybrid models, which favors suppliers with deep migration services.
Asia-Pacific manufacturing execution system market growth
Asia-Pacific is set to post the quickest regional expansion, at a 13.6% CAGR during 2027-2033. Demand comes largely from new capacity, as semiconductor fabs, electronics assembly plants, and battery factories across China, Taiwan, South Korea, Japan, India, and Southeast Asia install execution software at commissioning. India is the region's fastest-growing market, supported by public semiconductor investment and new electronics assembly lines that start with digital records from the first day of output.
China's state grading of smart factories widens the base of plants ready for execution software. Ministry of Industry and Information Technology (MIIT) figures released in January 2026 count more than 7,000 advanced smart factories and over 500 excellence-level smart factories built in China. The MIIT grades measure factory capability and do not count software installations, although reaching those grades typically involves digital production management. Suppliers with local-language support, data residency options, and integration partners inside China are better positioned for this work.
Copyright P&S Intelligence. Reuse requires attribution under CC BY 4.0.
Europe market analysis
Europe ranks third in revenue, behind North America and Asia-Pacific, with demand shaped more by regulation and engineering-led upgrades than by new plant construction. Germany, France, Italy, and the Nordic countries host automotive, machinery, chemical, and pharmaceutical plants with long-installed execution systems, some of which are due for modernization or migration to newer platforms. EU rules on product traceability and good manufacturing practice push plants to keep detailed digital records at the unit or batch level.
Battery producers face a specific deadline. The European Commission lists February 18, 2027, as the date from which the battery passport becomes mandatory for relevant battery categories placed on the EU market, including industrial and electric vehicle batteries. The rule sets data obligations for the battery itself and does not require any particular execution software, yet cell and pack plants need reliable production records to supply passport data. Suppliers with battery-specific genealogy modules and experience at European cell plants could see more orders as producers prepare.
Latin America market analysis
Latin America contributes a smaller share of global revenue, with demand centered on Mexico and Brazil. Mexican automotive, electronics, and medical device plants that supply U.S. customers often adopt the execution platforms their parent companies or customers specify, so purchases follow corporate standards set abroad. Local demand therefore tends to appear as rollout, localization, and support work for integrators more than as new vendor selections. Brazil's food, beverage, and chemical producers form a second buyer pool, where batch tracking and quality records support export sales.
Foreign investment keeps adding plants that arrive with these standards. As per Mexico's Ministry of Economy, the country received USD 40.87 billion of foreign direct investment in 2025, the highest annual figure on record. That total spans every sector of the economy, yet new foreign-owned production sites usually carry the parent company's execution software requirements into the country. Global vendors with Spanish-language support and local integration partners in Monterrey, Guadalajara, and the Bajío corridor are better positioned to capture these rollouts.
Middle East & Africa market analysis
Middle East & Africa accounts for the smallest share of global revenue, with early demand concentrated in Saudi Arabia, the U.A.E., Israel, and South Africa. Gulf governments are using industrial policy to move manufacturing away from low-wage labor toward automated production, and new plants in petrochemicals, metals, pharmaceuticals, and food processing are being designed with digital operations from the start. On these greenfield sites, the execution system is often specified within the plant engineering contract, which channels orders through the engineering firms and integrators that design the facility.
Saudi Arabia's Ministry of Industry and Mineral Resources runs the Future Factories Program, which aims to transform about 4,000 factories into smart, automated facilities through assessments, transformation plans, and incentives. The program sets a target and is no record of completed software purchases, so demand will build as individual factories move from assessment to implementation. Vendors and integrators with a local presence in Riyadh and Dammam, and Arabic-language operator interfaces, are better positioned to win the projects these plans generate.
The following geographies are analysed in this report.
North America
U.S.
Canada
Asia-Pacific
Japan
South Korea
Taiwan
China
India
Malaysia
Singapore
Thailand
Vietnam
Indonesia
Philippines
Australia
Rest of Asia-Pacific
Europe
Germany
U.K.
France
Italy
Netherlands
Spain
Switzerland
Sweden
Belgium
Austria
Finland
Denmark
Rest of Europe
Latin America
Brazil
Mexico
Chile
Argentina
Colombia
Rest of Latin America
Middle East & Africa
Saudi Arabia
U.A.E.
Israel
Qatar
Oman
Kuwait
South Africa
Egypt
Morocco
Nigeria
Rest of Middle East & Africa
Manufacturing Execution System Market Competition Analysis
The manufacturing execution system market share is spread across a moderately fragmented field, because plant requirements differ so sharply by industry that no single platform fits every buyer. A wafer fab, a biologics plant, and an automotive assembly line need different data models, regulatory records, and equipment interfaces, so vertical specialists compete alongside broad suites. High switching costs make installed positions durable, since routings, recipes, and validated records sit inside the system, yet cloud subscriptions and modular apps are lowering entry costs for newer vendors. The structure is evolving as acquisitions and ownership changes regroup product lines.
Competition runs along three clusters. Industrial automation and enterprise software groups, including Siemens AG, Rockwell Automation, Inc., Dassault Systèmes SE, SAP SE, and Schneider Electric's AVEVA, sell broad suites tied to their control, design, or ERP portfolios. That breadth helps them win multi-site standardization programs. Vertical specialists such as Körber AG, Applied Materials, Inc., and Critical Manufacturing compete on prevalidated industry content for pharmaceutical, semiconductor, and high-tech discrete plants. Modular and mid-market providers, including Tulip Interfaces, Inc. and Epicor Software Corporation, target plants that want faster deployment and subscription pricing.
For buyers, this structure means vendor choice usually follows the plant's industry and its ERP or automation standard, and the decision tends to hold for many years once production records accumulate in the system. Implementation partners therefore carry real influence over selection, and vendors without a strong partner network in a buyer's region or sector often struggle to reach the short list, even when their software compares well on functionality.
Major Companies in Manufacturing Execution System Market:
Siemens AG
Rockwell Automation, Inc.
Dassault Systèmes SE
SAP SE
Honeywell International Inc.
ABB Ltd.
Emerson Electric Co.
Schneider Electric SE / AVEVA Group Limited
Applied Materials Inc.
Körber AG
Critical Manufacturing (ASMPT)
Velotic
Oracle Corporation
Tulip Interfaces Inc.
Epicor Software Corporation
MPDV Mikrolab GmbH
Aegis Industrial Software Corporation
Parsec Automation Corp.
Infor Inc.
Manufacturing Execution System Market News
In August 2026, Dassault Systèmes SE was selected by JSW Greentech, the electric commercial vehicle arm of the JSW Group, to implement DELMIA Apriso MES at a new 90-acre plant in Chhatrapati Sambhajinagar, Maharashtra, planned for 10,000 e-buses and 5,000 e-trucks a year. The award shows Indian greenfield vehicle plants specifying execution software before output begins.
In August 2026, Critical Manufacturing S.A., a subsidiary of ASMPT Limited, partnered with UST to deploy its MES-based Industrial Operations Platform for semiconductor and electronics manufacturers in India and Southeast Asia, with UST providing consulting, implementation, and local delivery. The alliance adds local engineering capacity in a region where new fabs and assembly lines are commissioning execution software.
In June 2026, Schneider Electric SE signed an agreement to acquire Cognite, an industrial data and AI software company with 2025 revenue above USD 170 million, for USD 3.1 billion in cash, with Cognite to be integrated into AVEVA once the deal closes. The pending deal would give AVEVA's execution software users a dedicated industrial data and AI layer on its CONNECT platform.
In May 2026, Körber AG announced PAS-X Neo, a cloud-native, software-as-a-service MES for small and mid-sized pharmaceutical companies and sites that needs no local infrastructure, with the first version scheduled for November 2026. The launch extends a pharma-focused MES line to sites that lack the IT resources for a full on-premises deployment.
In March 2026, Velotic launched as an independent industrial software company, combining the Proficy business that TPG Inc. bought from GE Vernova Inc. for USD 600 million with PTC Inc.'s Kepware and ThingWorx lines. The launch moves Proficy, a portfolio serving more than 20,000 customers that includes MES, out of an energy equipment group and into a company focused on industrial software.
In January 2026, Aegis Industrial Software Corporation completed its acquisition of Simio, a provider of digital twin simulation and advanced planning and scheduling software taught at more than 500 higher education institutions. The deal adds simulation-based scheduling to Aegis's manufacturing operations software, a function plants often buy separately from execution systems.
Last Updated: November 2026
Frequently Asked Questions About This Report
How big is the manufacturing execution system market?+
The global manufacturing execution system market size is estimated at USD 18.35 Billion in 2026 and is projected to reach USD 20.25 Billion in 2027.
What is the growth rate of the MES market?+
Spending on these systems is projected to rise to USD 38.18 Billion by 2033, advancing at a CAGR of 11.15% during 2027-2033.
Which region dominates the manufacturing execution system market?+
North America holds 36.5% of manufacturing execution system market revenue in 2026, led by the U.S., where pharmaceutical, aerospace, and automotive plants generate much of the spending through upgrades of systems already in service.
Which region is growing fastest in the MES market?+
Asia-Pacific is projected to expand at a 13.6% CAGR during 2027-2033, the quickest regional pace, as new semiconductor, electronics, and battery plants in China, India, Taiwan, and South Korea buy execution software at commissioning.
Is cloud MES growing faster than on-premises MES?+
Cloud / Software-as-a-Service (SaaS) deployment is set to expand at a 16.8% CAGR during 2027-2033, the quickest pace among deployment models, because subscriptions remove up-front license and server spending.
Which industry uses MES the most?+
Automotive & Transportation holds 23.5% of revenue in 2026. Vehicle and component plants run high-volume lines where a wrong part can trigger a field recall, so carmakers require traceable production records.
Who are the major manufacturing execution system vendors?+
Industrial automation and enterprise software groups, including Siemens AG, Rockwell Automation, Inc., Dassault Systèmes SE, SAP SE, and Schneider Electric's AVEVA, sell broad suites tied to their control, design, or ERP portfolios.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws