District Heating Market Size & Share Analysis - Emerging Trends, Growth Opportunities, Competitive Landscape, and Forecasts (2025 - 2032)
This Report Provides In-Depth Analysis of the District Heating Market Report Prepared by P&S Intelligence, Segmented by Heat Source (Coal, Natural Gas, Renewables, Oil and Petroleum Products), Component (Boiler, Insulated Pipeline, Pumps, Heat Exchanger, Heat Meters), Plant Type (Boiler Plants, Combined Heat and Power), Application (Residential, Industrial, Commercial), and Geographical Outlook for the Period of 2019 to 2032
Explore the market potential with our data-driven report
District Heating Market Future Outlook
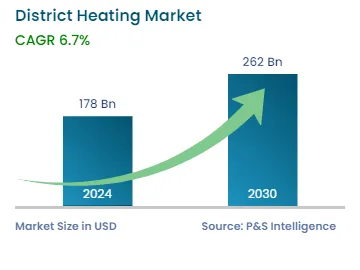
The district heating market size stood at USD 178 billion in 2024, and it is expected to witness a compound annual growth rate of 6.7% during 2025–2032, to reach USD 262 billion by 2032.
The major trend in the market is the usage of renewable sources of heat, such as bioenergy, heat pumps, solar–thermal, and geothermal, and even waste heat from industries and data centers. At the moment, the heat generated from renewable sources accounts for just 8% of the global production.
The market is driven by the increasing population of cities, which leads to rapid urbanization around the world. Due to this shift from rural to urban areas, the demand for energy is increasing across all the end-use sectors. Due to this, substantial investments have been made in district heating systems. For instance, in the U.K., an investment of around USD 310 million has been made since 2018 for developing district heating projects, such as in East Devon and London. With cities growing at a fast rate, the demand for efficient and reliable utility services is increasing.
The rapid industrialization is another key factor driving the market, as the excess heat from industries can be used as a heat source in these systems. On the other hand, the heat generated from these systems can be used in chemical plants, refineries, and paper factories.
In April 2025, ENGIE SA secured a 13-year concession agreement with Rennes Métropole to develop a green district heating network powered entirely by biomass and recovered energy. The investment totals EUR 156 million, expanding the network by 78 km and serving around 47,000 households.
District Heating Market Trends & Drivers
Integration of Renewable Energy Sources Is Major Trend
The global transition toward clean energy is significantly accelerating technological innovation in district heating systems.
In 2023, renewable energy met 15.9% of global building energy demand, including space heating.
Only 11.5% of space heating specifically came from modern renewables in 2021.
Despite slow progress, the IEA forecasts renewables will supply 21% of building heating needs by 2028, driven by bioenergy, heat pumps, and solar.
Modern district heating networks are increasingly integrating renewable sources such as biomass, geothermal, solar thermal, and waste heat recovery to enable sustainable and low-carbon urban heating solutions.
Fourth-generation district heating systems operate at lower temperatures and facilitate more efficient integration of renewable energy and heat pumps, thereby improving overall system performance and reducing distribution losses.
In December 2024, ENGIE SA completed a majority stake purchase (70.7%) in District Heating Eco Energías, a developer of biomass-powered urban heating networks in Ávila, Spain.
The project is designed to run on forest biomass, underscoring ENGIE’s commitment to renewable-based district heating infrastructure.
The lower operational temperatures also enhance economic viability and environmental performance by minimizing heat dissipation during energy transmission.
Globally, geothermal energy is used for space heating via district systems and ground-source heat pumps. Iceland’s Svartsengi and Nesjavellir plants supply hot water for tens of thousands of households.
New Zealand has around 31 MWt installed capacity for direct space heating, alongside dozens of heat pump systems in public and commercial buildings.
Regulatory frameworks worldwide are evolving to support renewable integration in heating infrastructures.
Governments are implementing mandates, carbon pricing mechanisms, and renewable energy subsidies, which incentivize clean energy adoption within district heating.
These regulatory pressures and financial stimuli are prompting increased investments in R&D initiatives, leading to continuous advancements in district heating technologies.
Overall, the convergence of policy drivers, technological innovation, and environmental priorities is positioning renewable-integrated district heating as a key component in the global decarbonization agenda.
Rising Global Level of Urbanization Is Key Driver for Market
The rapid pace of global urbanization is a key driver for the expansion of the district heating market worldwide.
Currently, 55% of the global population resides in urban regions, a figure anticipated to rise to 68% by the year 2050, says the World Urbanization Prospects 2018 edition of the UN-DESA.
Cities account for approximately two-thirds of global energy consumption and over 70% of greenhouse gas emissions, according to the World Bank.
Urban areas create ideal conditions for district heating due to high population density, centralized infrastructure, and close building proximity.
District heating systems offer cost-effective and energy-efficient solutions in dense urban environments by leveraging economies of scale.
Increasingly, urban planners view district heating as a foundational element of sustainable urban infrastructure, contributing to reduced emissions and optimized land use.
In June 2023, Fortum Corporation decided to invest approximately EUR 225 million over 2023–2027 in the Espoo Clean Heat program, including the construction of heat pump plants for waste heat recovery and 15 km of new district heating pipes.
Ongoing urban growth is generating substantial investment opportunities in district heating infrastructure.
Governments in major metropolitan regions are supporting district heating initiatives through large-scale infrastructure programs and favorable policy frameworks.
District Heating Market Segmentation Analysis
Heat Source Analysis
The natural gas category held the largest market share, of 45%, in 2024, because it offers high energy efficiency, widespread availability, and lower emissions compared to other fossil fuels like coal and oil. It is also well-integrated into existing infrastructure, particularly in developed regions such as Europe, North America, and parts of Asia, where combined heat and power (CHP) plants are commonly used. Many countries have transitioned from coal and oil to natural gas to meet short- and medium-term emission targets while maintaining a reliable heat supply, making it the most relied-upon source for district heating systems globally.
However, due to the increasing efforts for achieving net-zero emissions by 2050, the renewables category will be the fastest-growing in the forecast period. This would essentially be due to the joint efforts of countries for decarbonization. Currently, the initiatives in the European region for the integration of renewables in district heating systems, with around 25% of its energy produced from clean sources, make it one of the key regions in the market.
The heat sources analyzed here are:
Coal
Natural Gas (Largest Category)
Renewables (Fastest-Growing Category)
Oil and Petroleum Products
Plant Type Analysis
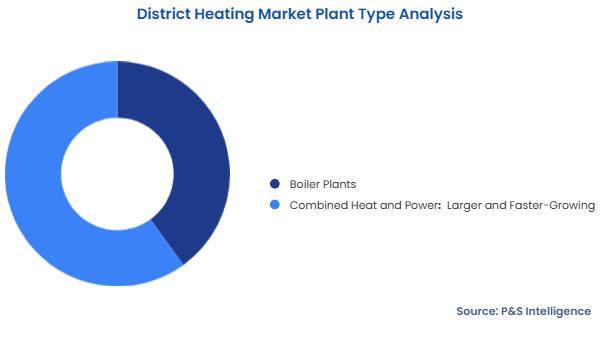
The combined heat and power category held the larger market share in 2024, and it will grow at the higher CAGR, of approximately 7%, during the forecast period, due to the cost-effectiveness and high sustainability of this approach. The cogeneration of electricity and heat is beneficial as the loss of energy while transferring it to another plant for electricity generation is minimal or extremely low. It also helps in reducing carbon emissions and operating costs, facilitating the integration of renewable energy sources, and improving the flexibility of critical infrastructure and the electrical power system.
CHP systems are majorly used in industrial, large commercial, and institutional applications; therefore, with the high rate of industrialization, this category is advancing rapidly. These systems also help reach economies of scale, which further makes technologies such as thermal energy storage or biomass more affordable to implement and operate.
The plant types analyzed here are:
Boiler Plants
Combined Heat and Power (CHP) (Larger and Faster-Growing Category)
Component Analysis
Boilers are the largest category in the market due to urbanization and the shift toward sustainable energy. Boilers efficiently provide centralized heat, reducing emissions and energy waste. Increasing government support for clean energy infrastructure further drives adoption, making boilers essential in modern, eco-friendly heating solutions worldwide.
The heat pump category within the component segment is expected to grow at the highest rate in the forecast period, due to the rising usage of technologically advanced systems. Heat pumps in these networks help in reducing heat loss and integrating renewable power in electricity networks, by running when the production of renewable power is high. They also help in increasing the temperature of the heat generated, which is used in different industries, such as chemical, refining, and paper.
With the increasing industrialization rate globally, the demand for heat pumps is rising in district heating networks. These pumps ultimately help in decreasing the consumption of energy and stabilizing the energy prices.
The components analyzed here are:
Boiler (Largest Category)
Insulated Pipeline
Pumps (Fastest-Growing Category)
Heat Exchanger
Heat Meters
Application Analysis
The residential category held the largest market share in 2024, and it will grow at the highest CAGR, during the forecast period, attributed to the increasing number of households globally. With the increasing level of urbanization, there is a rise in the need for energy. This, in turn, drives the modernization of the heating infrastructure, to make it apt for providing energy to modern homes. They are also cost-effective, as the owners share the cost of heating a building, and only one boiler is needed for the whole building, instead of one per residence. The advancements in smart home technologies are also a driver of the increasing demand.
In cold countries, such as Denmark, Sweden, and Russia, 40–50% of the heating requirements of buildings are fulfilled by these solutions, which lead to energy efficiency.
The applications analyzed here are:
Residential (Largest and Fastest-Growing Category)
Industrial
Commercial
Drive strategic growth with comprehensive market analysis
District Heating Market Geographical Analysis
Europe District Heating Market Size
The European region held the largest share of the market revenue, of more than 35%, in 2024. This was due to the rising demand for energy in the region, backed by the increasing industrialization and urbanization, as well as the growing preference for energy-efficient systems, and government regulations to reduce greenhouse emissions. The low temperature in most of the region for most of the year is also one of the factors that make Europe the biggest market for these systems.
Additionally, many new geothermal district heating plants are being constructed in the region to utilize clean energy. In this regard, the development of the region’s biggest such facility was announced at the beginning of 2022, and it will be partly operational by 2025. The KeepWarm project, under which the modernization of 16 pilot district heating systems has begun in Central and Western Europe, and many more projects are contributing to the market advance.
APAC District Heating Market Size
APAC will be the fastest-growing region in the forecast period, due to the booming industries, rapid urbanization, and constantly changing climate. Additionally, the increasing disposable income and rising concerns related to the emission of CO2 are the key driving factors for this market in the APAC region.
Moreover, China is the biggest market in the region due to the huge investments being poured into district heating systems, such as the one in Heilongjiang province, which is supported by the Asian Development Bank (ADB). It will cater to 1.21 million urban residents in six cities.
The following is the geographical breakdown of the market:
North America
U.S. (Larger Country Market)
Canada (Faster-Growing Country Market)
Europe (Largest Regional Market)
Germany (Largest Country Market)
U.K. (Fastest-Growing Country Market)
France
Italy
Spain
Rest of Europe
Asia-Pacific (Fastest-Growing Regional Market)
Japan
China (Largest Country Market)
India (Fastest-Growing Country Market)
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country Market)
Mexico (Fastest-Growing Country Market)
Rest of LATAM
Middle East and Africa
Saudi Arabia (Largest Country Market)
South Africa (Fastest-Growing Country Market)
Rest of MEA
District Heating Market Competitive Landscape
The district heating market is consolidated due to high capital intensity, complex technical requirements, and the advantage of economies of scale in infrastructure development and operations. Established companies maintain dominance through their extensive distribution networks, multi-regional presence, and long-term project experience. Additional factors contributing to consolidation include the need for regulatory compliance, integration of renewable energy sources, and increasing reliance on digital technologies for system optimization. These elements create significant barriers to entry, limiting participation to firms with strong financial and technical capabilities.
Key District Heating Companies:
Fortum Group
Vattenfall AB
ENGIE SA
Danfoss Group
Statkraft AS
LOGSTOR Denmark Holding ApS
Vital Energi Ltd.
The KELAG-K
Shinryo Corporation
Keppel Corporation Limited
Uniper SE
General Electric
District Heating Market News
In June 2025, Mijnwater won a grant worth EUR 13.5 million from the European Commission to develop its sustainable district heating and cooling network in Zuid-Limburg, Netherlands. This funding is being allocated through the Public Sector Loan Facility (PSLF), an essential element of the Just Transition Mechanism, which aids regions in their shift toward a climate-neutral economy. The grant is facilitated by a EUR 90-million loan from the European Investment Bank (EIB) to Enexis, which will then be utilized to finance its subsidiary, Mijnwater Warmte Infra B.V.
In January 2025, Solör Bioenergy Group announced an agreement to acquire the district heating activities of E.ON SE in Åkersberga, north of Stockholm.
In March 2024, Fortum Group announced the development of a new emissions-free and electricity-based district heating production facility in the Nuijala area of Espoo, Finland, featuring a 50-MW electric boiler and an 800 MWh heat accumulator to enhance production flexibility.
In March 2024, Hitachi Energy Ltd. secured a significant contract to provide grid connection solutions in Finland for the world's largest data center heat recovery initiative, enabling the replacement of fossil fuels with sustainable energy sources in Helsinki's district heating infrastructure.
In February 2024, Uniper SE and Evonik Industries AG launched the Technical Options for Thermal Energy Recovery (TORTE) project in Gelsenkirchen, expected to supply approximately 1,000 homes in the Ruhr region through industrial waste heat integration into district heating networks.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws