This Report Provides In-Depth Analysis of the Brain Implant Market Report Prepared by P&S Intelligence, Segmented by Type (Deep Brain Stimulation, Spinal Cord Stimulation, Vagus Nerve Stimulation), Application (Parkinson's Disease, Chronic Pain, Epilepsy, Depression, Essential Tremor, Alzheimer's Disease), and Geographical Outlook for the Period of 2021 to 2032
Explore the market potential with our data-driven report
Brain Implant Market Overview
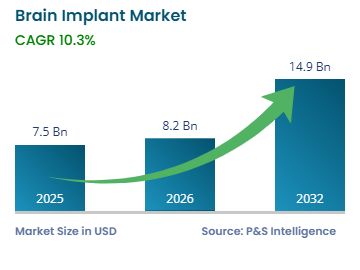
The brain implant market size was USD 7.5 billion for 2025, and it will grow by 10.3% during 2026–2032, to reach USD 14.9 billion by 2032.
This growth is supported by the rising clinical adoption of deep brain stimulation across movement disorders, expanding regulatory pathways for adaptive neurostimulation, and accelerating investment in closed-loop, sensor-enabled implant architectures. In parallel, advancements in minimally invasive implantation techniques, wireless connectivity, artificial intelligence, and real-time neural-signal processing are further improving the functionality, precision, and personalization of implantable neurostimulation systems.
Regulatory validation is reinforcing commercial momentum. The U.S. Food and Drug Administration (FDA) approved Medtronic's BrainSense Adaptive Deep Brain Stimulation system in February 2025, making it the first FDA-approved adaptive DBS technology for Parkinson's disease that uses brain signals to adjust stimulation in real time. Additionally, growing investment by medical-device companies, research institutions, and technology firms in BCI development is further supporting the commercialization of advanced brain implants and creating opportunities for applications in paralysis rehabilitation, communication assistance, and neurological disease management.
Key Market Insights
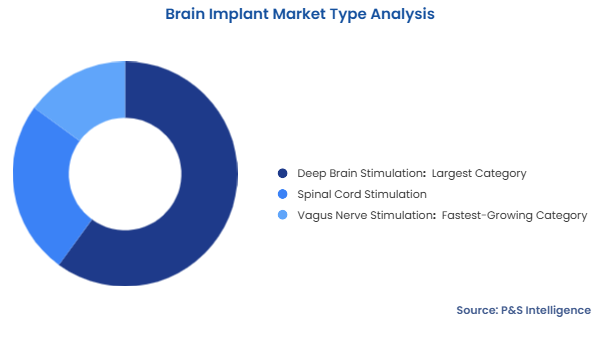
The deep brain stimulation category holds the largest market share, of 60%, in 2025, driven by established clinical use and a trained neurosurgical base.
The vagus nerve stimulation category will have the highest CAGR, of approximately 10.6%, driven by expanding clinical use, lower-risk implantation, and device miniaturization.
The parkinson’s disease category holds the largest market share, of 35%, in 2025, supported by established DBS use and clinical experience.
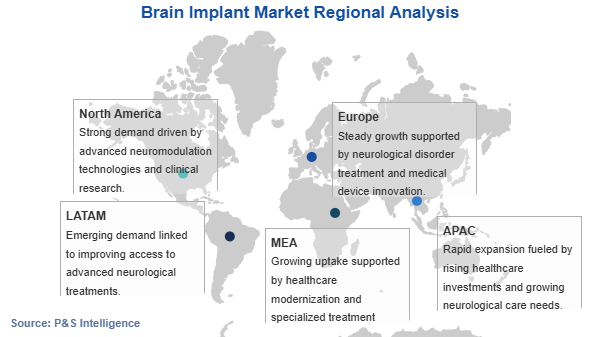
North America holds the largest market share, of 40%, in 2025, supported by mature healthcare infrastructure and favorable reimbursement.
Asia-Pacific will have the highest CAGR, of approximately 11.2%, driven by expanding neurosurgical capacity and healthcare access.
Brain Implant Market Trends and Drivers
Adaptive, Closed-Loop Neurostimulation Technologies Are Key Trends
The market is being reshaped by a shift from fixed-parameter stimulation toward adaptive, closed-loop systems capable of sensing neural activity in real time and adjusting therapy accordingly. This technological transformation is reducing the manual programming burden on clinicians, shortening time-to-therapeutic-benefit for patients, and enabling more individualized treatment than earlier generation devices allowed. The trend is also moving neurostimulation toward continuous monitoring, with implantable systems increasingly incorporating sensing capabilities that capture neural biomarkers alongside stimulation delivery.
A peer-reviewed review in the National Center for Biotechnology Information (NCBI) database notes a consistent upward trend in annual DBS procedure volumes, with U.S. admissions exceeding 5,500 patients, reflecting sustained clinical adoption of DBS. The continued expansion of DBS is occurring alongside advances in neural sensing, adaptive stimulation, and biomarker-based programming, which are enabling more responsive and personalized treatment approaches. Manufacturers are increasingly integrating sensing, stimulation, and software-based programming into unified platforms, while research is advancing algorithms that can identify patient-specific neural patterns and automatically modify stimulation parameters. This trend is expected to accelerate as manufacturers advance sensing-enabled electrode arrays and adaptive stimulation technologies, while closed-loop approaches continue to develop at different stages across DBS, VNS, and RNS applications.
Aging Populations and Rising Neurological Disease Burden Are Biggest Drivers
The expanding global burden of neurological disease is a primary structural driver of brain implant adoption. As populations age across major economies, the absolute number of people living with neurological conditions such as Parkinson's disease, epilepsy, and dementia is increasing. This increase in prevalence is expanding the potential patient pool for advanced neurological therapies and surgical interventions. Improving diagnostic capabilities and greater access to specialized neurological care are compounding this dynamic. These improvements are increasing the identification and referral of patients whose symptoms remain inadequately controlled with conventional treatment. According to the WHO's 2024 analysis of Global Burden of Disease (GBD) 2021 data, an estimated 3.4 billion people worldwide were living with neurological conditions in 2021. This figure represents 43.1% of the global population. Demographic aging and longer life expectancy have driven the increase in absolute neurological burden since 1990.
The WHO reports that epilepsy affects around 50 million people worldwide, making it one of the most common neurological diseases globally. A treatment gap remains, as the WHO reports that up to 70% of people with epilepsy could become seizure-free with appropriate diagnosis and treatment. Access to care remains limited in low- and middle-income countries. As healthcare systems improve diagnosis, specialist access, and treatment pathways, more patients with difficult-to-control neurological conditions are likely to enter specialist care, expanding the pool of patients requiring advanced neurological interventions and supporting sustained demand for brain implants.
Global Neurosurgical Workforce Shortages Is Key Restraint
Despite underlying demand, the market faces a structural restraint in the limited global supply of neurosurgeons qualified to perform complex implantation procedures. Brain implant placement requires highly specialized surgical training and multidisciplinary clinical support, which remain unevenly distributed worldwide. A 2025 peer-reviewed analysis reported an estimated deficit of approximately 23,300 neurosurgeons across Africa and Southeast Asia. This shortage limits the number of specialized centers capable of performing complex implant procedures and creates long waiting times and geographic barriers for patients seeking advanced neurological therapies.
The workforce gap is challenging in low- and middle-income countries, where neurosurgeons and specialized healthcare infrastructure are concentrated in major urban and academic centers. Limited availability of trained specialists restricts patient evaluation, surgical eligibility assessment, implantation, and post-operative programming and follow-up, all of which are essential for successful brain-implant therapy. As neurosurgical training requires several years of specialized education and supervised practice, expanding the workforce is a gradual process. Shortages in specialist capacity are likely to remain a constraint on brain-implant adoption in underserved regions, even as clinical indications and device technologies continue to expand.
Expanding Brain-Computer Interface Applications Is Biggest Opportunity
Beyond traditional neurostimulation, the convergence of implant technology with brain-computer interface research is opening therapeutic pathways beyond movement disorders and epilepsy, including motor-function restoration for paralysis, communication assistance, and applications in neurological, neuropsychiatric, and sensory disorders. The opportunity is expanding as invasive BCI technologies move from laboratory research toward first-in-human and early-stage clinical studies. The NIH BRAIN Initiative currently supports FDA-regulated clinical trials of novel invasive technologies targeting conditions including Parkinson’s disease, epilepsy, depression, stroke, tremor, visual loss, deafness, and paralysis.
Recent clinical progress is further demonstrating the potential for BCI systems to move beyond controlled research environments. In July 2026, the NIH reported results from an NIH-funded clinical trial in which a person with paralysis used an implanted BCI at home to convert attempted speech into spoken words, with the participant using the system for more than 3,800 hours over nearly 23 months. At the same time, the BRAIN Initiative is supporting translational programs and commercialization training designed to move validated neurotechnologies from laboratories into clinical applications and the marketplace. These developments create an opportunity for brain implants to expand into communication restoration, motor rehabilitation, sensory restoration, and other therapeutic applications, broadening the addressable market beyond conventional neurostimulation.
Brain Implant Market Segmentation Analysis
Type Analysis
The deep brain stimulation category holds the largest market share, of 60%, in 2025, driven by decades of clinical validation across movement disorders and an established base of trained implanting neurosurgeons familiar with stereotactic targeting procedures. A growing pipeline of adaptive, sensing-enabled systems has renewed clinical interest in the technology and expanded its role in the management of appropriately selected patients with advanced movement disorders. The Parkinson's Foundation estimates that nearly 1.2 million people in the U.S. will be living with Parkinson's disease by 2030, compared with approximately 930,000 today. This expanding patient population provides a growing underlying pool for advanced Parkinson's therapies, including DBS where clinically appropriate.
The vagus nerve stimulation category will have the highest CAGR, of approximately 10.6%, driven by expanding clinical evidence supporting VNS use beyond its original epilepsy indication, broader physician familiarity with its comparatively lower-risk implantation profile relative to intracranial procedures, and continued device miniaturization improving patient tolerability. Supporting its clinical expansion, a 2025 study reported a median 77% reduction in generalized tonic-clonic seizure frequency after 24 months of adjunctive VNS, with 42.6% of participants reporting seizure freedom during the three months preceding the 24-month assessment.
The parkinson’s disease category holds the largest market share in 2025, driven by one of the longest-established clinical evidence bases for surgical neuromodulation, well-established referral pathways connecting movement-disorder neurologists with implanting surgical teams, and extensive clinical experience with DBS for advanced Parkinson's disease. The Parkinson's Foundation reports that nearly 90,000 people are diagnosed with Parkinson's disease in the U.S. each year, almost double previous estimates of annual diagnoses, reinforcing the growing underlying patient population for advanced Parkinson's therapies, including DBS where clinically appropriate.
The alzheimer's disease category will have the highest CAGR, of approximately 11.8%, driven by early-stage clinical trials investigating responsive neurostimulation targeting memory-circuit structures such as the fornix and entorhinal cortex, a rapidly expanding patient population, and continued unmet clinical needs as available treatment options remain limited, particularly as the disease progresses. According to the 2025 Alzheimer's Disease Facts and Figures report, an estimated 7.2 million Americans aged 65 and older were living with Alzheimer's dementia in 2025, with this number projected to reach approximately 13.8 million by 2060. The expanding disease burden, combined with ongoing research into implant-based approaches for memory and cognitive function, creates a potential long-term opportunity for brain implants in Alzheimer's disease.
The applications analyzed in this report are:
Parkinson's Disease (Largest Category)
Chronic Pain
Epilepsy
Depression
Essential Tremor
Alzheimer's Disease (Fastest-Growing Category)
Drive strategic growth with comprehensive market analysis
Brain Implant Market Regional Analysis
North America Brain Implant Market Size
North America holds the largest market share, of 40%, in 2025, sustained by a mature neurosurgical infrastructure with dedicated movement-disorder and epilepsy surgery programs at major academic medical centers, a favorable reimbursement environment for neurostimulation procedures under both public and private payers, and an accelerating regulatory pathway that has cleared successive generations of adaptive, sensor-driven implant technology. The concentration of leading device manufacturers headquartered in the region further reinforces early commercial access to new therapies.
Recent clinical evidence further underscores the established role of DBS in the U.S.; a 2026 nationwide study analyzed 79,845 adults hospitalized with Parkinson’s disease between 2018 and 2023, including 482 patients who underwent DBS implantation, and found that DBS was associated with significantly lower risks of institutionalization and mortality, as well as lower healthcare expenditures. National Institute of Neurological Disorders and Stroke (NINDS) reports that a NINDS-funded clinical trial demonstrated deep brain stimulation was superior to best medical therapy for reducing Parkinson's disease symptoms and improving motor function.
Asia-Pacific Brain Implant Market Size
Asia-Pacific will have the highest CAGR, of approximately 11.2%, driven by rapidly expanding neurosurgical capacity in China and India, rising government investment in domestic neurotechnology manufacturing, and improving diagnosis rates for Parkinson's disease and epilepsy as healthcare access broadens across the region's large, aging population base. The region is also benefiting from the rapid development of brain-computer interfaces (BCIs), with China emerging as a major center for clinical research and commercialization. China’s national BCI strategy targets major technological breakthroughs by 2027 and the development of globally competitive BCI companies by 2030, while more than 10 invasive BCI clinical trials were reported to be active in the country in early 2026.
China's National Medical Products Administration (NMPA) granted the world's first commercial marketing approval for an invasive brain-computer interface medical device in March 2026, marking a significant step toward the commercialization of implantable neurotechnology in Asia. The device is designed to help patients with quadriplegia caused by cervical spinal-cord injuries regain hand-grasping ability, demonstrating the expansion of brain implants from conventional neurostimulation toward motor-function restoration. Asia Pacific's growth trajectory is expected to strengthen further as China targets a globally competitive neurotechnology sector by 2030, while Japan and South Korea continue to expand brain-science and medical-device research. Cross-border commercialization is also gaining support through regulatory convergence: APEC economies are working to streamline medical-product approvals, reduce duplicated reviews and inspections, and increase reliance on regulatory assessments across markets, while ASEAN's 10 member states are harmonizing medical-device requirements to reduce technical barriers to trade and improve market access.
India Brain Implant Market Size
India is fastest-growing market within Asia Pacific, supported by expanding DBS capabilities and increasing adoption of advanced neurostimulation technologies. A 2026 multicentre survey of 50 clinicians across 37 DBS centres in 18 Indian cities found that 84% of respondents were using BrainSense technology, while 90% intended to incorporate adaptive DBS into routine clinical practice. This indicates growing adoption of sensing-enabled and adaptive neurostimulation across India's specialist movement-disorder centres and supports the country's transition toward next-generation brain-implant technologies.
India is also strengthening its domestic brain-implant manufacturing capabilities. In 2026, the Government of India reported that an indigenous deep brain stimulator developed through collaboration between Sree Chitra Tirunal Institute for Medical Sciences and Technology (SCTIMST) and Bhabha Atomic Research Centre (BARC) had reached Technology Readiness Level 7, with the technology transferred to Shree Pacetronix Ltd. for commercialization and industrial scale-up. In March 2026, Apollo Hospitals also reported India's first clinical activation of adaptive DBS for Parkinson's disease, demonstrating the country's progress toward real-time and personalized neurostimulation. These developments strengthen India's position as an emerging regional hub for indigenous DBS development, adaptive neurostimulation, and next-generation implantable neurotechnology.
These regions and countries are analyzed:
North America (Largest Regional Market)
U.S. (Larger Country)
Canada (Faster-Growing Country)
Europe
Germany (Largest Country)
U.K. (Fastest-Growing Country)
France
Italy
Spain
Rest of Europe
Asia-Pacific (Fastest-Growing Regional Market)
China (Largest Country)
India (Fastest-Growing Country)
Japan
South Korea
Australia
Rest of APAC
Latin America
Brazil (Largest Country)
Mexico (Fastest-Growing Country)
Rest of LATAM
Middle East & Africa
Saudi Arabia (Largest Country)
South Africa
U.A.E. (Fastest-Growing Country)
Rest of MEA
Brain Implant Market Competitive Landscape
The market is consolidated, with a limited number of established medical-device manufacturers holding strong positions across major implantable neurostimulation categories. High barriers to entry reinforce this structure. Stringent regulatory requirements, lengthy clinical validation, R&D expenditure, specialized manufacturing capabilities, and intellectual-property protection make up these barriers. New entrants must establish clinical evidence, physician confidence, distribution networks, and long-term patient-support capabilities before achieving commercial scale. Established companies benefit from decades of clinical experience, regulatory expertise, established relationships with neurosurgeons and neurologists, and integrated product portfolios. This combination makes it difficult for smaller competitors to gain market share quickly. The complexity of combining implantable hardware, electrodes, stimulation systems, sensing technologies, and programming software favors companies with extensive technical and financial resources. Emerging BCI companies are increasing competition in specialized applications, but their limited commercial scale has not yet materially changed the consolidated competitive structure.
Leading Companies in Brain Implant Market:
Medtronic plc
Abbott Laboratories
Boston Scientific Corporation
LivaNova PLC
NeuroPace, Inc.
Neuralink Corp.
Synchron Inc.
Precision Neuroscience Corporation
Paradromics Inc.
Blackrock Neurotech LLC
CorTec GmbH
Aleva Neurotherapeutics SA
Brain Implant Market Developments
In April 2026, Medtronic plc launched its real-time, sensor-based Adaptive Deep Brain Stimulation system for Parkinson's disease in India. The launch extends Medtronic's adaptive neuromodulation portfolio into a large emerging market with a growing Parkinson's disease burden and expanding access to specialized neurosurgical care.
In March 2026, Paradromics Inc. launched its APEX Partnership Program, establishing collaborations with academic researchers to expand applications of its high-data-rate BCI platform and accelerate translation of BCI research into commercial applications.
In January 2026, Precision Neuroscience Corporation and Medtronic plc entered into a strategic partnership to integrate Precision's Layer 7 Cortical Interface with Medtronic's StealthStation surgical navigation system. The collaboration is intended to combine high-resolution cortical mapping with an established neurosurgical platform and accelerate clinical adoption of Precision's technology.
In November 2025, Synchron Inc. raised USD 200 million in a Series D financing round. The financing is accelerating development and commercialization of the company's Stentrode brain-computer interface, including pivotal clinical trials and next-generation BCI technology development. Stentrode is implanted through the blood vessels via the jugular vein. This approach avoids open-brain surgery.
In June 2025, Neuralink Corp. closed a USD 650 million Series E funding round, with participation from investors including ARK Invest and Sequoia Capital. The financing is supporting patient access to Neuralink's BCI technology, development of future devices, and expansion of the company's clinical-trial program across international sites.
Frequently Asked Questions About This Report
What are the major factors driving growth in the brain implant market?+
Market growth is driven by the rising burden of neurological disorders, aging populations, increasing adoption of neuromodulation therapies, advances in adaptive and sensing-enabled implants, expanding clinical indications, and improvements in specialized neurosurgical infrastructure.
What are the major opportunities emerging in the market?+
Major opportunities include the expansion of brain-computer interfaces into motor and communication restoration, development of adaptive and closed-loop stimulation, AI-enabled neural signal processing, indigenous implant manufacturing in emerging markets, and expansion of neurostimulation into additional neurological and psychiatric indications.
How are brain-computer interfaces expanding the addressable market?+
BCIs are expanding the market beyond traditional DBS, VNS, and RNS applications into motor-function restoration, communication assistance, and other assistive or therapeutic applications for people with severe neurological disabilities, with clinical trials and early commercial approvals accelerating therapeutic adoption.
What role is AI playing in the development of brain implants?+
AI is enabling more precise interpretation of neural signals, automated identification of biomarkers, adaptive stimulation, personalized programming, and improved clinical decision support, helping brain implants become more responsive and individualized.
How are partnerships, collaborations, acquisitions, and product launches shaping the competitive landscape?+
Companies are using partnerships, collaborations, acquisitions, and product launches to combine implant hardware, neural sensing, software, AI, and surgical-navigation capabilities, expand product portfolios, accelerate commercialization, and enter new therapeutic applications.
How are clinical trials and regulatory developments influencing the adoption of brain implants?+
Clinical trials are generating evidence on safety, efficacy, and new indications, while regulatory approvals are enabling commercialization of next-generation technologies and expanding the clinical applications of adaptive DBS, responsive neurostimulation, and invasive BCIs.
Want a report tailored exactly to your business need?
Leading companies across industries trust us to deliver data-driven insights and innovative solutions for their most critical decisions. From data-driven strategies to actionable insights, we empower the decision-makers who shape industries and define the future. From Fortune 500 companies to innovative startups, we are proud to partner with organisations that drive progress in their industries.
Client Testimonials
Working with P&S Intelligence and their team was an absolute pleasure – their awareness of timelines and commitment to value greatly contributed to our project's success. Eagerly anticipating future collaborations.
McKinsey & Company
India
Unmatched Standards
Our insights into the minutest levels of the markets, including the latest trends and competitive landscape, give you all the answers you need to take your business to new heights
Complete Data Security
We take a cautious approach to protecting your personal and confidential information. Trust is the strongest bond that connects us and our clients, and trust we build by complying with all international and domestic data protection and privacy laws