Automotive Tire Market Size Revenue Insights
Key Highlights
| Study Period | 2021 - 2032 |
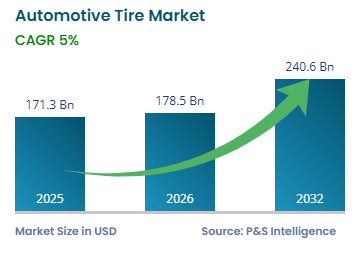
| Market Size in 2025 | USD 171.3 Billion |
| Market Size in 2026 | USD 178.5 Billion |
| Market Size by 2032 | USD 240.6 Billion |
| Projected CAGR | 5% |
| Largest Region | Asia-Pacific |
| Fastest-Growing Region | Asia-Pacific |
| Market Structure | Consolidated |
Market Size
Explore the market potential with our data-driven report
Automotive Tire Market Key Insights
- The passenger cars category holds the largest market share, of 45% in 2025, driven by the dominant global passenger vehicle fleet.
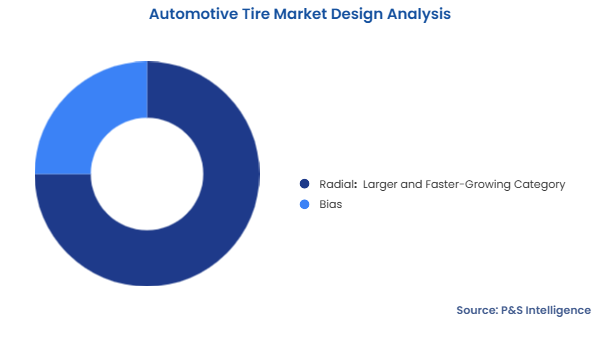
- The radial category holds the larger market share of 75% in 2025, and it will have the higher CAGR, due to superior durability and fuel efficiency.
- The aftermarket category holds the larger market share, of 70% in 2025, supported by continuous replacement demand cycles.
- The OEM category will have the higher CAGR, of approximately 5.4%, driven by rising vehicle production and increasing integration of advanced tire technologies in new vehicles.
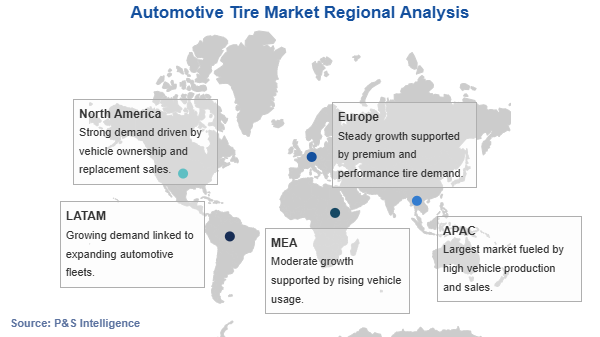
- Asia-Pacific holds the largest market share, of 40% in 2025, and it will have the highest CAGR, of approximately 5.9%, driven by high vehicle production and expanding mobility demand.
Automotive Tire Market Future Outlook
The automotive tire market size was USD 171.3 billion for 2025, and it will grow by 5.0% during 2026–2032, to reach USD 240.6 billion by 2032.
The market growth is driven by rising global vehicle production, expanding vehicle parc, and increasing demand for replacement tires driven by wear cycles and regulatory safety requirements. Tires remain a critical safety and performance component in automotive systems, directly influencing vehicle efficiency, fuel consumption, and road safety outcomes.
The expansion of the global vehicle fleet is structurally reinforcing tire demand across both OEM and replacement segments. According to the International Organization of Motor Vehicle Manufacturers, global vehicle production exceeded 93 million units in 2023, reflecting a recovery in automotive manufacturing. Additionally, the International Energy Agency estimates that the global car fleet surpassed 1.4 billion vehicles, generating a substantial recurring demand base for replacement tires. Regulatory frameworks are also reinforcing demand, with agencies such as the National Highway Traffic Safety Administration mandating tire performance and safety standards, including tread depth and labeling requirements. In addition, advancements in tire technology, including fuel-efficient designs and enhanced durability features, are supporting performance optimization and compliance with evolving regulatory standards across global markets.
Automotive Tire Market Trends and Drivers
Electric Vehicle Proliferation Is Key Trend Accelerating Demand for Specialized Tire Formulations
A defining trend in the automotive tire market is the rapid emergence of electric vehicle (EV)-specific tire formulations designed to address unique performance requirements such as higher torque, increased vehicle weight, and reduced noise levels. EVs generate instant torque and impose higher stress on tires, requiring specialized tread compounds, reinforced structures, and low rolling resistance designs. This is shifting product development priorities toward advanced materials and performance optimization.
The global transition toward electrification is accelerating this trend. According to the International Energy Agency, global electric car sales exceeded 14 million units in 2023, representing over 18% of total car sales. Regulatory mandates, including the European Union’s CO₂ emission reduction targets and China’s New Energy Vehicle (NEV) policies, are further expanding EV adoption. Tire manufacturers are responding with dedicated EV tire lines featuring silica-based compounds and noise-reduction technologies. As EV penetration increases, specialized tire formulations are expected to become a standard requirement, reshaping product differentiation across the market.
Rising Global Vehicle Production and Fleet Expansion Are Biggest Drivers
Rising vehicle production and the continuous expansion of the global vehicle fleet represent the primary drivers of the automotive tire market. Global production and fleet data reinforce this demand structure. The OICA reports strong recovery in global vehicle manufacturing, while the World Bank highlights rising motorization rates in emerging economies. Additionally, urbanization and logistics expansion are increasing vehicle utilization rates, accelerating tire wear.
The growth of e-commerce has significantly increased last-mile delivery fleets, particularly LCVs, further driving replacement tire demand. As manufacturers scale with rising demand, Bridgestone’s April 2024 move to develop sustainable tire materials using recycled and renewable inputs highlights efforts to strengthen supply and support long-term growth. This dual demand structure, OEM supply and high-frequency replacement, continues to sustain market expansion.
Raw Material Price Volatility Is Key Restraint
Raw material price volatility represents a major constraint on margin stability across the automotive tire market. Tire manufacturing depends heavily on natural rubber, synthetic rubber, carbon black, and crude oil derivatives, all of which are subject to significant price fluctuations. Raw materials typically account for a substantial share of total tire production costs, making manufacturers highly sensitive to even minor commodity price movements. These variations directly impact production costs and profitability for manufacturers.
According to the Food and Agriculture Organization, natural rubber prices have experienced cyclical volatility due to supply-demand imbalances and climate-related disruptions in major producing countries. The geographic concentration of natural rubber production in Southeast Asia further amplifies supply-side risks, as adverse weather conditions and export dynamics can quickly tighten global supply. Additionally, crude oil price fluctuations affect synthetic rubber and petrochemical inputs. Supply chain disruptions, as highlighted by the Organisation for Economic Co-operation and Development, have further intensified cost pressures. In response, tire manufacturers often implement price increases or cost optimization measures to offset input cost inflation, though competitive pressures limit full cost pass-through. These factors limit pricing flexibility and compress margins, particularly in highly competitive aftermarket segments, thereby constraining overall market profitability.
Sustainable and Smart Tire Technologies Are Biggest Opportunities
The development of sustainable and smart tire technologies presents a substantial opportunity for market participants. Environmental regulations are tightening across major markets, and consumer awareness of tire-related carbon footprints is rising. Both forces are expanding demand for tires manufactured from renewable or recycled materials. EU tire labeling regulations are pushing manufacturers toward fuel-efficient and low-emission tire designs, accelerating adoption of sustainable materials. Major manufacturers are responding with investment in bio-based compounds and circular economy production models. Michelin has been developing tires with high sustainable material content under its long-term environmental strategy, establishing a benchmark for sustainable material integration at scale.
Smart tire technology is advancing along a parallel track. Embedded sensor-based smart tire systems enable real-time monitoring of pressure, tread, and load, supporting predictive maintenance and reducing fleet downtime. For instance, Goodyear Tire & Rubber Company's connected tire solutions extend this capability further, supporting predictive maintenance and fleet optimization through continuous data capture beyond the point of sale. These technology platforms are opening new service-based revenue streams for manufacturers, allowing product differentiation that price competition alone cannot replicate.
Automotive Tire Market Segmentation Analysis
Vehicle Analysis
The passenger cars category holds the largest market share, of 45%, in 2025, driven by the dominant share of passenger vehicles in the global automotive fleet. High vehicle ownership levels, particularly in developed and emerging economies, generate sustained demand for both OEM and replacement tires in this segment. Additionally, product innovation in this segment remains strong, as demonstrated by Michelin’s continued development of high-performance and sustainable passenger car tires to meet evolving consumer and regulatory requirements.
The LCVs category will have the highest CAGR, of approximately 5.3%, supported by rapid expansion in e-commerce logistics and last-mile delivery networks. This category is further supported by the expansion of urban logistics infrastructure highlighted by government-backed mobility and transport initiatives globally, while industry players are aligning with this demand, such as Continental AG developing commercial vehicle tire solutions focused on durability and fleet efficiency for last-mile delivery operations.
The vehicles analyzed in this report are:
- Two-Wheelers
- Passenger Cars (Largest Category)
- Light Commercial Vehicles (LCVs) (Fastest-Growing Category)
- Medium and Heavy Commercial Vehicles (M&HCVs)
Design Analysis
The radial category holds the larger market share, of 75%, in 2025, and it will have the higher CAGR, driven by its superior durability, fuel efficiency, and performance characteristics compared to bias tires. Radial tires provide better traction, longer tread life, and reduced rolling resistance, making them the preferred choice across passenger and commercial vehicles. This dominance is further reinforced by regulatory frameworks such as the European Union’s tire labeling regulations and fuel efficiency standards, which favor low rolling resistance and high-performance tire characteristics typically achieved through radial construction. Moreover, manufacturers such as Bridgestone are expanding advanced radial tire offerings to meet evolving performance and sustainability requirements.
The designs analyzed in this report are:
- Radial (Larger and Faster-Growing Category)
- Bias
Type Analysis
The all-season tires category holds the largest market share in 2025, driven by their versatility across varying weather conditions, making them the default choice in regions with moderate climates where seasonal tire changes are neither required nor economically practical. Consumer preference for cost-effective, low-maintenance solutions has cemented this position, as single-set ownership removes the logistical and financial burden of maintaining separate seasonal fitments.
The winter tires category will have the highest CAGR, of approximately 5.7%, driven by stringent safety regulations in cold-climate regions and rising consumer awareness of seasonal tire performance. Government mandates across Austria and Germany require winter tires under defined weather conditions or during specified periods, generating consistent and predictable seasonal replacement demand.
The types analyzed in this report are:
- Summer Tires
- All-Season Tires (Largest Category)
- Winter Tires (Fastest-Growing Category)
End Use Analysis
The aftermarket category holds the larger market share, of 70%, in 2025, supported by continuous replacement demand driven by tire wear and regulatory requirements. Replacement cycles vary based on usage, road conditions, and vehicle type, creating a recurring revenue stream for manufacturers. According to the European Tyre and Rubber Manufacturers’ Association, replacement consumer tyre volumes in Europe reached approximately 223 million units in 2024, highlighting the strong and recurring demand in the aftermarket segment.
The OEM category will have the higher CAGR, driven by rising vehicle production and increasing integration of advanced tire technologies in new vehicles. OEM partnerships with automotive manufacturers are also strengthening growth in this segment. Increasing vehicle production and rising demand for technologically advanced tires, particularly for electric and premium vehicles, are supporting OEM segment growth.
The end uses analyzed in this report are:
- Original Equipment Manufacturer (OEM) (Faster-Growing Category)
- Aftermarket (Larger Category)
Drive strategic growth with comprehensive market analysis
Automotive Tire Market Geographical Outlook
Asia-Pacific Automotive Tire Market Size
Asia-Pacific holds the largest market share, of 40%, in 2025, and it will have the highest CAGR, of approximately 5.9%, driven by the region’s position as the global hub for automotive production and vehicle ownership expansion. China, India, Japan, and Southeast Asian countries collectively account for a significant share of global vehicle manufacturing, which directly translates into strong OEM tire demand. Based on data from the International Organization of Motor Vehicle Manufacturers (OICA), Asia-Oceania’s share of global vehicle production increased from 59.3% to 61.4%, while China’s share rose from 33.7% to 35.8%, reinforcing the region’s dominance in tire consumption. Additionally, rising disposable income and expanding middle-class populations are increasing vehicle ownership rates.
Government policies are further supporting market growth. China’s automotive production ecosystem, supported by industrial policies and EV adoption mandates, continues to generate high tire demand, while India’s automotive sector is expanding under initiatives such as domestic manufacturing incentives. The Automotive Tyre Manufacturers’ Association reports that India’s tire exports exceeded INR 23,000 crore in FY 2023–24, reflecting the country’s growing role in global tire supply alongside strong domestic demand. Increasing road infrastructure development across emerging economies is also improving vehicle utilization rates, accelerating tire wear cycles and replacement demand.
China Automotive Tire Market Size
China represents the largest country market within Asia-Pacific, anchoring regional dominance through its unmatched scale of vehicle production and domestic consumption. China produced over 31.2 million vehicles in 2024, making it the largest automotive market globally and a key driver of OEM and replacement tire demand. China's tire manufacturing sector operates on a highly integrated domestic supply chain. Natural rubber processing, synthetic rubber production, carbon black manufacturing, and steel cord fabrication are all sourced domestically, enabling cost-competitive output at scale. Government policies under the Made in China 2025 initiative and the national New Energy Vehicle mandate are compelling tire manufacturers to accelerate development of low-rolling-resistance and acoustically optimized tire designs. According to the International Energy Agency, electric LCV sales in China reached approximately 450,000 units in 2024, growing by nearly 90% year-on-year, accelerating demand for EV-compatible tire formats across both OEM and aftermarket channels. The country's growing premium vehicle segment is also shifting demand toward larger rim sizes and higher-value products. Rising disposable incomes and increasing sales of SUVs and luxury models are driving this upgrade in consumer tire preferences.
North America Automotive Tire Market Size
North America represents a mature but significant market, driven by a large installed vehicle base and strong replacement tire demand. The U.S. dominates the regional market, supported by high vehicle ownership rates and extensive road infrastructure. According to the U.S. Department of Transportation, the U.S. has over 280 million registered vehicles, creating a substantial and recurring replacement tire market.
The region also shows strong adoption of advanced tire technologies, including smart tires and EV-specific tire solutions. Increasing electric vehicle penetration, supported by federal incentives and emissions regulations, is driving demand for specialized tire formulations. Additionally, stringent safety and performance standards enforced by regulatory bodies are supporting premium tire adoption. These factors sustain steady market growth in North America despite its maturity.
The regions and countries of the market are as follows:
- North America
- U.S. (Larger and Faster-Growing Country Market)
- Canada
- Europe
- Germany (Largest Country Market)
- U.K.
- France
- Italy
- Spain (Fastest-Growing Country Market)
- Rest of Europe
- Asia-Pacific (Largest and Fastest-Growing Regional Market)
- China (Largest Country Market)
- India (Fastest-Growing Country Market)
- Japan
- South Korea
- Australia
- Rest of APAC
- Latin America
- Brazil (Largest Country Market)
- Mexico (Fastest-Growing Country Market)
- Rest of LATAM
- Middle East and Africa
- Saudi Arabia (Fastest-Growing Country Market)
- South Africa (Largest Country Market)
- U.A.E.
- Rest of MEA
Automotive Tire Market Competitive Landscape
The market is consolidated at the manufacturing level, where a small group of dominant Tier-1 players controls a significant share of global revenue and sets key technical standards. Leading companies such as Michelin, Bridgestone Corporation, The Goodyear Tire & Rubber Company, Continental AG, and Pirelli & C. S.p.A. dominate the market through strong global presence, advanced research and development capabilities, and long-standing relationships with automotive OEMs. These companies lead in premium and technologically advanced tire segments, reinforcing their competitive advantage. However, the broader market also includes numerous regional and mid-sized manufacturers such as Apollo Tyres Ltd, Giti Tire, Sailun Group, and Zhongce Rubber Group Co., Ltd., which primarily compete in aftermarket and price-sensitive segments, contributing to a diverse and competitive landscape.
Key Players in the Automotive Tire Market:
- Compagnie Generale des Etablissements Michelin SCA
- Bridgestone Corporation
- The Goodyear Tire & Rubber Company
- Continental AG
- Pirelli & C. S.p.A.
- Sumitomo Rubber Industries
- Hankook Tire & Technology
- The Yokohama Rubber Company
- Zhongce Rubber Group Co., Ltd.
- Apollo Tyres Ltd
- Nokian Tyres Plc
- Cheng Shin Rubber Industry Co., Ltd.
Automotive Tire Market News
- In January 2025, Goodyear Tire & Rubber Company completed the sale of its Dunlop brand rights in Europe, North America, and Oceania to Sumitomo Rubber Industries for approximately USD 701 million. The move is part of Goodyear’s strategy to streamline its brand portfolio and focus on core premium segments.
- In September 2024, Nokian Tyres Plc inaugurated a new passenger car tire manufacturing facility in Romania designed as a zero-CO₂ emissions plant powered by renewable energy, aimed at supplying European markets.
- In July 2024, Yokohama Rubber Co., Ltd. acquired the Off-the-Road tire business of Goodyear Tire & Rubber Company for approximately USD 905 million, strengthening its mining and commercial tire portfolio.
- In June 2024, Compagnie Generale des Etablissements Michelin SCA entered into OEM partnerships with global automakers for EV-optimized tire fitments, focusing on low rolling resistance and high durability tire solutions designed for electric and premium passenger vehicles.